" height="21.382199999999997px" id="kC7fwj2cp" transform="translate(43.2 8.135)" width="13.727599999999995px"/><path d="M 4.136 9.621 C 4.607 11.498 6.131 12.702 8.243 12.702 C 10.062 12.702 11.088 11.908 11.616 11 L 15.957 11 C 14.696 14.286 11.999 16.485 8.243 16.485 C 3.726 16.485 0 12.789 0 8.242 C 0 3.696 3.726 0 8.243 0 C 10.385 0 12.934 0.998 14.636 3.08 C 15.897 4.664 16.66 6.806 16.338 9.621 Z M 11.999 6.366 C 11.353 4.634 9.739 3.786 8.127 3.786 C 6.191 3.786 4.872 4.9 4.226 6.366 Z" fill="rgb(255, 255, 255)" height="16.4851px" id="gR7ROinvv" transform="translate(57.746 13.913)" width="16.41157892546896px"/><path d="M 4.752 0 L 7.685 9.944 L 10.617 0 L 15.369 0 L 9.914 15.399 L 5.455 15.399 L 0 0 Z" fill="rgb(255, 255, 255)" height="15.3991px" id="gNXCG2VXg" transform="translate(74.406 14.471)" width="15.369199999999992px"/><path d="M 15.372 6.631 C 15.372 10.502 12.056 13.202 8.801 13.202 L 1.937 13.202 L 1.937 21.385 L 0 21.385 L 0 0 L 8.801 0 C 12.056 0 15.372 2.67 15.372 6.629 Z M 1.939 11.821 L 8.951 11.821 C 11.443 11.821 13.437 9.561 13.437 6.629 C 13.437 3.696 11.531 1.379 8.951 1.379 L 1.939 1.379 Z" fill="rgb(255, 255, 255)" height="21.38469px" id="hre4mzAEc" transform="translate(91.857 8.135)" width="15.371899999999997px"/><path d="M 15.372 12.907 C 13.73 14.901 11.646 16.455 7.95 16.455 C 4.254 16.455 0 13.257 0 8.243 C 0 3.228 4.164 0 7.95 0 C 11.736 0 13.493 1.349 15.372 3.608 L 15.372 0.588 L 17.279 0.588 L 17.279 15.93 L 15.372 15.93 Z M 8.773 15.076 C 12.499 15.076 15.577 12.056 15.577 8.273 C 15.577 4.489 12.584 1.469 8.801 1.469 C 5.017 1.469 1.967 4.462 1.967 8.245 C 1.967 12.029 4.96 15.079 8.771 15.079 Z" fill="rgb(255, 255, 255)" height="16.455199999999998px" id="qtTPusYyi" transform="translate(106.698 13.943)" width="17.27900000000001px"/><path d="M 4.93 2.039 C 2.555 3.271 1.937 5.47 1.937 6.146 L 1.937 15.912 L 0 15.912 L 0 0.543 L 1.937 0.543 L 1.937 3.446 C 1.995 3.358 2.936 1.539 5.045 0.543 C 7.157 -0.425 8.448 0.19 8.506 0.22 L 8.506 1.569 C 8.418 1.539 6.747 1.071 4.927 2.039 Z" fill="rgb(255, 255, 255)" height="15.91228382167905px" id="zfo3WjwfH" transform="translate(125.823 13.928)" width="8.506000000000014px"/><path d="M 5.603 21.382 L 3.726 21.382 L 3.726 7.392 L 0 7.392 L 0 6.043 L 3.726 6.043 L 3.726 0 L 5.603 0 L 5.603 6.043 L 9.298 6.043 L 9.298 7.392 L 5.603 7.392 Z" fill="rgb(255, 255, 255)" height="21.382179999999998px" id="Qgg8g1qom" transform="translate(135.62 8.138)" width="9.298000000000002px"/><path d="M 14.814 15.955 L 12.907 15.955 L 12.907 5.923 C 12.907 3.959 10.385 1.376 7.422 1.376 C 4.634 1.376 1.937 3.929 1.937 5.893 L 1.937 15.955 L 0 15.955 L 0 0.585 L 1.937 0.585 L 1.937 3.05 C 2.025 2.903 3.844 0 8.243 0 C 11.996 0 14.814 3.255 14.814 6.336 L 14.814 15.957 Z" fill="rgb(255, 255, 255)" height="15.957199999999998px" id="BdlnNQExg" transform="translate(146.297 13.888)" width="14.813999999999993px"/><path d="M 1.704 9.091 C 1.997 11.936 4.519 14.929 8.245 14.929 C 11.736 14.929 13.525 12.494 14.198 10.97 L 15.987 10.97 C 14.814 14.108 12.028 16.425 8.242 16.425 C 3.726 16.425 0 12.787 0 8.243 C 0 3.698 3.726 0 8.242 0 C 10.502 0 12.847 1.026 14.431 2.845 C 15.809 4.372 16.6 6.511 16.367 9.093 L 1.701 9.093 Z M 14.814 7.712 C 14.608 4.749 12.026 1.582 8.242 1.582 C 4.459 1.582 1.849 4.662 1.671 7.712 Z" fill="rgb(255, 255, 255)" height="16.4251px" id="miuCWcRlt" transform="translate(162.78 13.976)" width="16.40743060664854px"/><path d="M 4.93 2.039 C 2.555 3.271 1.937 5.47 1.937 6.146 L 1.937 15.912 L 0 15.912 L 0 0.543 L 1.937 0.543 L 1.937 3.446 C 1.994 3.358 2.935 1.539 5.045 0.543 C 7.157 -0.425 8.448 0.19 8.505 0.22 L 8.505 1.569 C 8.418 1.539 6.746 1.071 4.927 2.039 Z" fill="rgb(255, 255, 255)" height="15.91228382167905px" id="aUCIawkuZ" transform="translate(180.964 13.928)" width="8.504999999999995px"/><path d="M 6.161 1.349 C 3.521 1.349 2.025 2.875 2.23 4.869 C 2.435 6.776 5.751 7.129 7.275 7.597 C 9.239 8.213 12.144 8.801 12.144 11.498 C 12.174 14.313 9.857 16.455 6.161 16.455 C 1.937 16.455 0 13.17 0 11 L 1.907 11 C 1.907 13.082 3.404 15.136 6.161 15.136 C 8.743 15.136 10.443 13.64 10.327 11.528 C 10.18 9.504 7.63 9.181 6.369 8.74 C 4.139 8.007 0.473 7.567 0.356 4.809 C 0.238 2.022 2.878 0 6.164 0 C 10.387 0 12.001 3.373 12.001 5.25 L 10.095 5.25 C 10.095 3.313 8.598 1.349 6.164 1.349 Z" fill="rgb(255, 255, 255)" height="16.4551px" id="rKmBDBvEO" transform="translate(188.856 13.946)" width="12.144287854396623px"/><path d="M 0 13.565 L 0 20.556 L 23.392 6.996 L 23.389 0 Z" fill="rgb(255, 255, 255)" height="20.55642px" id="sueM4yXL_" transform="translate(0 3.798)" width="23.3915px"/><path d="M 6.123 3.481 L 6.123 15.89 L 0 19.45 L 0 0 Z" fill="rgb(255, 255, 255)" height="19.45045px" id="KaHsCjO8D" transform="translate(24.227 3.313)" width="6.123100000000001px"/><path d="M 0 2.58 L 4.452 5.027 L 4.452 0 Z" fill="rgb(255, 255, 255)" height="5.027100000000001px" id="QaN_1leFS" transform="translate(0.863 22.25)" width="4.451598px"/><path d="M 0 2.537 L 4.381 4.94 L 4.381 0 Z" fill="rgb(255, 255, 255)" height="4.939599999999999px" id="O8MjoRp3s" transform="translate(25.969 28.188)" width="4.381499999999999px"/><path d="M 0 0 L 0 12.812 L 5.788 9.459 L 5.788 3.303 Z" fill="rgb(255, 255, 255)" height="12.8118px" id="uvKJMKQmN" transform="translate(6.166 0)" width="5.78782px"/><path d="M 0.01 0 L 0 5.2 L 4.622 2.53 Z" fill="rgb(255, 255, 255)" height="5.199800000000003px" id="qR_t9VF6i" transform="translate(12.807 32.367)" width="4.621799999999999px"/><path d="M 5.788 0 L 0 3.358 L 0 16.115 L 5.788 19.456 Z" fill="rgb(255, 255, 255)" height="19.4555px" id="n1CDQdI8Y" transform="translate(6.166 18.399)" width="5.78782px"/><path d="M 0 10.162 L 6.223 13.605 L 17.591 7.037 L 17.591 0 Z" fill="rgb(255, 255, 255)" height="13.6051px" id="zpzeKYNgo" transform="translate(18.877 16.65)" width="17.5912px"/><path d="M 0 0 L 0.01 6.941 L 17.544 16.6 L 23.699 13.029 Z" fill="rgb(255, 255, 255)" height="16.600299999999997px" id="Za4WI7_WJ" transform="translate(12.807 24.46)" width="23.6993px"/><path d="M 0.629 0 L 2.514 4.549 L 4.398 0 L 5.031 0 L 5.031 5.191 L 4.594 5.191 L 4.594 0.579 L 2.691 5.191 L 2.346 5.191 L 0.443 0.585 L 0.443 5.191 L 0 5.191 L 0 0 L 0.632 0 Z" fill="rgb(255, 255, 255)" height="5.1907px" id="CKKZc3ZzS" transform="translate(43 35.201)" width="5.0305000000000035px"/><path d="M 3.061 4.438 C 2.672 4.993 1.976 5.251 1.486 5.251 C 0.658 5.251 0 4.752 0 3.806 C 0 2.953 0.942 2.512 1.353 2.418 C 1.157 2.154 0.62 1.756 0.591 1.187 C 0.566 0.482 1.182 0 1.79 0 C 2.498 0 3.042 0.435 3.042 1.244 C 3.042 1.836 2.409 2.361 1.979 2.569 L 3.064 3.849 C 3.225 3.615 3.374 2.987 3.374 2.709 L 3.797 2.709 C 3.75 3.164 3.576 3.756 3.307 4.147 L 4.129 5.124 L 3.639 5.124 L 3.067 4.441 Z M 1.603 2.692 C 1.065 2.806 0.433 3.184 0.433 3.809 C 0.433 4.508 0.892 4.92 1.502 4.92 C 2.112 4.92 2.545 4.542 2.827 4.157 Z M 1.831 0.308 C 1.347 0.308 1.009 0.686 1.009 1.127 C 1.009 1.525 1.486 2.08 1.777 2.301 C 2.112 2.151 2.631 1.739 2.631 1.204 C 2.631 0.699 2.393 0.308 1.831 0.308 Z" fill="rgb(255, 255, 255)" height="5.2509000000000015px" id="Yv9BGi2jp" transform="translate(49.564 35)" width="4.129300000000001px"/><path d="M 2.722 0 L 4.904 5.191 L 4.48 5.191 L 3.854 3.722 L 1.062 3.722 L 0.436 5.191 L 0 5.191 L 2.201 0 L 2.725 0 Z M 1.202 3.398 L 3.712 3.398 L 2.454 0.451 Z" fill="rgb(255, 255, 255)" height="5.1907px" id="sp8wYAcXb" transform="translate(54.5 35.201)" width="4.903999999999996px"/><path d="M 2.722 0 L 4.904 5.191 L 4.48 5.191 L 3.854 3.722 L 1.062 3.722 L 0.436 5.191 L 0 5.191 L 2.201 0 L 2.725 0 Z M 1.202 3.398 L 3.712 3.398 L 2.454 0.451 Z" fill="rgb(255, 255, 255)" height="5.1907px" id="P4lt6e7Rs" transform="translate(62.904 35.201)" width="4.903999999999996px"/><path d="M 3.525 4.465 C 3.149 4.943 2.672 5.318 1.824 5.318 C 0.977 5.318 0 4.549 0 3.331 C 0 2.114 0.955 1.331 1.824 1.331 C 2.694 1.331 3.095 1.659 3.525 2.207 L 3.525 0 L 3.962 0 L 3.962 5.191 L 3.525 5.191 Z M 2.011 4.993 C 2.865 4.993 3.573 4.261 3.573 3.334 C 3.573 2.408 2.887 1.682 2.017 1.682 C 1.148 1.682 0.449 2.415 0.449 3.334 C 0.449 4.254 1.135 4.993 2.011 4.993 Z" fill="rgb(255, 255, 255)" height="5.317799999999998px" id="lGGhIxpVD" transform="translate(68.238 35.214)" width="3.961800000000011px"/><path d="M 0.487 0 L 1.764 3.211 L 3.042 0 L 3.519 0 L 1.992 3.722 L 1.534 3.722 L 0 0 Z" fill="rgb(255, 255, 255)" height="3.7224000000000004px" id="Obt61Nowr" transform="translate(72.952 36.752)" width="3.519199999999998px"/><path d="M 0.436 0.328 L 0 0.328 L 0 0 L 0.436 0 Z M 0.436 5.191 L 0 5.191 L 0 1.331 L 0.436 1.331 Z" fill="rgb(255, 255, 255)" height="5.19069998703003px" id="vw59luFvh" transform="translate(77.135 35.201)" width="1px"/><path d="M 1.413 0.328 C 0.806 0.328 0.465 0.699 0.512 1.181 C 0.56 1.642 1.319 1.729 1.669 1.843 C 2.122 1.993 2.786 2.134 2.786 2.789 C 2.792 3.472 2.261 3.993 1.413 3.993 C 0.446 3.993 0 3.197 0 2.669 L 0.436 2.669 C 0.436 3.174 0.781 3.672 1.413 3.672 C 2.005 3.672 2.397 3.308 2.368 2.796 C 2.333 2.304 1.748 2.227 1.461 2.12 C 0.949 1.943 0.107 1.836 0.082 1.167 C 0.054 0.492 0.661 0 1.413 0 C 2.384 0 2.754 0.819 2.754 1.274 L 2.318 1.274 C 2.318 0.803 1.976 0.328 1.416 0.328 Z" fill="rgb(255, 255, 255)" height="3.993300000000005px" id="PgD12ztc6" transform="translate(78.264 36.612)" width="2.7856554260391704px"/><path d="M 1.91 0 C 2.972 0 3.819 0.903 3.819 2.024 C 3.819 3.144 2.972 4.054 1.91 4.054 C 0.847 4.054 0 3.151 0 2.024 C 0 0.896 0.854 0 1.91 0 Z M 0.367 2.013 C 0.367 2.91 1.066 3.659 1.91 3.659 C 2.754 3.659 3.45 2.927 3.45 2.03 C 3.45 1.134 2.764 0.391 1.916 0.391 C 1.069 0.391 0.367 1.124 0.367 2.013 Z" fill="rgb(255, 255, 255)" height="4.053600000000003px" id="foA7n1hlj" transform="translate(81.726 36.548)" width="3.819499999999991px"/><path d="M 1.129 0.493 C 0.585 0.791 0.443 1.326 0.443 1.49 L 0.443 3.861 L 0 3.861 L 0 0.132 L 0.443 0.132 L 0.443 0.837 C 0.455 0.817 0.67 0.376 1.157 0.132 C 1.641 -0.102 1.938 0.045 1.951 0.055 L 1.951 0.383 C 1.932 0.376 1.546 0.262 1.129 0.496 Z" fill="rgb(255, 255, 255)" height="3.860826369589411px" id="k5aYRf81s" transform="translate(86.314 36.611)" width="1.950800000000001px"/><path d="M 0.496 0 L 1.774 3.204 L 3.051 0 L 3.529 0 L 1.394 5.191 L 0.977 5.191 L 1.556 3.746 L 0 0 Z" fill="rgb(255, 255, 255)" height="5.1907px" id="Qk0qQI08R" transform="translate(88.669 36.809)" width="3.5285999999999973px"/><path d="M 0.62 1.318 C 0.275 1.318 0 1.027 0 0.662 C 0 0.298 0.275 0 0.62 0 C 0.964 0 1.239 0.298 1.239 0.662 C 1.239 1.027 0.964 1.318 0.62 1.318 Z" fill="rgb(255, 255, 255)" height="1.317699999999995px" id="UvfhJgcqn" transform="translate(97.39 37.819)" width="1.2394000000000034px"/><path d="M 0.436 0 L 0.436 5.191 L 0 5.191 L 0 0 Z" fill="rgb(255, 255, 255)" height="5.1907px" id="Q3xjhsKOv" transform="translate(103.755 35.201)" width="1px"/><path d="M 3.396 3.87 L 2.959 3.87 L 2.959 1.435 C 2.959 0.956 2.381 0.331 1.701 0.331 C 1.062 0.331 0.443 0.95 0.443 1.428 L 0.443 3.87 L 0 3.87 L 0 0.14 L 0.443 0.14 L 0.443 0.739 C 0.462 0.702 0.879 0 1.891 0 C 2.751 0 3.399 0.789 3.399 1.538 L 3.399 3.873 Z" fill="rgb(255, 255, 255)" height="3.8729000000000013px" id="PA0q_YXTt" transform="translate(104.934 36.599)" width="3.399000000000001px"/><path d="M 0.487 0 L 1.765 3.211 L 3.042 0 L 3.519 0 L 1.992 3.722 L 1.534 3.722 L 0 0 Z" fill="rgb(255, 255, 255)" height="3.7224000000000004px" id="WMOxgqPnQ" transform="translate(108.867 36.752)" width="3.5189999999999912px"/><path d="M 0.389 2.204 C 0.455 2.893 1.034 3.622 1.891 3.622 C 2.691 3.622 3.102 3.03 3.257 2.662 L 3.668 2.662 C 3.399 3.425 2.76 3.987 1.891 3.987 C 0.854 3.987 0 3.104 0 2 C 0 0.896 0.854 0 1.891 0 C 2.409 0 2.947 0.251 3.31 0.689 C 3.627 1.06 3.81 1.579 3.756 2.204 Z M 3.399 1.87 C 3.352 1.151 2.76 0.381 1.891 0.381 C 1.021 0.381 0.424 1.127 0.383 1.87 Z" fill="rgb(255, 255, 255)" height="3.986699999999999px" id="OthKZAb9W" transform="translate(112.652 36.622)" width="3.7653860948311824px"/><path d="M 1.413 0.328 C 0.806 0.328 0.465 0.699 0.512 1.181 C 0.559 1.642 1.318 1.729 1.669 1.843 C 2.121 1.993 2.785 2.134 2.785 2.789 C 2.792 3.472 2.26 3.993 1.413 3.993 C 0.446 3.993 0 3.197 0 2.669 L 0.436 2.669 C 0.436 3.174 0.781 3.672 1.413 3.672 C 2.004 3.672 2.396 3.308 2.368 2.796 C 2.333 2.304 1.748 2.227 1.46 2.12 C 0.948 1.943 0.107 1.836 0.082 1.167 C 0.053 0.492 0.661 0 1.413 0 C 2.384 0 2.754 0.819 2.754 1.274 L 2.317 1.274 C 2.317 0.803 1.976 0.328 1.416 0.328 Z" fill="rgb(255, 255, 255)" height="3.993300000000005px" id="ciJYZP1cO" transform="translate(117.12 36.612)" width="2.785068243274509px"/><path d="M 1.284 5.187 L 0.854 5.187 L 0.854 1.793 L 0 1.793 L 0 1.465 L 0.854 1.465 L 0.854 0 L 1.284 0 L 1.284 1.465 L 2.131 1.465 L 2.131 1.793 L 1.284 1.793 Z" fill="rgb(255, 255, 255)" height="5.1873000000000005px" id="hsBMLYZHI" transform="translate(120.326 35.204)" width="2.1310000000000002px"/><path d="M 5.027 3.863 L 4.61 3.863 L 4.61 1.194 C 4.61 0.639 4.132 0.331 3.667 0.331 C 3.203 0.331 2.671 0.686 2.671 1.194 L 2.671 3.863 L 2.302 3.863 L 2.302 1.194 C 2.302 0.632 1.824 0.331 1.432 0.331 C 1.021 0.331 0.423 0.652 0.423 1.227 L 0.423 3.863 L 0 3.863 L 0 0.14 L 0.423 0.14 L 0.423 0.562 C 0.442 0.532 0.793 0 1.527 0 C 2.194 0 2.523 0.619 2.542 0.655 C 2.561 0.619 2.965 0 3.775 0 C 4.502 0 5.027 0.642 5.027 1.331 L 5.027 3.866 Z" fill="rgb(255, 255, 255)" height="3.866199999999999px" id="AfUG7WuDE" transform="translate(123.216 36.605)" width="5.027000000000001px"/><path d="M 0.389 2.204 C 0.455 2.893 1.034 3.622 1.891 3.622 C 2.69 3.622 3.102 3.03 3.256 2.662 L 3.667 2.662 C 3.399 3.425 2.76 3.987 1.891 3.987 C 0.853 3.987 0 3.104 0 2 C 0 0.896 0.853 0 1.891 0 C 2.409 0 2.947 0.251 3.31 0.689 C 3.626 1.06 3.81 1.579 3.756 2.204 Z M 3.399 1.87 C 3.351 1.151 2.76 0.381 1.891 0.381 C 1.021 0.381 0.423 1.127 0.382 1.87 Z" fill="rgb(255, 255, 255)" height="3.986699999999999px" id="nK4KLjWvd" transform="translate(129.078 36.622)" width="3.7653500179975223px"/><path d="M 3.396 3.87 L 2.959 3.87 L 2.959 1.435 C 2.959 0.956 2.381 0.331 1.701 0.331 C 1.062 0.331 0.443 0.95 0.443 1.428 L 0.443 3.87 L 0 3.87 L 0 0.14 L 0.443 0.14 L 0.443 0.739 C 0.462 0.702 0.879 0 1.891 0 C 2.751 0 3.399 0.789 3.399 1.538 L 3.399 3.873 Z" fill="rgb(255, 255, 255)" height="3.8729000000000013px" id="FAdN09aYl" transform="translate(133.691 36.599)" width="3.399000000000001px"/><path d="M 1.283 5.187 L 0.853 5.187 L 0.853 1.793 L 0 1.793 L 0 1.465 L 0.853 1.465 L 0.853 0 L 1.283 0 L 1.283 1.465 L 2.131 1.465 L 2.131 1.793 L 1.283 1.793 Z" fill="rgb(255, 255, 255)" height="5.1873000000000005px" id="rPmG4YvO9" transform="translate(137.672 35.204)" width="2.1310000000000002px"/><path d="M 1.414 0.328 C 0.807 0.328 0.465 0.699 0.513 1.181 C 0.56 1.642 1.319 1.729 1.67 1.843 C 2.122 1.993 2.786 2.134 2.786 2.789 C 2.792 3.472 2.261 3.993 1.414 3.993 C 0.446 3.993 0 3.197 0 2.669 L 0.437 2.669 C 0.437 3.174 0.781 3.672 1.414 3.672 C 2.005 3.672 2.397 3.308 2.369 2.796 C 2.334 2.304 1.749 2.227 1.461 2.12 C 0.949 1.943 0.108 1.836 0.083 1.167 C 0.054 0.492 0.661 0 1.414 0 C 2.384 0 2.754 0.819 2.754 1.274 L 2.318 1.274 C 2.318 0.803 1.977 0.328 1.417 0.328 Z" fill="rgb(255, 255, 255)" height="3.993300000000005px" id="yigdtUGQl" transform="translate(140.188 36.612)" width="2.7860503179292095px"/><path d="M 0.62 1.318 C 0.275 1.318 0 1.027 0 0.662 C 0 0.298 0.275 0 0.62 0 C 0.964 0 1.239 0.298 1.239 0.662 C 1.239 1.027 0.964 1.318 0.62 1.318 Z" fill="rgb(255, 255, 255)" height="1.317699999999995px" id="A9BLuCh5E" transform="translate(148.128 37.819)" width="1.2390000000000043px"/><path d="M 4.563 1.729 C 4.342 1.154 3.621 0.398 2.584 0.398 C 1.468 0.398 0.402 1.368 0.402 2.726 C 0.402 4.084 1.458 5.053 2.584 5.053 C 3.633 5.053 4.332 4.291 4.563 3.722 L 4.987 3.722 C 4.658 4.642 3.735 5.445 2.584 5.445 C 1.164 5.445 0 4.227 0 2.726 C 0 1.224 1.164 0 2.584 0 C 3.735 0 4.652 0.806 4.987 1.729 Z" fill="rgb(255, 255, 255)" height="5.444800000000001px" id="tMM9qOUdD" transform="translate(154.568 35.074)" width="4.986999999999995px"/><path d="M 3.092 0 L 3.092 0.328 L 0.446 0.328 L 0.446 2.194 L 3.029 2.194 L 3.029 2.528 L 0.446 2.528 L 0.446 5.191 L 0 5.191 L 0 0 Z" fill="rgb(255, 255, 255)" height="5.1907px" id="HdCqFaxpa" transform="translate(160.475 35.201)" width="3.092000000000013px"/><path d="M 2.577 0 C 4.003 0 5.154 1.217 5.154 2.726 C 5.154 4.234 4.003 5.445 2.577 5.445 C 1.151 5.445 0 4.227 0 2.726 C 0 1.224 1.157 0 2.577 0 Z M 0.398 2.726 C 0.398 4 1.375 5.033 2.58 5.033 C 3.785 5.033 4.762 4 4.762 2.726 C 4.762 1.452 3.785 0.418 2.58 0.418 C 1.375 0.418 0.398 1.445 0.398 2.726 Z" fill="rgb(255, 255, 255)" height="5.444800000000001px" id="YTLuHpHRE" transform="translate(164.231 35.074)" width="5.153999999999996px"/><path d="M 1.771 0.341 C 1.091 0.341 0.572 0.783 0.572 1.472 C 0.572 2.161 1.758 2.381 2.229 2.602 C 2.808 2.866 3.5 3.037 3.5 3.896 C 3.5 4.709 2.748 5.448 1.777 5.448 C 0.62 5.448 0 4.495 0 3.833 L 0.446 3.833 C 0.446 4.465 0.965 5.12 1.771 5.12 C 2.647 5.12 3.064 4.431 3.064 3.933 C 3.064 3.151 2.403 3.1 1.96 2.9 C 1.281 2.602 0.142 2.371 0.142 1.482 C 0.142 0.686 0.87 0 1.771 0 C 2.726 0 3.38 0.776 3.399 1.438 L 2.963 1.438 C 2.963 1.027 2.485 0.334 1.771 0.334 Z" fill="rgb(255, 255, 255)" height="5.4482px" id="DmJ2Y_yAT" transform="translate(172.85 35.067)" width="3.5px"/><path d="M 0.389 2.204 C 0.455 2.893 1.034 3.622 1.89 3.622 C 2.69 3.622 3.101 3.03 3.256 2.662 L 3.667 2.662 C 3.399 3.425 2.76 3.987 1.89 3.987 C 0.853 3.987 0 3.104 0 2 C 0 0.896 0.853 0 1.89 0 C 2.409 0 2.946 0.251 3.31 0.689 C 3.626 1.06 3.81 1.579 3.756 2.204 Z M 3.399 1.87 C 3.351 1.151 2.76 0.381 1.89 0.381 C 1.021 0.381 0.423 1.127 0.382 1.87 Z" fill="rgb(255, 255, 255)" height="3.986699999999999px" id="yMUVUZg9o" transform="translate(177.119 36.622)" width="3.7653500179975223px"/><path d="M 1.129 0.493 C 0.585 0.791 0.443 1.326 0.443 1.49 L 0.443 3.861 L 0 3.861 L 0 0.132 L 0.443 0.132 L 0.443 0.837 C 0.455 0.817 0.67 0.376 1.157 0.132 C 1.641 -0.102 1.938 0.045 1.951 0.055 L 1.951 0.383 C 1.932 0.376 1.546 0.262 1.129 0.496 Z" fill="rgb(255, 255, 255)" height="3.860826369589411px" id="px2Eh9pZT" transform="translate(181.697 36.611)" width="1.9509999999999934px"/><path d="M 0.487 0 L 1.764 3.211 L 3.042 0 L 3.519 0 L 1.992 3.722 L 1.533 3.722 L 0 0 Z" fill="rgb(255, 255, 255)" height="3.7224000000000004px" id="OCJj23ndt" transform="translate(184.021 36.752)" width="3.5190000000000055px"/><path d="M 0.436 0.328 L 0 0.328 L 0 0 L 0.436 0 Z M 0.436 5.191 L 0 5.191 L 0 1.331 L 0.436 1.331 Z" fill="rgb(255, 255, 255)" height="5.19069998703003px" id="N4v92LZAN" transform="translate(188.204 35.201)" width="1px"/><path d="M 3.256 1.331 C 3.162 1.067 2.713 0.405 1.884 0.405 C 1.116 0.405 0.376 1.06 0.376 2 C 0.376 2.94 1.129 3.602 1.884 3.602 C 2.678 3.602 3.13 3.003 3.256 2.669 L 3.667 2.669 C 3.392 3.438 2.751 3.993 1.884 3.993 C 0.853 3.993 0 3.104 0 2 C 0 0.896 0.853 0 1.884 0 C 2.754 0 3.446 0.625 3.667 1.331 Z" fill="rgb(255, 255, 255)" height="3.993300000000005px" id="x54xXVLtV" transform="translate(189.352 36.612)" width="3.6670000000000016px"/><path d="M 0.389 2.204 C 0.455 2.893 1.034 3.622 1.891 3.622 C 2.69 3.622 3.101 3.03 3.256 2.662 L 3.667 2.662 C 3.399 3.425 2.76 3.987 1.891 3.987 C 0.853 3.987 0 3.104 0 2 C 0 0.896 0.853 0 1.891 0 C 2.409 0 2.947 0.251 3.31 0.689 C 3.626 1.06 3.81 1.579 3.756 2.204 Z M 3.399 1.87 C 3.351 1.151 2.76 0.381 1.891 0.381 C 1.021 0.381 0.423 1.127 0.382 1.87 Z" fill="rgb(255, 255, 255)" height="3.986699999999999px" id="xkGiviUHf" transform="translate(193.747 36.622)" width="3.765350017997494px"/><path d="M 1.414 0.328 C 0.807 0.328 0.465 0.699 0.513 1.181 C 0.56 1.642 1.319 1.729 1.67 1.843 C 2.122 1.993 2.786 2.134 2.786 2.789 C 2.792 3.472 2.261 3.993 1.414 3.993 C 0.446 3.993 0 3.197 0 2.669 L 0.437 2.669 C 0.437 3.174 0.781 3.672 1.414 3.672 C 2.005 3.672 2.397 3.308 2.369 2.796 C 2.334 2.304 1.749 2.227 1.461 2.12 C 0.949 1.943 0.108 1.836 0.083 1.167 C 0.054 0.492 0.661 0 1.414 0 C 2.384 0 2.754 0.819 2.754 1.274 L 2.318 1.274 C 2.318 0.803 1.977 0.328 1.417 0.328 Z" fill="rgb(255, 255, 255)" height="3.993300000000005px" id="N8bEmWbbj" transform="translate(198.214 36.612)" width="2.7860503179292664px"/></svg>)


Türkiye’s M&A market regained momentum in 2025. Deloitte’s Annual Turkish M&A Review recorded 450 transactions and an estimated USD 16.2 billion in deal value, up 91% year on year. The total includes estimates for transactions with undisclosed values. A stronger market, however, does not guarantee that an individual cross-border sale will close.
For Turkish business owners considering a U.S. buyer, four preparation issues deserve particular attention: valuation, financial evidence, management continuity and the buyer universe.
1. Align valuation methodology before negotiating price
An owner may anchor value on revenue, property, installed capacity or market position. A U.S. buyer will often examine normalized EBITDA and comparable transactions, alongside cash flow, growth prospects and sector-specific measures. Asset-heavy and early-stage businesses may require different approaches.
The key question is which earnings are sustainable. Owner expenses, related-party arrangements and non-recurring income or costs need to be identified and supported. A departing family member’s salary is not automatically an add-back: the cost of replacing their work must also be considered.
Preparing an evidence-based bridge from reported to normalized earnings before buyer discussions gives both sides a clearer starting point. It also helps distinguish enterprise value from the equity proceeds remaining after debt, cash and working-capital adjustments.
2. Reconcile statutory accounts and management reporting
Differences between statutory accounts and management reports are not necessarily misconduct; timing, accounting policies and reporting scope can explain them. Unexplained differences, however, make diligence harder and can expose tax or accounting risks.
An institutional buyer needs earnings it can substantiate. Unresolved risks may lead to price adjustments, specific indemnities, escrow arrangements or a decision to withdraw. None of these outcomes is automatic.
Reconcile the accounts, document adjustments and resolve identified compliance issues with qualified professionals. A sell-side financial review can help surface questions early. Reliable reporting supports confidence in the business; it does not guarantee a higher valuation.
3. Reduce dependence on the founder
A buyer will ask how the business performs after the founder steps back. Customer relationships, supplier negotiations and pricing decisions that depend entirely on one person create continuity risk.
A second tier of management, documented processes and durable customer contracts can make the business more transferable. Depending on the circumstances, the transaction may include a transition period, retention arrangements or an earn-out linked to future performance. These are negotiated tools, not inevitable conditions of a sale.
4. Build the buyer universe around strategic fit
Large U.S. industry leaders are only part of the potential buyer universe. Mid-market businesses and private-equity-backed platforms may also find Turkish manufacturing capabilities attractive.
Assess the commercial rationale for each candidate: production capabilities, supply-chain diversification, access to customers, technology, cost competitiveness and proximity to Europe. Tailored materials should explain the opportunity in those terms, supported by evidence rather than a generic translated company presentation.
Follow the price from enterprise value to cash received
In a simplified example, assume an agreed enterprise value of USD 100 million. Deduct USD 20 million of debt, add USD 5 million of cash and deduct a USD 5 million working-capital adjustment. The resulting illustrative equity consideration is USD 80 million. The definition of debt, cash and working capital must be agreed: the same balance cannot be deducted twice under different labels.
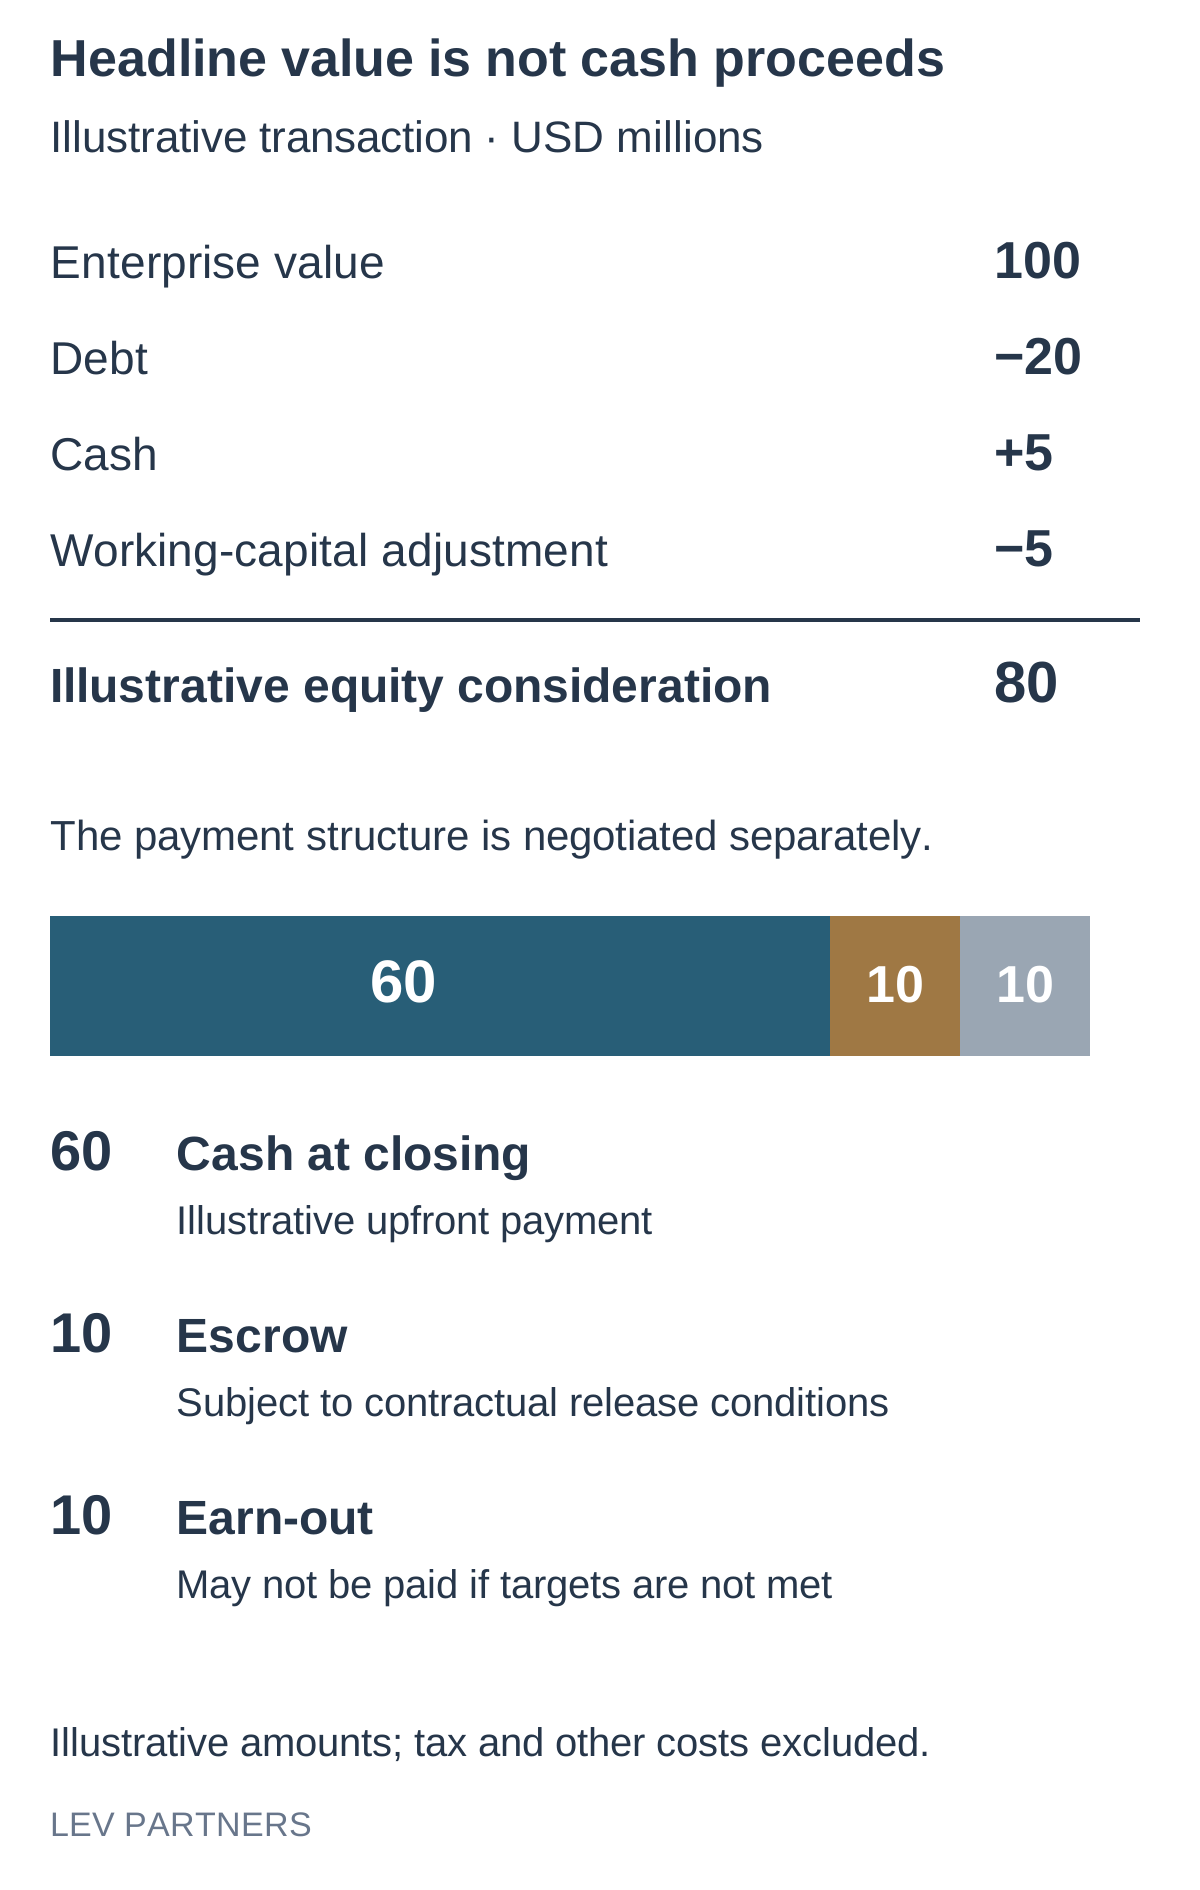
Illustrative transaction only. Tax, transaction expenses and other adjustments are excluded.
The payment terms are a separate negotiation. An USD 80 million headline could hypothetically consist of USD 60 million paid at closing, USD 10 million held in escrow and USD 10 million contingent on future performance. Escrow release depends on the agreed contract; an earn-out may never be paid if its conditions are not met. These components should not be presented as equivalent to immediate, unrestricted cash.
Agree definitions before the last round of negotiations
Working-capital targets should reflect the business's normal needs and seasonality. A target based on an unusual month may shift value unexpectedly. Review receivable quality, inventory provisions, supplier balances and the treatment of advances with the transaction team. Decide how closing accounts will be prepared, which accounting policies apply and how disputes will be resolved.
The seller should also understand which liabilities the buyer treats as debt-like and why. A detailed bridge supported by source records is more useful than arguing about a single multiple. It makes the economic consequences visible and helps prevent an apparent agreement on value from unraveling over definitions.
Prepare evidence around the buyer's investment case
If the buyer's rationale is access to customers, prepare retention and concentration analysis, contract terms and relationship ownership. If the rationale is manufacturing capacity, explain utilization, maintenance needs, product quality and the investment required to deliver growth. If it is technology, establish ownership of intellectual property and the practical ability to transfer or retain the relevant expertise.
Organize the data room around those questions as well as standard document categories. Assign one accountable person to coordinate responses and maintain consistent versions. Contradictory answers across finance, operations and sales can undermine confidence even when the underlying business is sound.
Manage continuity after signing
Before agreeing an earn-out or transition arrangement, define which decisions the seller can influence after closing. Consider budget authority, staffing, customer allocation, reporting access and how performance is measured. A target linked to outcomes outside the seller's control can create conflict. Legal and tax advisers should translate the commercial agreement into a workable structure, while management tests whether it can actually be operated.
How long can the process take?
A cross-border sale can take many months. An indicative planning range might be nine to eighteen months, but readiness, buyer interest, financing, approvals and diligence can materially shorten or extend it. Preparation, outreach, negotiation and closing should be planned as separate stages, with realistic decision points rather than a promised completion date.
Working with Lev Partners to approach U.S. investors
Lev Partners is a U.S.-based M&A and corporate finance advisor with a presence in Turkey and an international remit. For Turkish businesses considering U.S. strategic buyers or private equity investors, our M&A and investor sourcing service can cover sale readiness, valuation, investor materials, a tailored counterparty shortlist and confidential outreach, followed by offer evaluation, due diligence coordination and commercial negotiations.
The mandate may target a full sale, a minority investment or a strategic partnership. We first assess the company’s financial information, funding needs and shareholders’ objectives; we do not assume every U.S. investor is suitable for every business. Legal and tax work is coordinated with relevant specialists.
Transaction experience and the scope of our role
In 2025, Lev Partners managed end-to-end investment banking mandates representing USD 65 million in aggregate transaction value, including investor sourcing. A separate category of buy-side and sell-side process advisory represented approximately USD 70 million; investor sourcing was not included in those mandates. These are category totals, not amounts raised from U.S. investors or values attributed to an individual transaction.
Review our transaction experience and advisory roles to understand the distinction.
Discuss your investor search with Lev Partners. Share your sector, approximate company scale, investment requirement and preferred transaction structure so we can assess the appropriate scope.
Source
Deloitte — Annual Turkish M&A Review 2025. Market figures provide context and are not a forecast of an individual transaction’s outcome.
Your M&A advisory contact
Erim N. Kargacı — Founding Partner and Head of M&A, Lev Partners. Erim leads Lev’s M&A advisory and supports owners considering investment, acquisitions or a company sale. He is also listed among Endeavor Türkiye’s mentors.
Contact us today to discuss your transaction. Tell us about your business and objectives through our confidential contact form →.