" height="21.382199999999997px" id="kC7fwj2cp" transform="translate(43.2 8.135)" width="13.727599999999995px"/><path d="M 4.136 9.621 C 4.607 11.498 6.131 12.702 8.243 12.702 C 10.062 12.702 11.088 11.908 11.616 11 L 15.957 11 C 14.696 14.286 11.999 16.485 8.243 16.485 C 3.726 16.485 0 12.789 0 8.242 C 0 3.696 3.726 0 8.243 0 C 10.385 0 12.934 0.998 14.636 3.08 C 15.897 4.664 16.66 6.806 16.338 9.621 Z M 11.999 6.366 C 11.353 4.634 9.739 3.786 8.127 3.786 C 6.191 3.786 4.872 4.9 4.226 6.366 Z" fill="rgb(255, 255, 255)" height="16.4851px" id="gR7ROinvv" transform="translate(57.746 13.913)" width="16.41157892546896px"/><path d="M 4.752 0 L 7.685 9.944 L 10.617 0 L 15.369 0 L 9.914 15.399 L 5.455 15.399 L 0 0 Z" fill="rgb(255, 255, 255)" height="15.3991px" id="gNXCG2VXg" transform="translate(74.406 14.471)" width="15.369199999999992px"/><path d="M 15.372 6.631 C 15.372 10.502 12.056 13.202 8.801 13.202 L 1.937 13.202 L 1.937 21.385 L 0 21.385 L 0 0 L 8.801 0 C 12.056 0 15.372 2.67 15.372 6.629 Z M 1.939 11.821 L 8.951 11.821 C 11.443 11.821 13.437 9.561 13.437 6.629 C 13.437 3.696 11.531 1.379 8.951 1.379 L 1.939 1.379 Z" fill="rgb(255, 255, 255)" height="21.38469px" id="hre4mzAEc" transform="translate(91.857 8.135)" width="15.371899999999997px"/><path d="M 15.372 12.907 C 13.73 14.901 11.646 16.455 7.95 16.455 C 4.254 16.455 0 13.257 0 8.243 C 0 3.228 4.164 0 7.95 0 C 11.736 0 13.493 1.349 15.372 3.608 L 15.372 0.588 L 17.279 0.588 L 17.279 15.93 L 15.372 15.93 Z M 8.773 15.076 C 12.499 15.076 15.577 12.056 15.577 8.273 C 15.577 4.489 12.584 1.469 8.801 1.469 C 5.017 1.469 1.967 4.462 1.967 8.245 C 1.967 12.029 4.96 15.079 8.771 15.079 Z" fill="rgb(255, 255, 255)" height="16.455199999999998px" id="qtTPusYyi" transform="translate(106.698 13.943)" width="17.27900000000001px"/><path d="M 4.93 2.039 C 2.555 3.271 1.937 5.47 1.937 6.146 L 1.937 15.912 L 0 15.912 L 0 0.543 L 1.937 0.543 L 1.937 3.446 C 1.995 3.358 2.936 1.539 5.045 0.543 C 7.157 -0.425 8.448 0.19 8.506 0.22 L 8.506 1.569 C 8.418 1.539 6.747 1.071 4.927 2.039 Z" fill="rgb(255, 255, 255)" height="15.91228382167905px" id="zfo3WjwfH" transform="translate(125.823 13.928)" width="8.506000000000014px"/><path d="M 5.603 21.382 L 3.726 21.382 L 3.726 7.392 L 0 7.392 L 0 6.043 L 3.726 6.043 L 3.726 0 L 5.603 0 L 5.603 6.043 L 9.298 6.043 L 9.298 7.392 L 5.603 7.392 Z" fill="rgb(255, 255, 255)" height="21.382179999999998px" id="Qgg8g1qom" transform="translate(135.62 8.138)" width="9.298000000000002px"/><path d="M 14.814 15.955 L 12.907 15.955 L 12.907 5.923 C 12.907 3.959 10.385 1.376 7.422 1.376 C 4.634 1.376 1.937 3.929 1.937 5.893 L 1.937 15.955 L 0 15.955 L 0 0.585 L 1.937 0.585 L 1.937 3.05 C 2.025 2.903 3.844 0 8.243 0 C 11.996 0 14.814 3.255 14.814 6.336 L 14.814 15.957 Z" fill="rgb(255, 255, 255)" height="15.957199999999998px" id="BdlnNQExg" transform="translate(146.297 13.888)" width="14.813999999999993px"/><path d="M 1.704 9.091 C 1.997 11.936 4.519 14.929 8.245 14.929 C 11.736 14.929 13.525 12.494 14.198 10.97 L 15.987 10.97 C 14.814 14.108 12.028 16.425 8.242 16.425 C 3.726 16.425 0 12.787 0 8.243 C 0 3.698 3.726 0 8.242 0 C 10.502 0 12.847 1.026 14.431 2.845 C 15.809 4.372 16.6 6.511 16.367 9.093 L 1.701 9.093 Z M 14.814 7.712 C 14.608 4.749 12.026 1.582 8.242 1.582 C 4.459 1.582 1.849 4.662 1.671 7.712 Z" fill="rgb(255, 255, 255)" height="16.4251px" id="miuCWcRlt" transform="translate(162.78 13.976)" width="16.40743060664854px"/><path d="M 4.93 2.039 C 2.555 3.271 1.937 5.47 1.937 6.146 L 1.937 15.912 L 0 15.912 L 0 0.543 L 1.937 0.543 L 1.937 3.446 C 1.994 3.358 2.935 1.539 5.045 0.543 C 7.157 -0.425 8.448 0.19 8.505 0.22 L 8.505 1.569 C 8.418 1.539 6.746 1.071 4.927 2.039 Z" fill="rgb(255, 255, 255)" height="15.91228382167905px" id="aUCIawkuZ" transform="translate(180.964 13.928)" width="8.504999999999995px"/><path d="M 6.161 1.349 C 3.521 1.349 2.025 2.875 2.23 4.869 C 2.435 6.776 5.751 7.129 7.275 7.597 C 9.239 8.213 12.144 8.801 12.144 11.498 C 12.174 14.313 9.857 16.455 6.161 16.455 C 1.937 16.455 0 13.17 0 11 L 1.907 11 C 1.907 13.082 3.404 15.136 6.161 15.136 C 8.743 15.136 10.443 13.64 10.327 11.528 C 10.18 9.504 7.63 9.181 6.369 8.74 C 4.139 8.007 0.473 7.567 0.356 4.809 C 0.238 2.022 2.878 0 6.164 0 C 10.387 0 12.001 3.373 12.001 5.25 L 10.095 5.25 C 10.095 3.313 8.598 1.349 6.164 1.349 Z" fill="rgb(255, 255, 255)" height="16.4551px" id="rKmBDBvEO" transform="translate(188.856 13.946)" width="12.144287854396623px"/><path d="M 0 13.565 L 0 20.556 L 23.392 6.996 L 23.389 0 Z" fill="rgb(255, 255, 255)" height="20.55642px" id="sueM4yXL_" transform="translate(0 3.798)" width="23.3915px"/><path d="M 6.123 3.481 L 6.123 15.89 L 0 19.45 L 0 0 Z" fill="rgb(255, 255, 255)" height="19.45045px" id="KaHsCjO8D" transform="translate(24.227 3.313)" width="6.123100000000001px"/><path d="M 0 2.58 L 4.452 5.027 L 4.452 0 Z" fill="rgb(255, 255, 255)" height="5.027100000000001px" id="QaN_1leFS" transform="translate(0.863 22.25)" width="4.451598px"/><path d="M 0 2.537 L 4.381 4.94 L 4.381 0 Z" fill="rgb(255, 255, 255)" height="4.939599999999999px" id="O8MjoRp3s" transform="translate(25.969 28.188)" width="4.381499999999999px"/><path d="M 0 0 L 0 12.812 L 5.788 9.459 L 5.788 3.303 Z" fill="rgb(255, 255, 255)" height="12.8118px" id="uvKJMKQmN" transform="translate(6.166 0)" width="5.78782px"/><path d="M 0.01 0 L 0 5.2 L 4.622 2.53 Z" fill="rgb(255, 255, 255)" height="5.199800000000003px" id="qR_t9VF6i" transform="translate(12.807 32.367)" width="4.621799999999999px"/><path d="M 5.788 0 L 0 3.358 L 0 16.115 L 5.788 19.456 Z" fill="rgb(255, 255, 255)" height="19.4555px" id="n1CDQdI8Y" transform="translate(6.166 18.399)" width="5.78782px"/><path d="M 0 10.162 L 6.223 13.605 L 17.591 7.037 L 17.591 0 Z" fill="rgb(255, 255, 255)" height="13.6051px" id="zpzeKYNgo" transform="translate(18.877 16.65)" width="17.5912px"/><path d="M 0 0 L 0.01 6.941 L 17.544 16.6 L 23.699 13.029 Z" fill="rgb(255, 255, 255)" height="16.600299999999997px" id="Za4WI7_WJ" transform="translate(12.807 24.46)" width="23.6993px"/><path d="M 0.629 0 L 2.514 4.549 L 4.398 0 L 5.031 0 L 5.031 5.191 L 4.594 5.191 L 4.594 0.579 L 2.691 5.191 L 2.346 5.191 L 0.443 0.585 L 0.443 5.191 L 0 5.191 L 0 0 L 0.632 0 Z" fill="rgb(255, 255, 255)" height="5.1907px" id="CKKZc3ZzS" transform="translate(43 35.201)" width="5.0305000000000035px"/><path d="M 3.061 4.438 C 2.672 4.993 1.976 5.251 1.486 5.251 C 0.658 5.251 0 4.752 0 3.806 C 0 2.953 0.942 2.512 1.353 2.418 C 1.157 2.154 0.62 1.756 0.591 1.187 C 0.566 0.482 1.182 0 1.79 0 C 2.498 0 3.042 0.435 3.042 1.244 C 3.042 1.836 2.409 2.361 1.979 2.569 L 3.064 3.849 C 3.225 3.615 3.374 2.987 3.374 2.709 L 3.797 2.709 C 3.75 3.164 3.576 3.756 3.307 4.147 L 4.129 5.124 L 3.639 5.124 L 3.067 4.441 Z M 1.603 2.692 C 1.065 2.806 0.433 3.184 0.433 3.809 C 0.433 4.508 0.892 4.92 1.502 4.92 C 2.112 4.92 2.545 4.542 2.827 4.157 Z M 1.831 0.308 C 1.347 0.308 1.009 0.686 1.009 1.127 C 1.009 1.525 1.486 2.08 1.777 2.301 C 2.112 2.151 2.631 1.739 2.631 1.204 C 2.631 0.699 2.393 0.308 1.831 0.308 Z" fill="rgb(255, 255, 255)" height="5.2509000000000015px" id="Yv9BGi2jp" transform="translate(49.564 35)" width="4.129300000000001px"/><path d="M 2.722 0 L 4.904 5.191 L 4.48 5.191 L 3.854 3.722 L 1.062 3.722 L 0.436 5.191 L 0 5.191 L 2.201 0 L 2.725 0 Z M 1.202 3.398 L 3.712 3.398 L 2.454 0.451 Z" fill="rgb(255, 255, 255)" height="5.1907px" id="sp8wYAcXb" transform="translate(54.5 35.201)" width="4.903999999999996px"/><path d="M 2.722 0 L 4.904 5.191 L 4.48 5.191 L 3.854 3.722 L 1.062 3.722 L 0.436 5.191 L 0 5.191 L 2.201 0 L 2.725 0 Z M 1.202 3.398 L 3.712 3.398 L 2.454 0.451 Z" fill="rgb(255, 255, 255)" height="5.1907px" id="P4lt6e7Rs" transform="translate(62.904 35.201)" width="4.903999999999996px"/><path d="M 3.525 4.465 C 3.149 4.943 2.672 5.318 1.824 5.318 C 0.977 5.318 0 4.549 0 3.331 C 0 2.114 0.955 1.331 1.824 1.331 C 2.694 1.331 3.095 1.659 3.525 2.207 L 3.525 0 L 3.962 0 L 3.962 5.191 L 3.525 5.191 Z M 2.011 4.993 C 2.865 4.993 3.573 4.261 3.573 3.334 C 3.573 2.408 2.887 1.682 2.017 1.682 C 1.148 1.682 0.449 2.415 0.449 3.334 C 0.449 4.254 1.135 4.993 2.011 4.993 Z" fill="rgb(255, 255, 255)" height="5.317799999999998px" id="lGGhIxpVD" transform="translate(68.238 35.214)" width="3.961800000000011px"/><path d="M 0.487 0 L 1.764 3.211 L 3.042 0 L 3.519 0 L 1.992 3.722 L 1.534 3.722 L 0 0 Z" fill="rgb(255, 255, 255)" height="3.7224000000000004px" id="Obt61Nowr" transform="translate(72.952 36.752)" width="3.519199999999998px"/><path d="M 0.436 0.328 L 0 0.328 L 0 0 L 0.436 0 Z M 0.436 5.191 L 0 5.191 L 0 1.331 L 0.436 1.331 Z" fill="rgb(255, 255, 255)" height="5.19069998703003px" id="vw59luFvh" transform="translate(77.135 35.201)" width="1px"/><path d="M 1.413 0.328 C 0.806 0.328 0.465 0.699 0.512 1.181 C 0.56 1.642 1.319 1.729 1.669 1.843 C 2.122 1.993 2.786 2.134 2.786 2.789 C 2.792 3.472 2.261 3.993 1.413 3.993 C 0.446 3.993 0 3.197 0 2.669 L 0.436 2.669 C 0.436 3.174 0.781 3.672 1.413 3.672 C 2.005 3.672 2.397 3.308 2.368 2.796 C 2.333 2.304 1.748 2.227 1.461 2.12 C 0.949 1.943 0.107 1.836 0.082 1.167 C 0.054 0.492 0.661 0 1.413 0 C 2.384 0 2.754 0.819 2.754 1.274 L 2.318 1.274 C 2.318 0.803 1.976 0.328 1.416 0.328 Z" fill="rgb(255, 255, 255)" height="3.993300000000005px" id="PgD12ztc6" transform="translate(78.264 36.612)" width="2.7856554260391704px"/><path d="M 1.91 0 C 2.972 0 3.819 0.903 3.819 2.024 C 3.819 3.144 2.972 4.054 1.91 4.054 C 0.847 4.054 0 3.151 0 2.024 C 0 0.896 0.854 0 1.91 0 Z M 0.367 2.013 C 0.367 2.91 1.066 3.659 1.91 3.659 C 2.754 3.659 3.45 2.927 3.45 2.03 C 3.45 1.134 2.764 0.391 1.916 0.391 C 1.069 0.391 0.367 1.124 0.367 2.013 Z" fill="rgb(255, 255, 255)" height="4.053600000000003px" id="foA7n1hlj" transform="translate(81.726 36.548)" width="3.819499999999991px"/><path d="M 1.129 0.493 C 0.585 0.791 0.443 1.326 0.443 1.49 L 0.443 3.861 L 0 3.861 L 0 0.132 L 0.443 0.132 L 0.443 0.837 C 0.455 0.817 0.67 0.376 1.157 0.132 C 1.641 -0.102 1.938 0.045 1.951 0.055 L 1.951 0.383 C 1.932 0.376 1.546 0.262 1.129 0.496 Z" fill="rgb(255, 255, 255)" height="3.860826369589411px" id="k5aYRf81s" transform="translate(86.314 36.611)" width="1.950800000000001px"/><path d="M 0.496 0 L 1.774 3.204 L 3.051 0 L 3.529 0 L 1.394 5.191 L 0.977 5.191 L 1.556 3.746 L 0 0 Z" fill="rgb(255, 255, 255)" height="5.1907px" id="Qk0qQI08R" transform="translate(88.669 36.809)" width="3.5285999999999973px"/><path d="M 0.62 1.318 C 0.275 1.318 0 1.027 0 0.662 C 0 0.298 0.275 0 0.62 0 C 0.964 0 1.239 0.298 1.239 0.662 C 1.239 1.027 0.964 1.318 0.62 1.318 Z" fill="rgb(255, 255, 255)" height="1.317699999999995px" id="UvfhJgcqn" transform="translate(97.39 37.819)" width="1.2394000000000034px"/><path d="M 0.436 0 L 0.436 5.191 L 0 5.191 L 0 0 Z" fill="rgb(255, 255, 255)" height="5.1907px" id="Q3xjhsKOv" transform="translate(103.755 35.201)" width="1px"/><path d="M 3.396 3.87 L 2.959 3.87 L 2.959 1.435 C 2.959 0.956 2.381 0.331 1.701 0.331 C 1.062 0.331 0.443 0.95 0.443 1.428 L 0.443 3.87 L 0 3.87 L 0 0.14 L 0.443 0.14 L 0.443 0.739 C 0.462 0.702 0.879 0 1.891 0 C 2.751 0 3.399 0.789 3.399 1.538 L 3.399 3.873 Z" fill="rgb(255, 255, 255)" height="3.8729000000000013px" id="PA0q_YXTt" transform="translate(104.934 36.599)" width="3.399000000000001px"/><path d="M 0.487 0 L 1.765 3.211 L 3.042 0 L 3.519 0 L 1.992 3.722 L 1.534 3.722 L 0 0 Z" fill="rgb(255, 255, 255)" height="3.7224000000000004px" id="WMOxgqPnQ" transform="translate(108.867 36.752)" width="3.5189999999999912px"/><path d="M 0.389 2.204 C 0.455 2.893 1.034 3.622 1.891 3.622 C 2.691 3.622 3.102 3.03 3.257 2.662 L 3.668 2.662 C 3.399 3.425 2.76 3.987 1.891 3.987 C 0.854 3.987 0 3.104 0 2 C 0 0.896 0.854 0 1.891 0 C 2.409 0 2.947 0.251 3.31 0.689 C 3.627 1.06 3.81 1.579 3.756 2.204 Z M 3.399 1.87 C 3.352 1.151 2.76 0.381 1.891 0.381 C 1.021 0.381 0.424 1.127 0.383 1.87 Z" fill="rgb(255, 255, 255)" height="3.986699999999999px" id="OthKZAb9W" transform="translate(112.652 36.622)" width="3.7653860948311824px"/><path d="M 1.413 0.328 C 0.806 0.328 0.465 0.699 0.512 1.181 C 0.559 1.642 1.318 1.729 1.669 1.843 C 2.121 1.993 2.785 2.134 2.785 2.789 C 2.792 3.472 2.26 3.993 1.413 3.993 C 0.446 3.993 0 3.197 0 2.669 L 0.436 2.669 C 0.436 3.174 0.781 3.672 1.413 3.672 C 2.004 3.672 2.396 3.308 2.368 2.796 C 2.333 2.304 1.748 2.227 1.46 2.12 C 0.948 1.943 0.107 1.836 0.082 1.167 C 0.053 0.492 0.661 0 1.413 0 C 2.384 0 2.754 0.819 2.754 1.274 L 2.317 1.274 C 2.317 0.803 1.976 0.328 1.416 0.328 Z" fill="rgb(255, 255, 255)" height="3.993300000000005px" id="ciJYZP1cO" transform="translate(117.12 36.612)" width="2.785068243274509px"/><path d="M 1.284 5.187 L 0.854 5.187 L 0.854 1.793 L 0 1.793 L 0 1.465 L 0.854 1.465 L 0.854 0 L 1.284 0 L 1.284 1.465 L 2.131 1.465 L 2.131 1.793 L 1.284 1.793 Z" fill="rgb(255, 255, 255)" height="5.1873000000000005px" id="hsBMLYZHI" transform="translate(120.326 35.204)" width="2.1310000000000002px"/><path d="M 5.027 3.863 L 4.61 3.863 L 4.61 1.194 C 4.61 0.639 4.132 0.331 3.667 0.331 C 3.203 0.331 2.671 0.686 2.671 1.194 L 2.671 3.863 L 2.302 3.863 L 2.302 1.194 C 2.302 0.632 1.824 0.331 1.432 0.331 C 1.021 0.331 0.423 0.652 0.423 1.227 L 0.423 3.863 L 0 3.863 L 0 0.14 L 0.423 0.14 L 0.423 0.562 C 0.442 0.532 0.793 0 1.527 0 C 2.194 0 2.523 0.619 2.542 0.655 C 2.561 0.619 2.965 0 3.775 0 C 4.502 0 5.027 0.642 5.027 1.331 L 5.027 3.866 Z" fill="rgb(255, 255, 255)" height="3.866199999999999px" id="AfUG7WuDE" transform="translate(123.216 36.605)" width="5.027000000000001px"/><path d="M 0.389 2.204 C 0.455 2.893 1.034 3.622 1.891 3.622 C 2.69 3.622 3.102 3.03 3.256 2.662 L 3.667 2.662 C 3.399 3.425 2.76 3.987 1.891 3.987 C 0.853 3.987 0 3.104 0 2 C 0 0.896 0.853 0 1.891 0 C 2.409 0 2.947 0.251 3.31 0.689 C 3.626 1.06 3.81 1.579 3.756 2.204 Z M 3.399 1.87 C 3.351 1.151 2.76 0.381 1.891 0.381 C 1.021 0.381 0.423 1.127 0.382 1.87 Z" fill="rgb(255, 255, 255)" height="3.986699999999999px" id="nK4KLjWvd" transform="translate(129.078 36.622)" width="3.7653500179975223px"/><path d="M 3.396 3.87 L 2.959 3.87 L 2.959 1.435 C 2.959 0.956 2.381 0.331 1.701 0.331 C 1.062 0.331 0.443 0.95 0.443 1.428 L 0.443 3.87 L 0 3.87 L 0 0.14 L 0.443 0.14 L 0.443 0.739 C 0.462 0.702 0.879 0 1.891 0 C 2.751 0 3.399 0.789 3.399 1.538 L 3.399 3.873 Z" fill="rgb(255, 255, 255)" height="3.8729000000000013px" id="FAdN09aYl" transform="translate(133.691 36.599)" width="3.399000000000001px"/><path d="M 1.283 5.187 L 0.853 5.187 L 0.853 1.793 L 0 1.793 L 0 1.465 L 0.853 1.465 L 0.853 0 L 1.283 0 L 1.283 1.465 L 2.131 1.465 L 2.131 1.793 L 1.283 1.793 Z" fill="rgb(255, 255, 255)" height="5.1873000000000005px" id="rPmG4YvO9" transform="translate(137.672 35.204)" width="2.1310000000000002px"/><path d="M 1.414 0.328 C 0.807 0.328 0.465 0.699 0.513 1.181 C 0.56 1.642 1.319 1.729 1.67 1.843 C 2.122 1.993 2.786 2.134 2.786 2.789 C 2.792 3.472 2.261 3.993 1.414 3.993 C 0.446 3.993 0 3.197 0 2.669 L 0.437 2.669 C 0.437 3.174 0.781 3.672 1.414 3.672 C 2.005 3.672 2.397 3.308 2.369 2.796 C 2.334 2.304 1.749 2.227 1.461 2.12 C 0.949 1.943 0.108 1.836 0.083 1.167 C 0.054 0.492 0.661 0 1.414 0 C 2.384 0 2.754 0.819 2.754 1.274 L 2.318 1.274 C 2.318 0.803 1.977 0.328 1.417 0.328 Z" fill="rgb(255, 255, 255)" height="3.993300000000005px" id="yigdtUGQl" transform="translate(140.188 36.612)" width="2.7860503179292095px"/><path d="M 0.62 1.318 C 0.275 1.318 0 1.027 0 0.662 C 0 0.298 0.275 0 0.62 0 C 0.964 0 1.239 0.298 1.239 0.662 C 1.239 1.027 0.964 1.318 0.62 1.318 Z" fill="rgb(255, 255, 255)" height="1.317699999999995px" id="A9BLuCh5E" transform="translate(148.128 37.819)" width="1.2390000000000043px"/><path d="M 4.563 1.729 C 4.342 1.154 3.621 0.398 2.584 0.398 C 1.468 0.398 0.402 1.368 0.402 2.726 C 0.402 4.084 1.458 5.053 2.584 5.053 C 3.633 5.053 4.332 4.291 4.563 3.722 L 4.987 3.722 C 4.658 4.642 3.735 5.445 2.584 5.445 C 1.164 5.445 0 4.227 0 2.726 C 0 1.224 1.164 0 2.584 0 C 3.735 0 4.652 0.806 4.987 1.729 Z" fill="rgb(255, 255, 255)" height="5.444800000000001px" id="tMM9qOUdD" transform="translate(154.568 35.074)" width="4.986999999999995px"/><path d="M 3.092 0 L 3.092 0.328 L 0.446 0.328 L 0.446 2.194 L 3.029 2.194 L 3.029 2.528 L 0.446 2.528 L 0.446 5.191 L 0 5.191 L 0 0 Z" fill="rgb(255, 255, 255)" height="5.1907px" id="HdCqFaxpa" transform="translate(160.475 35.201)" width="3.092000000000013px"/><path d="M 2.577 0 C 4.003 0 5.154 1.217 5.154 2.726 C 5.154 4.234 4.003 5.445 2.577 5.445 C 1.151 5.445 0 4.227 0 2.726 C 0 1.224 1.157 0 2.577 0 Z M 0.398 2.726 C 0.398 4 1.375 5.033 2.58 5.033 C 3.785 5.033 4.762 4 4.762 2.726 C 4.762 1.452 3.785 0.418 2.58 0.418 C 1.375 0.418 0.398 1.445 0.398 2.726 Z" fill="rgb(255, 255, 255)" height="5.444800000000001px" id="YTLuHpHRE" transform="translate(164.231 35.074)" width="5.153999999999996px"/><path d="M 1.771 0.341 C 1.091 0.341 0.572 0.783 0.572 1.472 C 0.572 2.161 1.758 2.381 2.229 2.602 C 2.808 2.866 3.5 3.037 3.5 3.896 C 3.5 4.709 2.748 5.448 1.777 5.448 C 0.62 5.448 0 4.495 0 3.833 L 0.446 3.833 C 0.446 4.465 0.965 5.12 1.771 5.12 C 2.647 5.12 3.064 4.431 3.064 3.933 C 3.064 3.151 2.403 3.1 1.96 2.9 C 1.281 2.602 0.142 2.371 0.142 1.482 C 0.142 0.686 0.87 0 1.771 0 C 2.726 0 3.38 0.776 3.399 1.438 L 2.963 1.438 C 2.963 1.027 2.485 0.334 1.771 0.334 Z" fill="rgb(255, 255, 255)" height="5.4482px" id="DmJ2Y_yAT" transform="translate(172.85 35.067)" width="3.5px"/><path d="M 0.389 2.204 C 0.455 2.893 1.034 3.622 1.89 3.622 C 2.69 3.622 3.101 3.03 3.256 2.662 L 3.667 2.662 C 3.399 3.425 2.76 3.987 1.89 3.987 C 0.853 3.987 0 3.104 0 2 C 0 0.896 0.853 0 1.89 0 C 2.409 0 2.946 0.251 3.31 0.689 C 3.626 1.06 3.81 1.579 3.756 2.204 Z M 3.399 1.87 C 3.351 1.151 2.76 0.381 1.89 0.381 C 1.021 0.381 0.423 1.127 0.382 1.87 Z" fill="rgb(255, 255, 255)" height="3.986699999999999px" id="yMUVUZg9o" transform="translate(177.119 36.622)" width="3.7653500179975223px"/><path d="M 1.129 0.493 C 0.585 0.791 0.443 1.326 0.443 1.49 L 0.443 3.861 L 0 3.861 L 0 0.132 L 0.443 0.132 L 0.443 0.837 C 0.455 0.817 0.67 0.376 1.157 0.132 C 1.641 -0.102 1.938 0.045 1.951 0.055 L 1.951 0.383 C 1.932 0.376 1.546 0.262 1.129 0.496 Z" fill="rgb(255, 255, 255)" height="3.860826369589411px" id="px2Eh9pZT" transform="translate(181.697 36.611)" width="1.9509999999999934px"/><path d="M 0.487 0 L 1.764 3.211 L 3.042 0 L 3.519 0 L 1.992 3.722 L 1.533 3.722 L 0 0 Z" fill="rgb(255, 255, 255)" height="3.7224000000000004px" id="OCJj23ndt" transform="translate(184.021 36.752)" width="3.5190000000000055px"/><path d="M 0.436 0.328 L 0 0.328 L 0 0 L 0.436 0 Z M 0.436 5.191 L 0 5.191 L 0 1.331 L 0.436 1.331 Z" fill="rgb(255, 255, 255)" height="5.19069998703003px" id="N4v92LZAN" transform="translate(188.204 35.201)" width="1px"/><path d="M 3.256 1.331 C 3.162 1.067 2.713 0.405 1.884 0.405 C 1.116 0.405 0.376 1.06 0.376 2 C 0.376 2.94 1.129 3.602 1.884 3.602 C 2.678 3.602 3.13 3.003 3.256 2.669 L 3.667 2.669 C 3.392 3.438 2.751 3.993 1.884 3.993 C 0.853 3.993 0 3.104 0 2 C 0 0.896 0.853 0 1.884 0 C 2.754 0 3.446 0.625 3.667 1.331 Z" fill="rgb(255, 255, 255)" height="3.993300000000005px" id="x54xXVLtV" transform="translate(189.352 36.612)" width="3.6670000000000016px"/><path d="M 0.389 2.204 C 0.455 2.893 1.034 3.622 1.891 3.622 C 2.69 3.622 3.101 3.03 3.256 2.662 L 3.667 2.662 C 3.399 3.425 2.76 3.987 1.891 3.987 C 0.853 3.987 0 3.104 0 2 C 0 0.896 0.853 0 1.891 0 C 2.409 0 2.947 0.251 3.31 0.689 C 3.626 1.06 3.81 1.579 3.756 2.204 Z M 3.399 1.87 C 3.351 1.151 2.76 0.381 1.891 0.381 C 1.021 0.381 0.423 1.127 0.382 1.87 Z" fill="rgb(255, 255, 255)" height="3.986699999999999px" id="xkGiviUHf" transform="translate(193.747 36.622)" width="3.765350017997494px"/><path d="M 1.414 0.328 C 0.807 0.328 0.465 0.699 0.513 1.181 C 0.56 1.642 1.319 1.729 1.67 1.843 C 2.122 1.993 2.786 2.134 2.786 2.789 C 2.792 3.472 2.261 3.993 1.414 3.993 C 0.446 3.993 0 3.197 0 2.669 L 0.437 2.669 C 0.437 3.174 0.781 3.672 1.414 3.672 C 2.005 3.672 2.397 3.308 2.369 2.796 C 2.334 2.304 1.749 2.227 1.461 2.12 C 0.949 1.943 0.108 1.836 0.083 1.167 C 0.054 0.492 0.661 0 1.414 0 C 2.384 0 2.754 0.819 2.754 1.274 L 2.318 1.274 C 2.318 0.803 1.977 0.328 1.417 0.328 Z" fill="rgb(255, 255, 255)" height="3.993300000000005px" id="N8bEmWbbj" transform="translate(198.214 36.612)" width="2.7860503179292664px"/></svg>)


The investment decision
Evaluate a SPAC by the cash the business can use, the ownership shareholders retain and the operating plan the transaction can fund.
For a Turkish company with international customers, a defensible competitive position and a credible expansion plan, access to U.S. public markets can become a strategic financing question. A SPAC may be one route worth evaluating. Its relevance depends on the business being ready for public ownership and on the transaction delivering sufficient capital on acceptable terms.
The starting point should be the company's growth plan: a new production facility, overseas acquisitions, distribution infrastructure or investment in technology. The financing structure should support that plan. Choosing a SPAC first and searching for a business rationale afterwards reverses the decision.
How the SPAC route works
A special purpose acquisition company raises capital through an IPO and seeks an operating business with which to combine. That subsequent transaction is commonly called a de-SPAC. The operating company can become part of a publicly traded group through the combination, subject to the transaction structure, approvals and applicable listing requirements. Nasdaq describes SPACs as a distinct listing route; admission is not automatic simply because the acquisition vehicle is already listed. See Nasdaq's SPAC overview.
Why it may make sense for a Turkish business
One potential benefit is alignment between international operations and the company's financing audience. A manufacturer selling specialized components to global customers may have a business case that is easier to assess alongside international peers. An investor presentation can connect order visibility, customer retention, margins and capacity utilization to a specific use of capital. That can broaden the discussion beyond local borrowing capacity, although it does not guarantee investor demand or a higher valuation.
A second consideration is the duration of the capital requirement. Building a factory or acquiring an overseas distributor may take longer to generate cash than short-term facilities comfortably allow. Equity financing can form part of a more suitable capital structure, provided shareholders understand its cost through dilution and governance obligations. The right comparison is the overall economic outcome, rather than the headline amount announced at signing.
A third possibility is supporting a longer international growth strategy. Public shares may become part of the consideration for future acquisitions, subject to liquidity, contractual restrictions and the willingness of counterparties to accept them. Public reporting can also provide a structured framework for communicating with customers, lenders and potential partners. Neither benefit follows automatically from a listing: management must build credibility through consistent execution.
Which companies should consider an assessment?
Export-oriented industrial businesses, technology-enabled manufacturers, healthcare companies and established consumer businesses can all merit an initial review. Sector alone is insufficient. A useful candidate has understandable unit economics, evidence supporting its forecasts, a clear ownership structure and managers willing to operate under public-market scrutiny.
For example, an automotive supplier with diversified customers and a funded product-development plan presents a different proposition from a business dependent on one contract and immediate refinancing. The assessment should focus on operating resilience, customer quality and the use of proceeds, wherever the business is located.
Preparation also means examining revenue recognition, related-party transactions, working capital, debt covenants and management reporting. A company facing an urgent liquidity shortage may need restructuring or private financing before a public-market transaction is realistic. A SPAC should not be treated as emergency cash or a substitute for a viable business model.
The economics that deserve the most attention
SPAC shareholders can exercise redemption rights, so the trust balance is not the same as assured cash at closing. Additional financing may be necessary. Sponsor interests, warrants, fees and financing terms can materially affect existing shareholders. The SEC's rules require enhanced disclosures concerning sponsor compensation, conflicts, dilution and projections. See the SEC compliance guide.
Our practical decision framework starts with three questions: what net cash remains available to the business, what ownership do current shareholders retain on a fully diluted basis, and can the resulting company fund its operating plan? Management should compare several redemption and financing scenarios, including a downside case. The cost of audit, governance, investor relations and ongoing reporting belongs in that plan as well.
A hypothetical manufacturer planning an overseas acquisition should therefore test whether proceeds after transaction costs can cover both the purchase and the working capital needed afterwards. A compelling announced valuation cannot compensate for insufficient operating cash. Commercial alternatives should remain open until the proposed structure passes that test.
A worked example: follow the cash to the operating business
Assume a SPAC initially holds USD 100 million in trust. If redemptions remove USD 60 million, USD 40 million remains. Add a hypothetical USD 30 million private investment in public equity, or PIPE, and subtract USD 10 million of transaction costs: the result is USD 60 million of net transaction cash. These amounts are illustrative; they are not market benchmarks or a financing commitment.
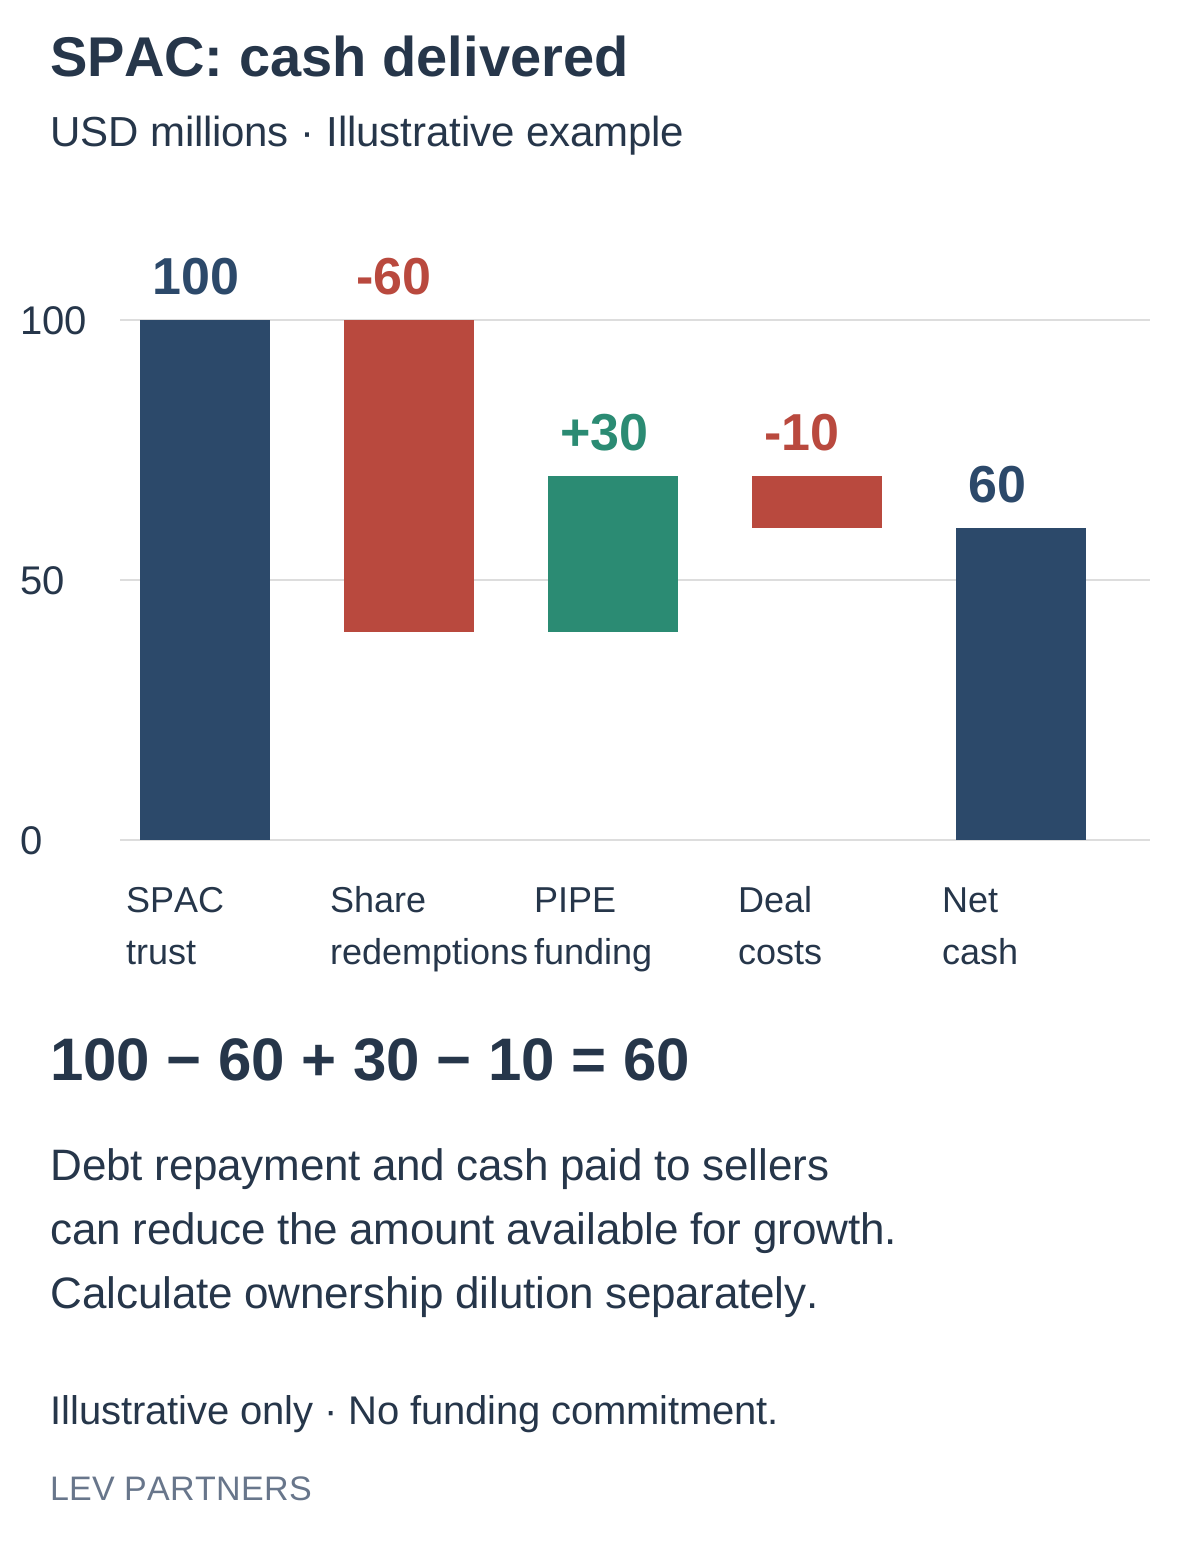
Illustrative cash bridge in USD millions. Company valuation and shareholder dilution are separate calculations.
That USD 60 million is not necessarily all available for growth. If the transaction also requires USD 15 million of debt repayment and USD 5 million of cash consideration to selling shareholders, the operating business would retain USD 40 million before any other uses. Management should reconcile every source and use of funds, then compare the residual cash with the acquisition, capital expenditure and working-capital plan.
Three sensitivities to test before signing
Higher redemptions: At USD 80 million of redemptions, the same example produces USD 40 million of net transaction cash before debt repayment and seller consideration. How would the growth plan change?
Less additional financing: A smaller or conditional PIPE changes available cash. Which commitments are binding, what conditions remain and when must they be satisfied?
More dilution: Sponsor shares, new financing, warrants and other instruments may change existing shareholders' percentage ownership. A cash waterfall cannot answer this question; build a separate fully diluted capitalization table.
A valuation discussion should therefore include both cash delivered and ownership retained. An attractive headline enterprise value may coexist with limited operating proceeds, substantial dilution or restrictive financing terms. Negotiations should focus on the combined outcome.
Keep alternative routes in the comparison
A traditional IPO places the operating business directly into an offering process. A SPAC route centers on negotiating and completing a business combination, with its own financing and redemption risks. A direct listing has a different market-entry mechanism and should not be assumed to deliver new growth capital without a separately evaluated permitted structure. Private equity or a strategic investment may provide capital without taking on public-company obligations at the same point. The best route depends on the funding objective, execution requirements and shareholder priorities.
How Lev Partners supports the process
Lev Partners is U.S.-based, with a presence in Turkey and an international advisory perspective. Our role is to connect a company's commercial objectives with the preparation and coordination required for a credible cross-border transaction. The value of a U.S. network lies in identifying relevant conversations and assembling an appropriate working team, then helping those parties evaluate the same reliable information.
First, we can assess strategic fit and compare the SPAC route with a traditional IPO, private equity investment or a strategic transaction. This includes clarifying the capital requirement, shareholders' objectives and the management resources available. Our IPO advisory services provide a starting point for that readiness discussion.
Second, we can support financial modelling, valuation analysis, investor materials and data-room preparation. An English presentation needs more than translation: it must explain how the company earns money, what differentiates it and how proposed funding creates measurable operating capacity. We help management connect its narrative to financial evidence and identify questions likely to arise during due diligence.
Third, our U.S. relationships can support identifying appropriate counterparties and professional advisers, subject to their interest, availability and fit. We can coordinate discussions with securities counsel, independent auditors, tax specialists and other transaction participants. Where regulated securities placement or brokerage is required, that work must be undertaken by appropriately authorized professionals. Introductions are a starting point for evaluation, not a commitment of funding.
Finally, we can help management track workstreams, evaluate proposed economics and prepare for life after closing. A clear reporting calendar, ownership of financial controls and realistic management capacity matter just as much as reaching a transaction milestone.
Start with readiness, then choose the route
A SPAC can be a sensible option when a strong operating business, suitable counterparties, workable economics and public-company readiness come together. It should earn its place against other financing routes. For some companies, private investment or a strategic partnership will better meet the same objective.
Contact Lev Partners to discuss whether your company is ready for a SPAC assessment. An initial discussion can focus on recent financial performance, international revenues, ownership and the intended use of funds. From there, we can define the preparation needed and the alternatives worth pursuing.
Your public-markets advisory contacts
Atilla Esen — Board Advisor, Lev Partners. Atilla brings capital-markets management experience, including a former General Manager role at Ahlatcı Yatırım. At Lev, he is a contact for assessing public-market preparation alongside the company’s broader financing priorities.
Erim N. Kargacı — Founding Partner and Head of M&A, Lev Partners. Erim leads Lev’s M&A advisory and helps coordinate the strategic and financial preparation for a potential transaction. He is listed among Endeavor Türkiye’s mentors.
Contact us today to discuss your company’s readiness. Share your business profile and financing objectives through our contact form →.