" height="21.382199999999997px" id="kC7fwj2cp" transform="translate(43.2 8.135)" width="13.727599999999995px"/><path d="M 4.136 9.621 C 4.607 11.498 6.131 12.702 8.243 12.702 C 10.062 12.702 11.088 11.908 11.616 11 L 15.957 11 C 14.696 14.286 11.999 16.485 8.243 16.485 C 3.726 16.485 0 12.789 0 8.242 C 0 3.696 3.726 0 8.243 0 C 10.385 0 12.934 0.998 14.636 3.08 C 15.897 4.664 16.66 6.806 16.338 9.621 Z M 11.999 6.366 C 11.353 4.634 9.739 3.786 8.127 3.786 C 6.191 3.786 4.872 4.9 4.226 6.366 Z" fill="rgb(255, 255, 255)" height="16.4851px" id="gR7ROinvv" transform="translate(57.746 13.913)" width="16.41157892546896px"/><path d="M 4.752 0 L 7.685 9.944 L 10.617 0 L 15.369 0 L 9.914 15.399 L 5.455 15.399 L 0 0 Z" fill="rgb(255, 255, 255)" height="15.3991px" id="gNXCG2VXg" transform="translate(74.406 14.471)" width="15.369199999999992px"/><path d="M 15.372 6.631 C 15.372 10.502 12.056 13.202 8.801 13.202 L 1.937 13.202 L 1.937 21.385 L 0 21.385 L 0 0 L 8.801 0 C 12.056 0 15.372 2.67 15.372 6.629 Z M 1.939 11.821 L 8.951 11.821 C 11.443 11.821 13.437 9.561 13.437 6.629 C 13.437 3.696 11.531 1.379 8.951 1.379 L 1.939 1.379 Z" fill="rgb(255, 255, 255)" height="21.38469px" id="hre4mzAEc" transform="translate(91.857 8.135)" width="15.371899999999997px"/><path d="M 15.372 12.907 C 13.73 14.901 11.646 16.455 7.95 16.455 C 4.254 16.455 0 13.257 0 8.243 C 0 3.228 4.164 0 7.95 0 C 11.736 0 13.493 1.349 15.372 3.608 L 15.372 0.588 L 17.279 0.588 L 17.279 15.93 L 15.372 15.93 Z M 8.773 15.076 C 12.499 15.076 15.577 12.056 15.577 8.273 C 15.577 4.489 12.584 1.469 8.801 1.469 C 5.017 1.469 1.967 4.462 1.967 8.245 C 1.967 12.029 4.96 15.079 8.771 15.079 Z" fill="rgb(255, 255, 255)" height="16.455199999999998px" id="qtTPusYyi" transform="translate(106.698 13.943)" width="17.27900000000001px"/><path d="M 4.93 2.039 C 2.555 3.271 1.937 5.47 1.937 6.146 L 1.937 15.912 L 0 15.912 L 0 0.543 L 1.937 0.543 L 1.937 3.446 C 1.995 3.358 2.936 1.539 5.045 0.543 C 7.157 -0.425 8.448 0.19 8.506 0.22 L 8.506 1.569 C 8.418 1.539 6.747 1.071 4.927 2.039 Z" fill="rgb(255, 255, 255)" height="15.91228382167905px" id="zfo3WjwfH" transform="translate(125.823 13.928)" width="8.506000000000014px"/><path d="M 5.603 21.382 L 3.726 21.382 L 3.726 7.392 L 0 7.392 L 0 6.043 L 3.726 6.043 L 3.726 0 L 5.603 0 L 5.603 6.043 L 9.298 6.043 L 9.298 7.392 L 5.603 7.392 Z" fill="rgb(255, 255, 255)" height="21.382179999999998px" id="Qgg8g1qom" transform="translate(135.62 8.138)" width="9.298000000000002px"/><path d="M 14.814 15.955 L 12.907 15.955 L 12.907 5.923 C 12.907 3.959 10.385 1.376 7.422 1.376 C 4.634 1.376 1.937 3.929 1.937 5.893 L 1.937 15.955 L 0 15.955 L 0 0.585 L 1.937 0.585 L 1.937 3.05 C 2.025 2.903 3.844 0 8.243 0 C 11.996 0 14.814 3.255 14.814 6.336 L 14.814 15.957 Z" fill="rgb(255, 255, 255)" height="15.957199999999998px" id="BdlnNQExg" transform="translate(146.297 13.888)" width="14.813999999999993px"/><path d="M 1.704 9.091 C 1.997 11.936 4.519 14.929 8.245 14.929 C 11.736 14.929 13.525 12.494 14.198 10.97 L 15.987 10.97 C 14.814 14.108 12.028 16.425 8.242 16.425 C 3.726 16.425 0 12.787 0 8.243 C 0 3.698 3.726 0 8.242 0 C 10.502 0 12.847 1.026 14.431 2.845 C 15.809 4.372 16.6 6.511 16.367 9.093 L 1.701 9.093 Z M 14.814 7.712 C 14.608 4.749 12.026 1.582 8.242 1.582 C 4.459 1.582 1.849 4.662 1.671 7.712 Z" fill="rgb(255, 255, 255)" height="16.4251px" id="miuCWcRlt" transform="translate(162.78 13.976)" width="16.40743060664854px"/><path d="M 4.93 2.039 C 2.555 3.271 1.937 5.47 1.937 6.146 L 1.937 15.912 L 0 15.912 L 0 0.543 L 1.937 0.543 L 1.937 3.446 C 1.994 3.358 2.935 1.539 5.045 0.543 C 7.157 -0.425 8.448 0.19 8.505 0.22 L 8.505 1.569 C 8.418 1.539 6.746 1.071 4.927 2.039 Z" fill="rgb(255, 255, 255)" height="15.91228382167905px" id="aUCIawkuZ" transform="translate(180.964 13.928)" width="8.504999999999995px"/><path d="M 6.161 1.349 C 3.521 1.349 2.025 2.875 2.23 4.869 C 2.435 6.776 5.751 7.129 7.275 7.597 C 9.239 8.213 12.144 8.801 12.144 11.498 C 12.174 14.313 9.857 16.455 6.161 16.455 C 1.937 16.455 0 13.17 0 11 L 1.907 11 C 1.907 13.082 3.404 15.136 6.161 15.136 C 8.743 15.136 10.443 13.64 10.327 11.528 C 10.18 9.504 7.63 9.181 6.369 8.74 C 4.139 8.007 0.473 7.567 0.356 4.809 C 0.238 2.022 2.878 0 6.164 0 C 10.387 0 12.001 3.373 12.001 5.25 L 10.095 5.25 C 10.095 3.313 8.598 1.349 6.164 1.349 Z" fill="rgb(255, 255, 255)" height="16.4551px" id="rKmBDBvEO" transform="translate(188.856 13.946)" width="12.144287854396623px"/><path d="M 0 13.565 L 0 20.556 L 23.392 6.996 L 23.389 0 Z" fill="rgb(255, 255, 255)" height="20.55642px" id="sueM4yXL_" transform="translate(0 3.798)" width="23.3915px"/><path d="M 6.123 3.481 L 6.123 15.89 L 0 19.45 L 0 0 Z" fill="rgb(255, 255, 255)" height="19.45045px" id="KaHsCjO8D" transform="translate(24.227 3.313)" width="6.123100000000001px"/><path d="M 0 2.58 L 4.452 5.027 L 4.452 0 Z" fill="rgb(255, 255, 255)" height="5.027100000000001px" id="QaN_1leFS" transform="translate(0.863 22.25)" width="4.451598px"/><path d="M 0 2.537 L 4.381 4.94 L 4.381 0 Z" fill="rgb(255, 255, 255)" height="4.939599999999999px" id="O8MjoRp3s" transform="translate(25.969 28.188)" width="4.381499999999999px"/><path d="M 0 0 L 0 12.812 L 5.788 9.459 L 5.788 3.303 Z" fill="rgb(255, 255, 255)" height="12.8118px" id="uvKJMKQmN" transform="translate(6.166 0)" width="5.78782px"/><path d="M 0.01 0 L 0 5.2 L 4.622 2.53 Z" fill="rgb(255, 255, 255)" height="5.199800000000003px" id="qR_t9VF6i" transform="translate(12.807 32.367)" width="4.621799999999999px"/><path d="M 5.788 0 L 0 3.358 L 0 16.115 L 5.788 19.456 Z" fill="rgb(255, 255, 255)" height="19.4555px" id="n1CDQdI8Y" transform="translate(6.166 18.399)" width="5.78782px"/><path d="M 0 10.162 L 6.223 13.605 L 17.591 7.037 L 17.591 0 Z" fill="rgb(255, 255, 255)" height="13.6051px" id="zpzeKYNgo" transform="translate(18.877 16.65)" width="17.5912px"/><path d="M 0 0 L 0.01 6.941 L 17.544 16.6 L 23.699 13.029 Z" fill="rgb(255, 255, 255)" height="16.600299999999997px" id="Za4WI7_WJ" transform="translate(12.807 24.46)" width="23.6993px"/><path d="M 0.629 0 L 2.514 4.549 L 4.398 0 L 5.031 0 L 5.031 5.191 L 4.594 5.191 L 4.594 0.579 L 2.691 5.191 L 2.346 5.191 L 0.443 0.585 L 0.443 5.191 L 0 5.191 L 0 0 L 0.632 0 Z" fill="rgb(255, 255, 255)" height="5.1907px" id="CKKZc3ZzS" transform="translate(43 35.201)" width="5.0305000000000035px"/><path d="M 3.061 4.438 C 2.672 4.993 1.976 5.251 1.486 5.251 C 0.658 5.251 0 4.752 0 3.806 C 0 2.953 0.942 2.512 1.353 2.418 C 1.157 2.154 0.62 1.756 0.591 1.187 C 0.566 0.482 1.182 0 1.79 0 C 2.498 0 3.042 0.435 3.042 1.244 C 3.042 1.836 2.409 2.361 1.979 2.569 L 3.064 3.849 C 3.225 3.615 3.374 2.987 3.374 2.709 L 3.797 2.709 C 3.75 3.164 3.576 3.756 3.307 4.147 L 4.129 5.124 L 3.639 5.124 L 3.067 4.441 Z M 1.603 2.692 C 1.065 2.806 0.433 3.184 0.433 3.809 C 0.433 4.508 0.892 4.92 1.502 4.92 C 2.112 4.92 2.545 4.542 2.827 4.157 Z M 1.831 0.308 C 1.347 0.308 1.009 0.686 1.009 1.127 C 1.009 1.525 1.486 2.08 1.777 2.301 C 2.112 2.151 2.631 1.739 2.631 1.204 C 2.631 0.699 2.393 0.308 1.831 0.308 Z" fill="rgb(255, 255, 255)" height="5.2509000000000015px" id="Yv9BGi2jp" transform="translate(49.564 35)" width="4.129300000000001px"/><path d="M 2.722 0 L 4.904 5.191 L 4.48 5.191 L 3.854 3.722 L 1.062 3.722 L 0.436 5.191 L 0 5.191 L 2.201 0 L 2.725 0 Z M 1.202 3.398 L 3.712 3.398 L 2.454 0.451 Z" fill="rgb(255, 255, 255)" height="5.1907px" id="sp8wYAcXb" transform="translate(54.5 35.201)" width="4.903999999999996px"/><path d="M 2.722 0 L 4.904 5.191 L 4.48 5.191 L 3.854 3.722 L 1.062 3.722 L 0.436 5.191 L 0 5.191 L 2.201 0 L 2.725 0 Z M 1.202 3.398 L 3.712 3.398 L 2.454 0.451 Z" fill="rgb(255, 255, 255)" height="5.1907px" id="P4lt6e7Rs" transform="translate(62.904 35.201)" width="4.903999999999996px"/><path d="M 3.525 4.465 C 3.149 4.943 2.672 5.318 1.824 5.318 C 0.977 5.318 0 4.549 0 3.331 C 0 2.114 0.955 1.331 1.824 1.331 C 2.694 1.331 3.095 1.659 3.525 2.207 L 3.525 0 L 3.962 0 L 3.962 5.191 L 3.525 5.191 Z M 2.011 4.993 C 2.865 4.993 3.573 4.261 3.573 3.334 C 3.573 2.408 2.887 1.682 2.017 1.682 C 1.148 1.682 0.449 2.415 0.449 3.334 C 0.449 4.254 1.135 4.993 2.011 4.993 Z" fill="rgb(255, 255, 255)" height="5.317799999999998px" id="lGGhIxpVD" transform="translate(68.238 35.214)" width="3.961800000000011px"/><path d="M 0.487 0 L 1.764 3.211 L 3.042 0 L 3.519 0 L 1.992 3.722 L 1.534 3.722 L 0 0 Z" fill="rgb(255, 255, 255)" height="3.7224000000000004px" id="Obt61Nowr" transform="translate(72.952 36.752)" width="3.519199999999998px"/><path d="M 0.436 0.328 L 0 0.328 L 0 0 L 0.436 0 Z M 0.436 5.191 L 0 5.191 L 0 1.331 L 0.436 1.331 Z" fill="rgb(255, 255, 255)" height="5.19069998703003px" id="vw59luFvh" transform="translate(77.135 35.201)" width="1px"/><path d="M 1.413 0.328 C 0.806 0.328 0.465 0.699 0.512 1.181 C 0.56 1.642 1.319 1.729 1.669 1.843 C 2.122 1.993 2.786 2.134 2.786 2.789 C 2.792 3.472 2.261 3.993 1.413 3.993 C 0.446 3.993 0 3.197 0 2.669 L 0.436 2.669 C 0.436 3.174 0.781 3.672 1.413 3.672 C 2.005 3.672 2.397 3.308 2.368 2.796 C 2.333 2.304 1.748 2.227 1.461 2.12 C 0.949 1.943 0.107 1.836 0.082 1.167 C 0.054 0.492 0.661 0 1.413 0 C 2.384 0 2.754 0.819 2.754 1.274 L 2.318 1.274 C 2.318 0.803 1.976 0.328 1.416 0.328 Z" fill="rgb(255, 255, 255)" height="3.993300000000005px" id="PgD12ztc6" transform="translate(78.264 36.612)" width="2.7856554260391704px"/><path d="M 1.91 0 C 2.972 0 3.819 0.903 3.819 2.024 C 3.819 3.144 2.972 4.054 1.91 4.054 C 0.847 4.054 0 3.151 0 2.024 C 0 0.896 0.854 0 1.91 0 Z M 0.367 2.013 C 0.367 2.91 1.066 3.659 1.91 3.659 C 2.754 3.659 3.45 2.927 3.45 2.03 C 3.45 1.134 2.764 0.391 1.916 0.391 C 1.069 0.391 0.367 1.124 0.367 2.013 Z" fill="rgb(255, 255, 255)" height="4.053600000000003px" id="foA7n1hlj" transform="translate(81.726 36.548)" width="3.819499999999991px"/><path d="M 1.129 0.493 C 0.585 0.791 0.443 1.326 0.443 1.49 L 0.443 3.861 L 0 3.861 L 0 0.132 L 0.443 0.132 L 0.443 0.837 C 0.455 0.817 0.67 0.376 1.157 0.132 C 1.641 -0.102 1.938 0.045 1.951 0.055 L 1.951 0.383 C 1.932 0.376 1.546 0.262 1.129 0.496 Z" fill="rgb(255, 255, 255)" height="3.860826369589411px" id="k5aYRf81s" transform="translate(86.314 36.611)" width="1.950800000000001px"/><path d="M 0.496 0 L 1.774 3.204 L 3.051 0 L 3.529 0 L 1.394 5.191 L 0.977 5.191 L 1.556 3.746 L 0 0 Z" fill="rgb(255, 255, 255)" height="5.1907px" id="Qk0qQI08R" transform="translate(88.669 36.809)" width="3.5285999999999973px"/><path d="M 0.62 1.318 C 0.275 1.318 0 1.027 0 0.662 C 0 0.298 0.275 0 0.62 0 C 0.964 0 1.239 0.298 1.239 0.662 C 1.239 1.027 0.964 1.318 0.62 1.318 Z" fill="rgb(255, 255, 255)" height="1.317699999999995px" id="UvfhJgcqn" transform="translate(97.39 37.819)" width="1.2394000000000034px"/><path d="M 0.436 0 L 0.436 5.191 L 0 5.191 L 0 0 Z" fill="rgb(255, 255, 255)" height="5.1907px" id="Q3xjhsKOv" transform="translate(103.755 35.201)" width="1px"/><path d="M 3.396 3.87 L 2.959 3.87 L 2.959 1.435 C 2.959 0.956 2.381 0.331 1.701 0.331 C 1.062 0.331 0.443 0.95 0.443 1.428 L 0.443 3.87 L 0 3.87 L 0 0.14 L 0.443 0.14 L 0.443 0.739 C 0.462 0.702 0.879 0 1.891 0 C 2.751 0 3.399 0.789 3.399 1.538 L 3.399 3.873 Z" fill="rgb(255, 255, 255)" height="3.8729000000000013px" id="PA0q_YXTt" transform="translate(104.934 36.599)" width="3.399000000000001px"/><path d="M 0.487 0 L 1.765 3.211 L 3.042 0 L 3.519 0 L 1.992 3.722 L 1.534 3.722 L 0 0 Z" fill="rgb(255, 255, 255)" height="3.7224000000000004px" id="WMOxgqPnQ" transform="translate(108.867 36.752)" width="3.5189999999999912px"/><path d="M 0.389 2.204 C 0.455 2.893 1.034 3.622 1.891 3.622 C 2.691 3.622 3.102 3.03 3.257 2.662 L 3.668 2.662 C 3.399 3.425 2.76 3.987 1.891 3.987 C 0.854 3.987 0 3.104 0 2 C 0 0.896 0.854 0 1.891 0 C 2.409 0 2.947 0.251 3.31 0.689 C 3.627 1.06 3.81 1.579 3.756 2.204 Z M 3.399 1.87 C 3.352 1.151 2.76 0.381 1.891 0.381 C 1.021 0.381 0.424 1.127 0.383 1.87 Z" fill="rgb(255, 255, 255)" height="3.986699999999999px" id="OthKZAb9W" transform="translate(112.652 36.622)" width="3.7653860948311824px"/><path d="M 1.413 0.328 C 0.806 0.328 0.465 0.699 0.512 1.181 C 0.559 1.642 1.318 1.729 1.669 1.843 C 2.121 1.993 2.785 2.134 2.785 2.789 C 2.792 3.472 2.26 3.993 1.413 3.993 C 0.446 3.993 0 3.197 0 2.669 L 0.436 2.669 C 0.436 3.174 0.781 3.672 1.413 3.672 C 2.004 3.672 2.396 3.308 2.368 2.796 C 2.333 2.304 1.748 2.227 1.46 2.12 C 0.948 1.943 0.107 1.836 0.082 1.167 C 0.053 0.492 0.661 0 1.413 0 C 2.384 0 2.754 0.819 2.754 1.274 L 2.317 1.274 C 2.317 0.803 1.976 0.328 1.416 0.328 Z" fill="rgb(255, 255, 255)" height="3.993300000000005px" id="ciJYZP1cO" transform="translate(117.12 36.612)" width="2.785068243274509px"/><path d="M 1.284 5.187 L 0.854 5.187 L 0.854 1.793 L 0 1.793 L 0 1.465 L 0.854 1.465 L 0.854 0 L 1.284 0 L 1.284 1.465 L 2.131 1.465 L 2.131 1.793 L 1.284 1.793 Z" fill="rgb(255, 255, 255)" height="5.1873000000000005px" id="hsBMLYZHI" transform="translate(120.326 35.204)" width="2.1310000000000002px"/><path d="M 5.027 3.863 L 4.61 3.863 L 4.61 1.194 C 4.61 0.639 4.132 0.331 3.667 0.331 C 3.203 0.331 2.671 0.686 2.671 1.194 L 2.671 3.863 L 2.302 3.863 L 2.302 1.194 C 2.302 0.632 1.824 0.331 1.432 0.331 C 1.021 0.331 0.423 0.652 0.423 1.227 L 0.423 3.863 L 0 3.863 L 0 0.14 L 0.423 0.14 L 0.423 0.562 C 0.442 0.532 0.793 0 1.527 0 C 2.194 0 2.523 0.619 2.542 0.655 C 2.561 0.619 2.965 0 3.775 0 C 4.502 0 5.027 0.642 5.027 1.331 L 5.027 3.866 Z" fill="rgb(255, 255, 255)" height="3.866199999999999px" id="AfUG7WuDE" transform="translate(123.216 36.605)" width="5.027000000000001px"/><path d="M 0.389 2.204 C 0.455 2.893 1.034 3.622 1.891 3.622 C 2.69 3.622 3.102 3.03 3.256 2.662 L 3.667 2.662 C 3.399 3.425 2.76 3.987 1.891 3.987 C 0.853 3.987 0 3.104 0 2 C 0 0.896 0.853 0 1.891 0 C 2.409 0 2.947 0.251 3.31 0.689 C 3.626 1.06 3.81 1.579 3.756 2.204 Z M 3.399 1.87 C 3.351 1.151 2.76 0.381 1.891 0.381 C 1.021 0.381 0.423 1.127 0.382 1.87 Z" fill="rgb(255, 255, 255)" height="3.986699999999999px" id="nK4KLjWvd" transform="translate(129.078 36.622)" width="3.7653500179975223px"/><path d="M 3.396 3.87 L 2.959 3.87 L 2.959 1.435 C 2.959 0.956 2.381 0.331 1.701 0.331 C 1.062 0.331 0.443 0.95 0.443 1.428 L 0.443 3.87 L 0 3.87 L 0 0.14 L 0.443 0.14 L 0.443 0.739 C 0.462 0.702 0.879 0 1.891 0 C 2.751 0 3.399 0.789 3.399 1.538 L 3.399 3.873 Z" fill="rgb(255, 255, 255)" height="3.8729000000000013px" id="FAdN09aYl" transform="translate(133.691 36.599)" width="3.399000000000001px"/><path d="M 1.283 5.187 L 0.853 5.187 L 0.853 1.793 L 0 1.793 L 0 1.465 L 0.853 1.465 L 0.853 0 L 1.283 0 L 1.283 1.465 L 2.131 1.465 L 2.131 1.793 L 1.283 1.793 Z" fill="rgb(255, 255, 255)" height="5.1873000000000005px" id="rPmG4YvO9" transform="translate(137.672 35.204)" width="2.1310000000000002px"/><path d="M 1.414 0.328 C 0.807 0.328 0.465 0.699 0.513 1.181 C 0.56 1.642 1.319 1.729 1.67 1.843 C 2.122 1.993 2.786 2.134 2.786 2.789 C 2.792 3.472 2.261 3.993 1.414 3.993 C 0.446 3.993 0 3.197 0 2.669 L 0.437 2.669 C 0.437 3.174 0.781 3.672 1.414 3.672 C 2.005 3.672 2.397 3.308 2.369 2.796 C 2.334 2.304 1.749 2.227 1.461 2.12 C 0.949 1.943 0.108 1.836 0.083 1.167 C 0.054 0.492 0.661 0 1.414 0 C 2.384 0 2.754 0.819 2.754 1.274 L 2.318 1.274 C 2.318 0.803 1.977 0.328 1.417 0.328 Z" fill="rgb(255, 255, 255)" height="3.993300000000005px" id="yigdtUGQl" transform="translate(140.188 36.612)" width="2.7860503179292095px"/><path d="M 0.62 1.318 C 0.275 1.318 0 1.027 0 0.662 C 0 0.298 0.275 0 0.62 0 C 0.964 0 1.239 0.298 1.239 0.662 C 1.239 1.027 0.964 1.318 0.62 1.318 Z" fill="rgb(255, 255, 255)" height="1.317699999999995px" id="A9BLuCh5E" transform="translate(148.128 37.819)" width="1.2390000000000043px"/><path d="M 4.563 1.729 C 4.342 1.154 3.621 0.398 2.584 0.398 C 1.468 0.398 0.402 1.368 0.402 2.726 C 0.402 4.084 1.458 5.053 2.584 5.053 C 3.633 5.053 4.332 4.291 4.563 3.722 L 4.987 3.722 C 4.658 4.642 3.735 5.445 2.584 5.445 C 1.164 5.445 0 4.227 0 2.726 C 0 1.224 1.164 0 2.584 0 C 3.735 0 4.652 0.806 4.987 1.729 Z" fill="rgb(255, 255, 255)" height="5.444800000000001px" id="tMM9qOUdD" transform="translate(154.568 35.074)" width="4.986999999999995px"/><path d="M 3.092 0 L 3.092 0.328 L 0.446 0.328 L 0.446 2.194 L 3.029 2.194 L 3.029 2.528 L 0.446 2.528 L 0.446 5.191 L 0 5.191 L 0 0 Z" fill="rgb(255, 255, 255)" height="5.1907px" id="HdCqFaxpa" transform="translate(160.475 35.201)" width="3.092000000000013px"/><path d="M 2.577 0 C 4.003 0 5.154 1.217 5.154 2.726 C 5.154 4.234 4.003 5.445 2.577 5.445 C 1.151 5.445 0 4.227 0 2.726 C 0 1.224 1.157 0 2.577 0 Z M 0.398 2.726 C 0.398 4 1.375 5.033 2.58 5.033 C 3.785 5.033 4.762 4 4.762 2.726 C 4.762 1.452 3.785 0.418 2.58 0.418 C 1.375 0.418 0.398 1.445 0.398 2.726 Z" fill="rgb(255, 255, 255)" height="5.444800000000001px" id="YTLuHpHRE" transform="translate(164.231 35.074)" width="5.153999999999996px"/><path d="M 1.771 0.341 C 1.091 0.341 0.572 0.783 0.572 1.472 C 0.572 2.161 1.758 2.381 2.229 2.602 C 2.808 2.866 3.5 3.037 3.5 3.896 C 3.5 4.709 2.748 5.448 1.777 5.448 C 0.62 5.448 0 4.495 0 3.833 L 0.446 3.833 C 0.446 4.465 0.965 5.12 1.771 5.12 C 2.647 5.12 3.064 4.431 3.064 3.933 C 3.064 3.151 2.403 3.1 1.96 2.9 C 1.281 2.602 0.142 2.371 0.142 1.482 C 0.142 0.686 0.87 0 1.771 0 C 2.726 0 3.38 0.776 3.399 1.438 L 2.963 1.438 C 2.963 1.027 2.485 0.334 1.771 0.334 Z" fill="rgb(255, 255, 255)" height="5.4482px" id="DmJ2Y_yAT" transform="translate(172.85 35.067)" width="3.5px"/><path d="M 0.389 2.204 C 0.455 2.893 1.034 3.622 1.89 3.622 C 2.69 3.622 3.101 3.03 3.256 2.662 L 3.667 2.662 C 3.399 3.425 2.76 3.987 1.89 3.987 C 0.853 3.987 0 3.104 0 2 C 0 0.896 0.853 0 1.89 0 C 2.409 0 2.946 0.251 3.31 0.689 C 3.626 1.06 3.81 1.579 3.756 2.204 Z M 3.399 1.87 C 3.351 1.151 2.76 0.381 1.89 0.381 C 1.021 0.381 0.423 1.127 0.382 1.87 Z" fill="rgb(255, 255, 255)" height="3.986699999999999px" id="yMUVUZg9o" transform="translate(177.119 36.622)" width="3.7653500179975223px"/><path d="M 1.129 0.493 C 0.585 0.791 0.443 1.326 0.443 1.49 L 0.443 3.861 L 0 3.861 L 0 0.132 L 0.443 0.132 L 0.443 0.837 C 0.455 0.817 0.67 0.376 1.157 0.132 C 1.641 -0.102 1.938 0.045 1.951 0.055 L 1.951 0.383 C 1.932 0.376 1.546 0.262 1.129 0.496 Z" fill="rgb(255, 255, 255)" height="3.860826369589411px" id="px2Eh9pZT" transform="translate(181.697 36.611)" width="1.9509999999999934px"/><path d="M 0.487 0 L 1.764 3.211 L 3.042 0 L 3.519 0 L 1.992 3.722 L 1.533 3.722 L 0 0 Z" fill="rgb(255, 255, 255)" height="3.7224000000000004px" id="OCJj23ndt" transform="translate(184.021 36.752)" width="3.5190000000000055px"/><path d="M 0.436 0.328 L 0 0.328 L 0 0 L 0.436 0 Z M 0.436 5.191 L 0 5.191 L 0 1.331 L 0.436 1.331 Z" fill="rgb(255, 255, 255)" height="5.19069998703003px" id="N4v92LZAN" transform="translate(188.204 35.201)" width="1px"/><path d="M 3.256 1.331 C 3.162 1.067 2.713 0.405 1.884 0.405 C 1.116 0.405 0.376 1.06 0.376 2 C 0.376 2.94 1.129 3.602 1.884 3.602 C 2.678 3.602 3.13 3.003 3.256 2.669 L 3.667 2.669 C 3.392 3.438 2.751 3.993 1.884 3.993 C 0.853 3.993 0 3.104 0 2 C 0 0.896 0.853 0 1.884 0 C 2.754 0 3.446 0.625 3.667 1.331 Z" fill="rgb(255, 255, 255)" height="3.993300000000005px" id="x54xXVLtV" transform="translate(189.352 36.612)" width="3.6670000000000016px"/><path d="M 0.389 2.204 C 0.455 2.893 1.034 3.622 1.891 3.622 C 2.69 3.622 3.101 3.03 3.256 2.662 L 3.667 2.662 C 3.399 3.425 2.76 3.987 1.891 3.987 C 0.853 3.987 0 3.104 0 2 C 0 0.896 0.853 0 1.891 0 C 2.409 0 2.947 0.251 3.31 0.689 C 3.626 1.06 3.81 1.579 3.756 2.204 Z M 3.399 1.87 C 3.351 1.151 2.76 0.381 1.891 0.381 C 1.021 0.381 0.423 1.127 0.382 1.87 Z" fill="rgb(255, 255, 255)" height="3.986699999999999px" id="xkGiviUHf" transform="translate(193.747 36.622)" width="3.765350017997494px"/><path d="M 1.414 0.328 C 0.807 0.328 0.465 0.699 0.513 1.181 C 0.56 1.642 1.319 1.729 1.67 1.843 C 2.122 1.993 2.786 2.134 2.786 2.789 C 2.792 3.472 2.261 3.993 1.414 3.993 C 0.446 3.993 0 3.197 0 2.669 L 0.437 2.669 C 0.437 3.174 0.781 3.672 1.414 3.672 C 2.005 3.672 2.397 3.308 2.369 2.796 C 2.334 2.304 1.749 2.227 1.461 2.12 C 0.949 1.943 0.108 1.836 0.083 1.167 C 0.054 0.492 0.661 0 1.414 0 C 2.384 0 2.754 0.819 2.754 1.274 L 2.318 1.274 C 2.318 0.803 1.977 0.328 1.417 0.328 Z" fill="rgb(255, 255, 255)" height="3.993300000000005px" id="N8bEmWbbj" transform="translate(198.214 36.612)" width="2.7860503179292664px"/></svg>)


Your U.S. company needs a financial operating system
Opening a U.S. company and obtaining a bank account are only the beginning. Once sales, supplier payments and transfers from shareholders start, management needs a reliable way to record transactions, understand profitability and identify filing responsibilities. A tax return prepared at year-end cannot replace that operating discipline.
For international owners, the challenge is often coordination. The bookkeeper sees transactions, management sees commercial activity, and the tax preparer sees filing requirements. If those views do not connect, missing documents and unanswered questions can accumulate until the filing deadline. A practical accounting and tax process brings them together throughout the year.
1. Start with the entity and the activity
The legal label on a company is not enough to determine its federal tax treatment. The IRS explains that an LLC may be treated as a disregarded entity, partnership or corporation depending on ownership and tax elections. The relevant returns therefore depend on the actual classification and facts, not simply on the letters “LLC”.
Prepare an initial fact sheet with the ownership structure, tax elections, financial year, business model, locations, employees, inventory and related-party arrangements. Share it with the appropriate U.S. tax professional. An online seller using warehouses, a consulting company with remote staff and a manufacturer establishing a sales subsidiary can have different obligations even when incorporated in the same state.
2. Make accounting useful every month
A sound monthly process reconciles bank and card accounts, customer balances, supplier balances and payment-platform settlements. It separates shareholder funding from revenue, documents loans and capital contributions, and keeps personal expenditure outside the company's operating results. Supporting invoices and agreements should be easy to retrieve.
The IRS identifies recordkeeping as a foundation for financial statements and tax returns. Management also needs those records to answer commercial questions: which activities generate margin, how much cash is tied up in receivables, and whether the business can fund its next stage of growth.
Practical example: A payment processor deposits USD 9,700 after deducting USD 300 of fees from USD 10,000 of customer receipts. Recording only the bank deposit can obscure gross activity and fees. The accounting team should reconcile the settlement to the underlying transactions, including refunds and any tax collected. This is an illustrative reconciliation, not a rule that all customer receipts are recognised revenue.
3. Separate the different tax workstreams
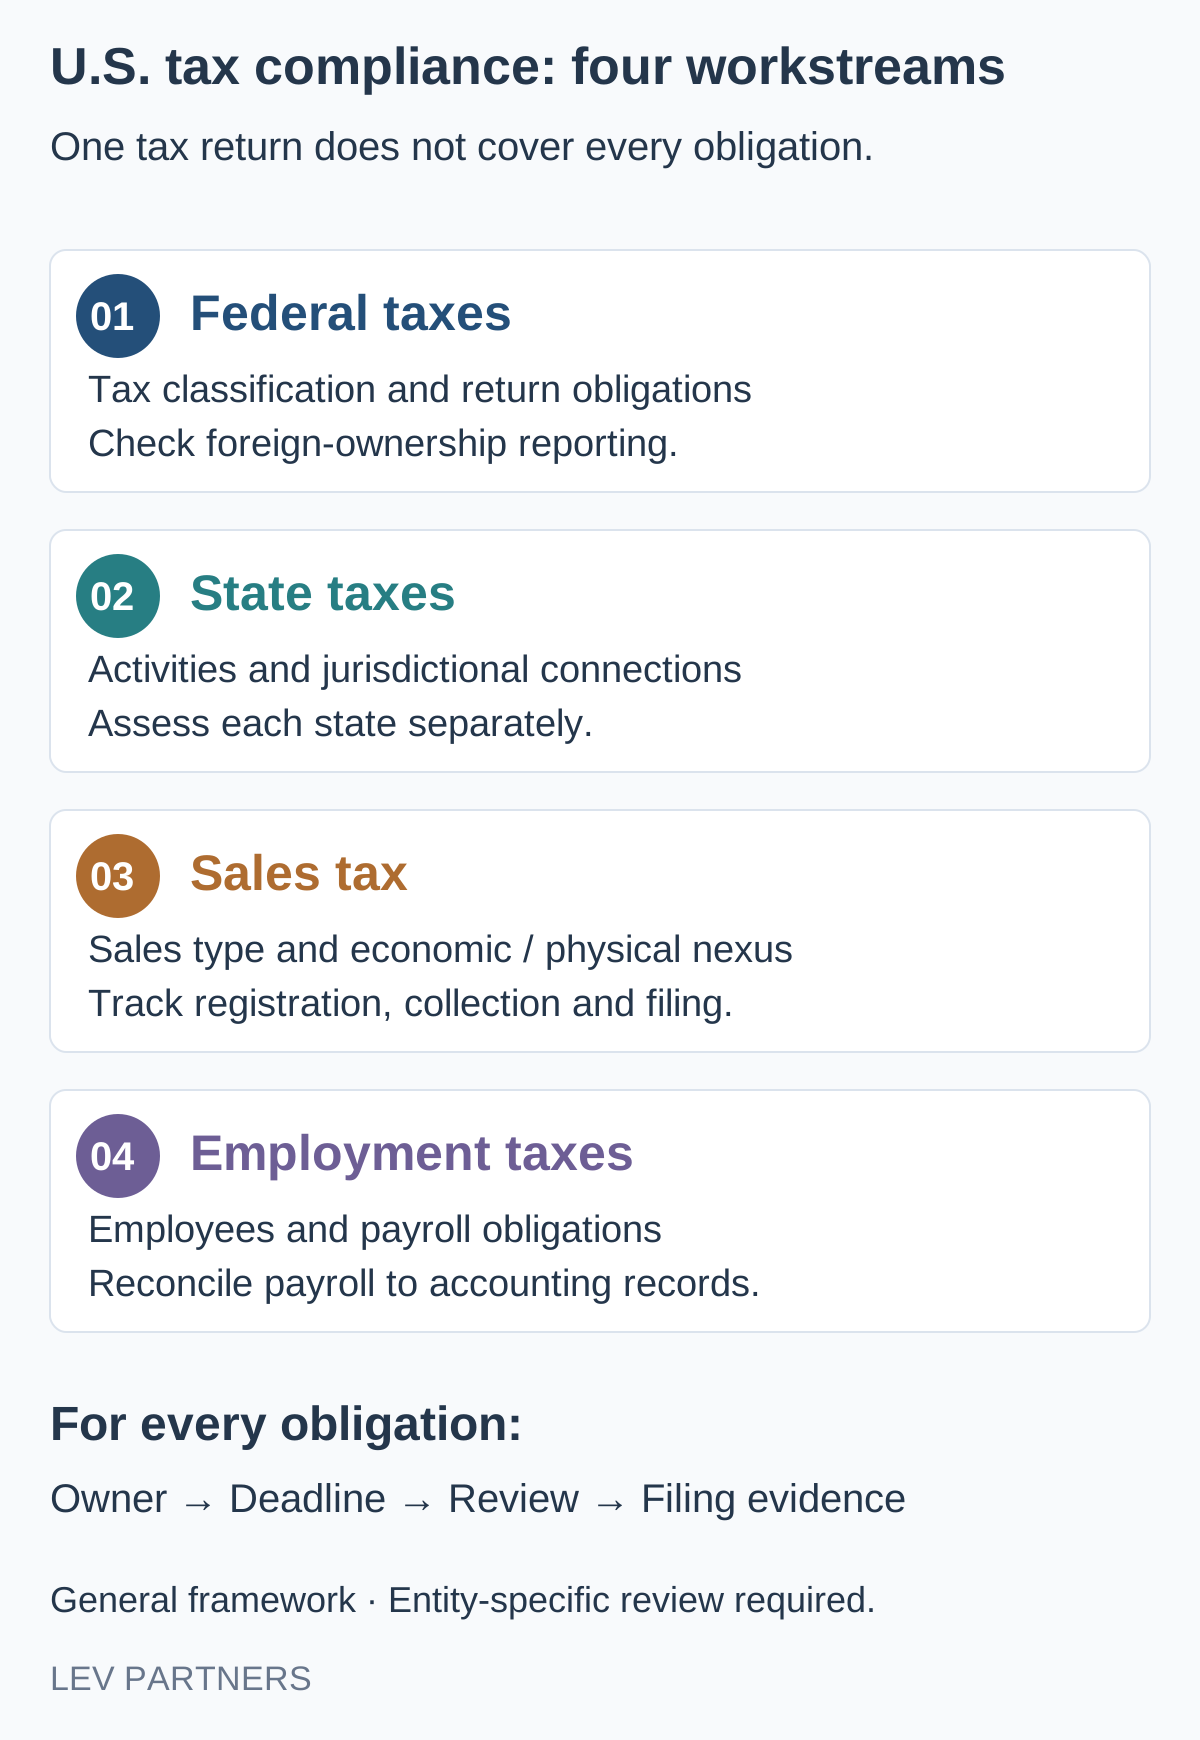
Federal income tax, state obligations, sales tax and employment taxes are different workstreams. Which ones apply depends on the company's structure and activity. Maintain a responsibility register showing the applicable filing, jurisdiction, period, preparer, reviewer, due date and evidence of submission and payment.
Sales tax deserves its own review when selling across states. For example, New York publishes registration rules for certain remote sellers without a physical presence. Its requirements should not be treated as a nationwide threshold. A state-by-state assessment should consider where the company operates and sells, the nature of its products or services, and any relevant marketplace arrangements.
Ask the preparer to distinguish the filing deadline from the payment deadline and to explain any estimated-payment requirements. Do not assume that requesting extra time to file also postpones payment. The applicable calendar should be confirmed for the specific entity and tax year rather than copied from a generic online checklist.
4. Foreign ownership can create additional reporting
Transactions between a U.S. entity and its foreign owner or affiliates require attention. Depending on the entity and the transactions, Form 5472 reporting can apply. Certain foreign-owned U.S. disregarded entities may need a Form 5472 attached to a pro forma Form 1120 even where no income tax is due. The IRS instructions define the scope and exceptions.
Maintain a separate schedule of owner contributions, distributions, loans, repayments and intercompany charges, supported by the relevant documents. Have the tax professional determine the treatment and reporting requirements. “We made no profit” is not a sufficient basis for assuming there is nothing to file.
5. Give each party a clear role
Management approves the commercial facts and provides complete records. The accounting team maintains the ledger and reconciliations. The appropriately qualified tax professional determines the filing position and prepares the agreed returns. An advisory coordinator helps manage information requests, deadlines and communication between the parties.
When selecting a U.S. CPA firm or other tax professional, confirm credentials, relevant international-business experience, scope, fees and who will handle questions after filing. The IRS provides guidance on preparer qualifications. Hiring a preparer does not remove the taxpayer's responsibility for the information reported.
6. Build readiness for financing and growth
Clean financial information supports more than compliance. A lender, investor or potential buyer may ask for consistent monthly accounts, reconciled debt, evidence of tax filings and an explanation of intercompany balances. Resolving discrepancies while the business is operating normally is generally easier than reconstructing several years during a financing process.
The first improvement need not be a new software system. Establish one document repository, an agreed chart of accounts, a monthly reporting deadline and a list of unresolved items with named owners. Review the process when entering another state, adding employees, changing ownership or launching a new sales channel.
How Lev Partners can support you
Our U.S. accounting and tax coordination service helps international business owners organise financial information, establish reporting routines and coordinate with CPA firms and relevant specialists. We connect this work with CFO support and broader U.S. expansion planning. Tax advice, return preparation and representation are provided by the appropriately qualified professionals under the agreed scope.
Contact Lev Partners to review your company's current accounting setup, reporting gaps and coordination needs. This article provides general information; entity-specific obligations require professional review.
Sources: IRS guidance on LLC classification, recordkeeping, business taxes, Form 5472 and choosing a tax professional; New York remote-seller guidance. Reviewed September 22, 2026.
Your U.S. services contact
Canan Kargacı — Director of U.S. Tax Compliance, Lev Partners. Canan is Lev’s service contact for U.S. accounting and tax-compliance coordination. She helps scope the company’s reporting, accounting and compliance needs and coordinate the relevant workstreams with the team.
Contact us today about your U.S. operations. Tell us about your entity, activities and current accounting or tax priorities through our contact form →.