" height="21.382199999999997px" id="kC7fwj2cp" transform="translate(43.2 8.135)" width="13.727599999999995px"/><path d="M 4.136 9.621 C 4.607 11.498 6.131 12.702 8.243 12.702 C 10.062 12.702 11.088 11.908 11.616 11 L 15.957 11 C 14.696 14.286 11.999 16.485 8.243 16.485 C 3.726 16.485 0 12.789 0 8.242 C 0 3.696 3.726 0 8.243 0 C 10.385 0 12.934 0.998 14.636 3.08 C 15.897 4.664 16.66 6.806 16.338 9.621 Z M 11.999 6.366 C 11.353 4.634 9.739 3.786 8.127 3.786 C 6.191 3.786 4.872 4.9 4.226 6.366 Z" fill="rgb(255, 255, 255)" height="16.4851px" id="gR7ROinvv" transform="translate(57.746 13.913)" width="16.41157892546896px"/><path d="M 4.752 0 L 7.685 9.944 L 10.617 0 L 15.369 0 L 9.914 15.399 L 5.455 15.399 L 0 0 Z" fill="rgb(255, 255, 255)" height="15.3991px" id="gNXCG2VXg" transform="translate(74.406 14.471)" width="15.369199999999992px"/><path d="M 15.372 6.631 C 15.372 10.502 12.056 13.202 8.801 13.202 L 1.937 13.202 L 1.937 21.385 L 0 21.385 L 0 0 L 8.801 0 C 12.056 0 15.372 2.67 15.372 6.629 Z M 1.939 11.821 L 8.951 11.821 C 11.443 11.821 13.437 9.561 13.437 6.629 C 13.437 3.696 11.531 1.379 8.951 1.379 L 1.939 1.379 Z" fill="rgb(255, 255, 255)" height="21.38469px" id="hre4mzAEc" transform="translate(91.857 8.135)" width="15.371899999999997px"/><path d="M 15.372 12.907 C 13.73 14.901 11.646 16.455 7.95 16.455 C 4.254 16.455 0 13.257 0 8.243 C 0 3.228 4.164 0 7.95 0 C 11.736 0 13.493 1.349 15.372 3.608 L 15.372 0.588 L 17.279 0.588 L 17.279 15.93 L 15.372 15.93 Z M 8.773 15.076 C 12.499 15.076 15.577 12.056 15.577 8.273 C 15.577 4.489 12.584 1.469 8.801 1.469 C 5.017 1.469 1.967 4.462 1.967 8.245 C 1.967 12.029 4.96 15.079 8.771 15.079 Z" fill="rgb(255, 255, 255)" height="16.455199999999998px" id="qtTPusYyi" transform="translate(106.698 13.943)" width="17.27900000000001px"/><path d="M 4.93 2.039 C 2.555 3.271 1.937 5.47 1.937 6.146 L 1.937 15.912 L 0 15.912 L 0 0.543 L 1.937 0.543 L 1.937 3.446 C 1.995 3.358 2.936 1.539 5.045 0.543 C 7.157 -0.425 8.448 0.19 8.506 0.22 L 8.506 1.569 C 8.418 1.539 6.747 1.071 4.927 2.039 Z" fill="rgb(255, 255, 255)" height="15.91228382167905px" id="zfo3WjwfH" transform="translate(125.823 13.928)" width="8.506000000000014px"/><path d="M 5.603 21.382 L 3.726 21.382 L 3.726 7.392 L 0 7.392 L 0 6.043 L 3.726 6.043 L 3.726 0 L 5.603 0 L 5.603 6.043 L 9.298 6.043 L 9.298 7.392 L 5.603 7.392 Z" fill="rgb(255, 255, 255)" height="21.382179999999998px" id="Qgg8g1qom" transform="translate(135.62 8.138)" width="9.298000000000002px"/><path d="M 14.814 15.955 L 12.907 15.955 L 12.907 5.923 C 12.907 3.959 10.385 1.376 7.422 1.376 C 4.634 1.376 1.937 3.929 1.937 5.893 L 1.937 15.955 L 0 15.955 L 0 0.585 L 1.937 0.585 L 1.937 3.05 C 2.025 2.903 3.844 0 8.243 0 C 11.996 0 14.814 3.255 14.814 6.336 L 14.814 15.957 Z" fill="rgb(255, 255, 255)" height="15.957199999999998px" id="BdlnNQExg" transform="translate(146.297 13.888)" width="14.813999999999993px"/><path d="M 1.704 9.091 C 1.997 11.936 4.519 14.929 8.245 14.929 C 11.736 14.929 13.525 12.494 14.198 10.97 L 15.987 10.97 C 14.814 14.108 12.028 16.425 8.242 16.425 C 3.726 16.425 0 12.787 0 8.243 C 0 3.698 3.726 0 8.242 0 C 10.502 0 12.847 1.026 14.431 2.845 C 15.809 4.372 16.6 6.511 16.367 9.093 L 1.701 9.093 Z M 14.814 7.712 C 14.608 4.749 12.026 1.582 8.242 1.582 C 4.459 1.582 1.849 4.662 1.671 7.712 Z" fill="rgb(255, 255, 255)" height="16.4251px" id="miuCWcRlt" transform="translate(162.78 13.976)" width="16.40743060664854px"/><path d="M 4.93 2.039 C 2.555 3.271 1.937 5.47 1.937 6.146 L 1.937 15.912 L 0 15.912 L 0 0.543 L 1.937 0.543 L 1.937 3.446 C 1.994 3.358 2.935 1.539 5.045 0.543 C 7.157 -0.425 8.448 0.19 8.505 0.22 L 8.505 1.569 C 8.418 1.539 6.746 1.071 4.927 2.039 Z" fill="rgb(255, 255, 255)" height="15.91228382167905px" id="aUCIawkuZ" transform="translate(180.964 13.928)" width="8.504999999999995px"/><path d="M 6.161 1.349 C 3.521 1.349 2.025 2.875 2.23 4.869 C 2.435 6.776 5.751 7.129 7.275 7.597 C 9.239 8.213 12.144 8.801 12.144 11.498 C 12.174 14.313 9.857 16.455 6.161 16.455 C 1.937 16.455 0 13.17 0 11 L 1.907 11 C 1.907 13.082 3.404 15.136 6.161 15.136 C 8.743 15.136 10.443 13.64 10.327 11.528 C 10.18 9.504 7.63 9.181 6.369 8.74 C 4.139 8.007 0.473 7.567 0.356 4.809 C 0.238 2.022 2.878 0 6.164 0 C 10.387 0 12.001 3.373 12.001 5.25 L 10.095 5.25 C 10.095 3.313 8.598 1.349 6.164 1.349 Z" fill="rgb(255, 255, 255)" height="16.4551px" id="rKmBDBvEO" transform="translate(188.856 13.946)" width="12.144287854396623px"/><path d="M 0 13.565 L 0 20.556 L 23.392 6.996 L 23.389 0 Z" fill="rgb(255, 255, 255)" height="20.55642px" id="sueM4yXL_" transform="translate(0 3.798)" width="23.3915px"/><path d="M 6.123 3.481 L 6.123 15.89 L 0 19.45 L 0 0 Z" fill="rgb(255, 255, 255)" height="19.45045px" id="KaHsCjO8D" transform="translate(24.227 3.313)" width="6.123100000000001px"/><path d="M 0 2.58 L 4.452 5.027 L 4.452 0 Z" fill="rgb(255, 255, 255)" height="5.027100000000001px" id="QaN_1leFS" transform="translate(0.863 22.25)" width="4.451598px"/><path d="M 0 2.537 L 4.381 4.94 L 4.381 0 Z" fill="rgb(255, 255, 255)" height="4.939599999999999px" id="O8MjoRp3s" transform="translate(25.969 28.188)" width="4.381499999999999px"/><path d="M 0 0 L 0 12.812 L 5.788 9.459 L 5.788 3.303 Z" fill="rgb(255, 255, 255)" height="12.8118px" id="uvKJMKQmN" transform="translate(6.166 0)" width="5.78782px"/><path d="M 0.01 0 L 0 5.2 L 4.622 2.53 Z" fill="rgb(255, 255, 255)" height="5.199800000000003px" id="qR_t9VF6i" transform="translate(12.807 32.367)" width="4.621799999999999px"/><path d="M 5.788 0 L 0 3.358 L 0 16.115 L 5.788 19.456 Z" fill="rgb(255, 255, 255)" height="19.4555px" id="n1CDQdI8Y" transform="translate(6.166 18.399)" width="5.78782px"/><path d="M 0 10.162 L 6.223 13.605 L 17.591 7.037 L 17.591 0 Z" fill="rgb(255, 255, 255)" height="13.6051px" id="zpzeKYNgo" transform="translate(18.877 16.65)" width="17.5912px"/><path d="M 0 0 L 0.01 6.941 L 17.544 16.6 L 23.699 13.029 Z" fill="rgb(255, 255, 255)" height="16.600299999999997px" id="Za4WI7_WJ" transform="translate(12.807 24.46)" width="23.6993px"/><path d="M 0.629 0 L 2.514 4.549 L 4.398 0 L 5.031 0 L 5.031 5.191 L 4.594 5.191 L 4.594 0.579 L 2.691 5.191 L 2.346 5.191 L 0.443 0.585 L 0.443 5.191 L 0 5.191 L 0 0 L 0.632 0 Z" fill="rgb(255, 255, 255)" height="5.1907px" id="CKKZc3ZzS" transform="translate(43 35.201)" width="5.0305000000000035px"/><path d="M 3.061 4.438 C 2.672 4.993 1.976 5.251 1.486 5.251 C 0.658 5.251 0 4.752 0 3.806 C 0 2.953 0.942 2.512 1.353 2.418 C 1.157 2.154 0.62 1.756 0.591 1.187 C 0.566 0.482 1.182 0 1.79 0 C 2.498 0 3.042 0.435 3.042 1.244 C 3.042 1.836 2.409 2.361 1.979 2.569 L 3.064 3.849 C 3.225 3.615 3.374 2.987 3.374 2.709 L 3.797 2.709 C 3.75 3.164 3.576 3.756 3.307 4.147 L 4.129 5.124 L 3.639 5.124 L 3.067 4.441 Z M 1.603 2.692 C 1.065 2.806 0.433 3.184 0.433 3.809 C 0.433 4.508 0.892 4.92 1.502 4.92 C 2.112 4.92 2.545 4.542 2.827 4.157 Z M 1.831 0.308 C 1.347 0.308 1.009 0.686 1.009 1.127 C 1.009 1.525 1.486 2.08 1.777 2.301 C 2.112 2.151 2.631 1.739 2.631 1.204 C 2.631 0.699 2.393 0.308 1.831 0.308 Z" fill="rgb(255, 255, 255)" height="5.2509000000000015px" id="Yv9BGi2jp" transform="translate(49.564 35)" width="4.129300000000001px"/><path d="M 2.722 0 L 4.904 5.191 L 4.48 5.191 L 3.854 3.722 L 1.062 3.722 L 0.436 5.191 L 0 5.191 L 2.201 0 L 2.725 0 Z M 1.202 3.398 L 3.712 3.398 L 2.454 0.451 Z" fill="rgb(255, 255, 255)" height="5.1907px" id="sp8wYAcXb" transform="translate(54.5 35.201)" width="4.903999999999996px"/><path d="M 2.722 0 L 4.904 5.191 L 4.48 5.191 L 3.854 3.722 L 1.062 3.722 L 0.436 5.191 L 0 5.191 L 2.201 0 L 2.725 0 Z M 1.202 3.398 L 3.712 3.398 L 2.454 0.451 Z" fill="rgb(255, 255, 255)" height="5.1907px" id="P4lt6e7Rs" transform="translate(62.904 35.201)" width="4.903999999999996px"/><path d="M 3.525 4.465 C 3.149 4.943 2.672 5.318 1.824 5.318 C 0.977 5.318 0 4.549 0 3.331 C 0 2.114 0.955 1.331 1.824 1.331 C 2.694 1.331 3.095 1.659 3.525 2.207 L 3.525 0 L 3.962 0 L 3.962 5.191 L 3.525 5.191 Z M 2.011 4.993 C 2.865 4.993 3.573 4.261 3.573 3.334 C 3.573 2.408 2.887 1.682 2.017 1.682 C 1.148 1.682 0.449 2.415 0.449 3.334 C 0.449 4.254 1.135 4.993 2.011 4.993 Z" fill="rgb(255, 255, 255)" height="5.317799999999998px" id="lGGhIxpVD" transform="translate(68.238 35.214)" width="3.961800000000011px"/><path d="M 0.487 0 L 1.764 3.211 L 3.042 0 L 3.519 0 L 1.992 3.722 L 1.534 3.722 L 0 0 Z" fill="rgb(255, 255, 255)" height="3.7224000000000004px" id="Obt61Nowr" transform="translate(72.952 36.752)" width="3.519199999999998px"/><path d="M 0.436 0.328 L 0 0.328 L 0 0 L 0.436 0 Z M 0.436 5.191 L 0 5.191 L 0 1.331 L 0.436 1.331 Z" fill="rgb(255, 255, 255)" height="5.19069998703003px" id="vw59luFvh" transform="translate(77.135 35.201)" width="1px"/><path d="M 1.413 0.328 C 0.806 0.328 0.465 0.699 0.512 1.181 C 0.56 1.642 1.319 1.729 1.669 1.843 C 2.122 1.993 2.786 2.134 2.786 2.789 C 2.792 3.472 2.261 3.993 1.413 3.993 C 0.446 3.993 0 3.197 0 2.669 L 0.436 2.669 C 0.436 3.174 0.781 3.672 1.413 3.672 C 2.005 3.672 2.397 3.308 2.368 2.796 C 2.333 2.304 1.748 2.227 1.461 2.12 C 0.949 1.943 0.107 1.836 0.082 1.167 C 0.054 0.492 0.661 0 1.413 0 C 2.384 0 2.754 0.819 2.754 1.274 L 2.318 1.274 C 2.318 0.803 1.976 0.328 1.416 0.328 Z" fill="rgb(255, 255, 255)" height="3.993300000000005px" id="PgD12ztc6" transform="translate(78.264 36.612)" width="2.7856554260391704px"/><path d="M 1.91 0 C 2.972 0 3.819 0.903 3.819 2.024 C 3.819 3.144 2.972 4.054 1.91 4.054 C 0.847 4.054 0 3.151 0 2.024 C 0 0.896 0.854 0 1.91 0 Z M 0.367 2.013 C 0.367 2.91 1.066 3.659 1.91 3.659 C 2.754 3.659 3.45 2.927 3.45 2.03 C 3.45 1.134 2.764 0.391 1.916 0.391 C 1.069 0.391 0.367 1.124 0.367 2.013 Z" fill="rgb(255, 255, 255)" height="4.053600000000003px" id="foA7n1hlj" transform="translate(81.726 36.548)" width="3.819499999999991px"/><path d="M 1.129 0.493 C 0.585 0.791 0.443 1.326 0.443 1.49 L 0.443 3.861 L 0 3.861 L 0 0.132 L 0.443 0.132 L 0.443 0.837 C 0.455 0.817 0.67 0.376 1.157 0.132 C 1.641 -0.102 1.938 0.045 1.951 0.055 L 1.951 0.383 C 1.932 0.376 1.546 0.262 1.129 0.496 Z" fill="rgb(255, 255, 255)" height="3.860826369589411px" id="k5aYRf81s" transform="translate(86.314 36.611)" width="1.950800000000001px"/><path d="M 0.496 0 L 1.774 3.204 L 3.051 0 L 3.529 0 L 1.394 5.191 L 0.977 5.191 L 1.556 3.746 L 0 0 Z" fill="rgb(255, 255, 255)" height="5.1907px" id="Qk0qQI08R" transform="translate(88.669 36.809)" width="3.5285999999999973px"/><path d="M 0.62 1.318 C 0.275 1.318 0 1.027 0 0.662 C 0 0.298 0.275 0 0.62 0 C 0.964 0 1.239 0.298 1.239 0.662 C 1.239 1.027 0.964 1.318 0.62 1.318 Z" fill="rgb(255, 255, 255)" height="1.317699999999995px" id="UvfhJgcqn" transform="translate(97.39 37.819)" width="1.2394000000000034px"/><path d="M 0.436 0 L 0.436 5.191 L 0 5.191 L 0 0 Z" fill="rgb(255, 255, 255)" height="5.1907px" id="Q3xjhsKOv" transform="translate(103.755 35.201)" width="1px"/><path d="M 3.396 3.87 L 2.959 3.87 L 2.959 1.435 C 2.959 0.956 2.381 0.331 1.701 0.331 C 1.062 0.331 0.443 0.95 0.443 1.428 L 0.443 3.87 L 0 3.87 L 0 0.14 L 0.443 0.14 L 0.443 0.739 C 0.462 0.702 0.879 0 1.891 0 C 2.751 0 3.399 0.789 3.399 1.538 L 3.399 3.873 Z" fill="rgb(255, 255, 255)" height="3.8729000000000013px" id="PA0q_YXTt" transform="translate(104.934 36.599)" width="3.399000000000001px"/><path d="M 0.487 0 L 1.765 3.211 L 3.042 0 L 3.519 0 L 1.992 3.722 L 1.534 3.722 L 0 0 Z" fill="rgb(255, 255, 255)" height="3.7224000000000004px" id="WMOxgqPnQ" transform="translate(108.867 36.752)" width="3.5189999999999912px"/><path d="M 0.389 2.204 C 0.455 2.893 1.034 3.622 1.891 3.622 C 2.691 3.622 3.102 3.03 3.257 2.662 L 3.668 2.662 C 3.399 3.425 2.76 3.987 1.891 3.987 C 0.854 3.987 0 3.104 0 2 C 0 0.896 0.854 0 1.891 0 C 2.409 0 2.947 0.251 3.31 0.689 C 3.627 1.06 3.81 1.579 3.756 2.204 Z M 3.399 1.87 C 3.352 1.151 2.76 0.381 1.891 0.381 C 1.021 0.381 0.424 1.127 0.383 1.87 Z" fill="rgb(255, 255, 255)" height="3.986699999999999px" id="OthKZAb9W" transform="translate(112.652 36.622)" width="3.7653860948311824px"/><path d="M 1.413 0.328 C 0.806 0.328 0.465 0.699 0.512 1.181 C 0.559 1.642 1.318 1.729 1.669 1.843 C 2.121 1.993 2.785 2.134 2.785 2.789 C 2.792 3.472 2.26 3.993 1.413 3.993 C 0.446 3.993 0 3.197 0 2.669 L 0.436 2.669 C 0.436 3.174 0.781 3.672 1.413 3.672 C 2.004 3.672 2.396 3.308 2.368 2.796 C 2.333 2.304 1.748 2.227 1.46 2.12 C 0.948 1.943 0.107 1.836 0.082 1.167 C 0.053 0.492 0.661 0 1.413 0 C 2.384 0 2.754 0.819 2.754 1.274 L 2.317 1.274 C 2.317 0.803 1.976 0.328 1.416 0.328 Z" fill="rgb(255, 255, 255)" height="3.993300000000005px" id="ciJYZP1cO" transform="translate(117.12 36.612)" width="2.785068243274509px"/><path d="M 1.284 5.187 L 0.854 5.187 L 0.854 1.793 L 0 1.793 L 0 1.465 L 0.854 1.465 L 0.854 0 L 1.284 0 L 1.284 1.465 L 2.131 1.465 L 2.131 1.793 L 1.284 1.793 Z" fill="rgb(255, 255, 255)" height="5.1873000000000005px" id="hsBMLYZHI" transform="translate(120.326 35.204)" width="2.1310000000000002px"/><path d="M 5.027 3.863 L 4.61 3.863 L 4.61 1.194 C 4.61 0.639 4.132 0.331 3.667 0.331 C 3.203 0.331 2.671 0.686 2.671 1.194 L 2.671 3.863 L 2.302 3.863 L 2.302 1.194 C 2.302 0.632 1.824 0.331 1.432 0.331 C 1.021 0.331 0.423 0.652 0.423 1.227 L 0.423 3.863 L 0 3.863 L 0 0.14 L 0.423 0.14 L 0.423 0.562 C 0.442 0.532 0.793 0 1.527 0 C 2.194 0 2.523 0.619 2.542 0.655 C 2.561 0.619 2.965 0 3.775 0 C 4.502 0 5.027 0.642 5.027 1.331 L 5.027 3.866 Z" fill="rgb(255, 255, 255)" height="3.866199999999999px" id="AfUG7WuDE" transform="translate(123.216 36.605)" width="5.027000000000001px"/><path d="M 0.389 2.204 C 0.455 2.893 1.034 3.622 1.891 3.622 C 2.69 3.622 3.102 3.03 3.256 2.662 L 3.667 2.662 C 3.399 3.425 2.76 3.987 1.891 3.987 C 0.853 3.987 0 3.104 0 2 C 0 0.896 0.853 0 1.891 0 C 2.409 0 2.947 0.251 3.31 0.689 C 3.626 1.06 3.81 1.579 3.756 2.204 Z M 3.399 1.87 C 3.351 1.151 2.76 0.381 1.891 0.381 C 1.021 0.381 0.423 1.127 0.382 1.87 Z" fill="rgb(255, 255, 255)" height="3.986699999999999px" id="nK4KLjWvd" transform="translate(129.078 36.622)" width="3.7653500179975223px"/><path d="M 3.396 3.87 L 2.959 3.87 L 2.959 1.435 C 2.959 0.956 2.381 0.331 1.701 0.331 C 1.062 0.331 0.443 0.95 0.443 1.428 L 0.443 3.87 L 0 3.87 L 0 0.14 L 0.443 0.14 L 0.443 0.739 C 0.462 0.702 0.879 0 1.891 0 C 2.751 0 3.399 0.789 3.399 1.538 L 3.399 3.873 Z" fill="rgb(255, 255, 255)" height="3.8729000000000013px" id="FAdN09aYl" transform="translate(133.691 36.599)" width="3.399000000000001px"/><path d="M 1.283 5.187 L 0.853 5.187 L 0.853 1.793 L 0 1.793 L 0 1.465 L 0.853 1.465 L 0.853 0 L 1.283 0 L 1.283 1.465 L 2.131 1.465 L 2.131 1.793 L 1.283 1.793 Z" fill="rgb(255, 255, 255)" height="5.1873000000000005px" id="rPmG4YvO9" transform="translate(137.672 35.204)" width="2.1310000000000002px"/><path d="M 1.414 0.328 C 0.807 0.328 0.465 0.699 0.513 1.181 C 0.56 1.642 1.319 1.729 1.67 1.843 C 2.122 1.993 2.786 2.134 2.786 2.789 C 2.792 3.472 2.261 3.993 1.414 3.993 C 0.446 3.993 0 3.197 0 2.669 L 0.437 2.669 C 0.437 3.174 0.781 3.672 1.414 3.672 C 2.005 3.672 2.397 3.308 2.369 2.796 C 2.334 2.304 1.749 2.227 1.461 2.12 C 0.949 1.943 0.108 1.836 0.083 1.167 C 0.054 0.492 0.661 0 1.414 0 C 2.384 0 2.754 0.819 2.754 1.274 L 2.318 1.274 C 2.318 0.803 1.977 0.328 1.417 0.328 Z" fill="rgb(255, 255, 255)" height="3.993300000000005px" id="yigdtUGQl" transform="translate(140.188 36.612)" width="2.7860503179292095px"/><path d="M 0.62 1.318 C 0.275 1.318 0 1.027 0 0.662 C 0 0.298 0.275 0 0.62 0 C 0.964 0 1.239 0.298 1.239 0.662 C 1.239 1.027 0.964 1.318 0.62 1.318 Z" fill="rgb(255, 255, 255)" height="1.317699999999995px" id="A9BLuCh5E" transform="translate(148.128 37.819)" width="1.2390000000000043px"/><path d="M 4.563 1.729 C 4.342 1.154 3.621 0.398 2.584 0.398 C 1.468 0.398 0.402 1.368 0.402 2.726 C 0.402 4.084 1.458 5.053 2.584 5.053 C 3.633 5.053 4.332 4.291 4.563 3.722 L 4.987 3.722 C 4.658 4.642 3.735 5.445 2.584 5.445 C 1.164 5.445 0 4.227 0 2.726 C 0 1.224 1.164 0 2.584 0 C 3.735 0 4.652 0.806 4.987 1.729 Z" fill="rgb(255, 255, 255)" height="5.444800000000001px" id="tMM9qOUdD" transform="translate(154.568 35.074)" width="4.986999999999995px"/><path d="M 3.092 0 L 3.092 0.328 L 0.446 0.328 L 0.446 2.194 L 3.029 2.194 L 3.029 2.528 L 0.446 2.528 L 0.446 5.191 L 0 5.191 L 0 0 Z" fill="rgb(255, 255, 255)" height="5.1907px" id="HdCqFaxpa" transform="translate(160.475 35.201)" width="3.092000000000013px"/><path d="M 2.577 0 C 4.003 0 5.154 1.217 5.154 2.726 C 5.154 4.234 4.003 5.445 2.577 5.445 C 1.151 5.445 0 4.227 0 2.726 C 0 1.224 1.157 0 2.577 0 Z M 0.398 2.726 C 0.398 4 1.375 5.033 2.58 5.033 C 3.785 5.033 4.762 4 4.762 2.726 C 4.762 1.452 3.785 0.418 2.58 0.418 C 1.375 0.418 0.398 1.445 0.398 2.726 Z" fill="rgb(255, 255, 255)" height="5.444800000000001px" id="YTLuHpHRE" transform="translate(164.231 35.074)" width="5.153999999999996px"/><path d="M 1.771 0.341 C 1.091 0.341 0.572 0.783 0.572 1.472 C 0.572 2.161 1.758 2.381 2.229 2.602 C 2.808 2.866 3.5 3.037 3.5 3.896 C 3.5 4.709 2.748 5.448 1.777 5.448 C 0.62 5.448 0 4.495 0 3.833 L 0.446 3.833 C 0.446 4.465 0.965 5.12 1.771 5.12 C 2.647 5.12 3.064 4.431 3.064 3.933 C 3.064 3.151 2.403 3.1 1.96 2.9 C 1.281 2.602 0.142 2.371 0.142 1.482 C 0.142 0.686 0.87 0 1.771 0 C 2.726 0 3.38 0.776 3.399 1.438 L 2.963 1.438 C 2.963 1.027 2.485 0.334 1.771 0.334 Z" fill="rgb(255, 255, 255)" height="5.4482px" id="DmJ2Y_yAT" transform="translate(172.85 35.067)" width="3.5px"/><path d="M 0.389 2.204 C 0.455 2.893 1.034 3.622 1.89 3.622 C 2.69 3.622 3.101 3.03 3.256 2.662 L 3.667 2.662 C 3.399 3.425 2.76 3.987 1.89 3.987 C 0.853 3.987 0 3.104 0 2 C 0 0.896 0.853 0 1.89 0 C 2.409 0 2.946 0.251 3.31 0.689 C 3.626 1.06 3.81 1.579 3.756 2.204 Z M 3.399 1.87 C 3.351 1.151 2.76 0.381 1.89 0.381 C 1.021 0.381 0.423 1.127 0.382 1.87 Z" fill="rgb(255, 255, 255)" height="3.986699999999999px" id="yMUVUZg9o" transform="translate(177.119 36.622)" width="3.7653500179975223px"/><path d="M 1.129 0.493 C 0.585 0.791 0.443 1.326 0.443 1.49 L 0.443 3.861 L 0 3.861 L 0 0.132 L 0.443 0.132 L 0.443 0.837 C 0.455 0.817 0.67 0.376 1.157 0.132 C 1.641 -0.102 1.938 0.045 1.951 0.055 L 1.951 0.383 C 1.932 0.376 1.546 0.262 1.129 0.496 Z" fill="rgb(255, 255, 255)" height="3.860826369589411px" id="px2Eh9pZT" transform="translate(181.697 36.611)" width="1.9509999999999934px"/><path d="M 0.487 0 L 1.764 3.211 L 3.042 0 L 3.519 0 L 1.992 3.722 L 1.533 3.722 L 0 0 Z" fill="rgb(255, 255, 255)" height="3.7224000000000004px" id="OCJj23ndt" transform="translate(184.021 36.752)" width="3.5190000000000055px"/><path d="M 0.436 0.328 L 0 0.328 L 0 0 L 0.436 0 Z M 0.436 5.191 L 0 5.191 L 0 1.331 L 0.436 1.331 Z" fill="rgb(255, 255, 255)" height="5.19069998703003px" id="N4v92LZAN" transform="translate(188.204 35.201)" width="1px"/><path d="M 3.256 1.331 C 3.162 1.067 2.713 0.405 1.884 0.405 C 1.116 0.405 0.376 1.06 0.376 2 C 0.376 2.94 1.129 3.602 1.884 3.602 C 2.678 3.602 3.13 3.003 3.256 2.669 L 3.667 2.669 C 3.392 3.438 2.751 3.993 1.884 3.993 C 0.853 3.993 0 3.104 0 2 C 0 0.896 0.853 0 1.884 0 C 2.754 0 3.446 0.625 3.667 1.331 Z" fill="rgb(255, 255, 255)" height="3.993300000000005px" id="x54xXVLtV" transform="translate(189.352 36.612)" width="3.6670000000000016px"/><path d="M 0.389 2.204 C 0.455 2.893 1.034 3.622 1.891 3.622 C 2.69 3.622 3.101 3.03 3.256 2.662 L 3.667 2.662 C 3.399 3.425 2.76 3.987 1.891 3.987 C 0.853 3.987 0 3.104 0 2 C 0 0.896 0.853 0 1.891 0 C 2.409 0 2.947 0.251 3.31 0.689 C 3.626 1.06 3.81 1.579 3.756 2.204 Z M 3.399 1.87 C 3.351 1.151 2.76 0.381 1.891 0.381 C 1.021 0.381 0.423 1.127 0.382 1.87 Z" fill="rgb(255, 255, 255)" height="3.986699999999999px" id="xkGiviUHf" transform="translate(193.747 36.622)" width="3.765350017997494px"/><path d="M 1.414 0.328 C 0.807 0.328 0.465 0.699 0.513 1.181 C 0.56 1.642 1.319 1.729 1.67 1.843 C 2.122 1.993 2.786 2.134 2.786 2.789 C 2.792 3.472 2.261 3.993 1.414 3.993 C 0.446 3.993 0 3.197 0 2.669 L 0.437 2.669 C 0.437 3.174 0.781 3.672 1.414 3.672 C 2.005 3.672 2.397 3.308 2.369 2.796 C 2.334 2.304 1.749 2.227 1.461 2.12 C 0.949 1.943 0.108 1.836 0.083 1.167 C 0.054 0.492 0.661 0 1.414 0 C 2.384 0 2.754 0.819 2.754 1.274 L 2.318 1.274 C 2.318 0.803 1.977 0.328 1.417 0.328 Z" fill="rgb(255, 255, 255)" height="3.993300000000005px" id="N8bEmWbbj" transform="translate(198.214 36.612)" width="2.7860503179292664px"/></svg>)


Due diligence should help a buyer or investor decide whether to proceed, on what terms and with which post-closing priorities. Its value is not the length of the report. It is the connection between evidence, financial consequences and decisions. A useful review distinguishes confirmed findings from unresolved questions and explains how each material issue affects the investment case.
Define the transaction question before requesting documents
A control acquisition, minority investment and asset purchase create different questions. Start with the proposed structure, commercial rationale, funding plan and information available. Agree the scope and materiality with the relevant financial, legal, tax and operational specialists. No review can eliminate every risk, and missing information should be visible rather than treated as reassurance.
Build the request list around decisions. If customer retention drives value, examine contracts, concentration, renewal behavior and margins. If production capacity is central, examine utilization, maintenance requirements, permits and investment needs. A standard request list can provide coverage, but it should not replace an understanding of what makes this transaction work.
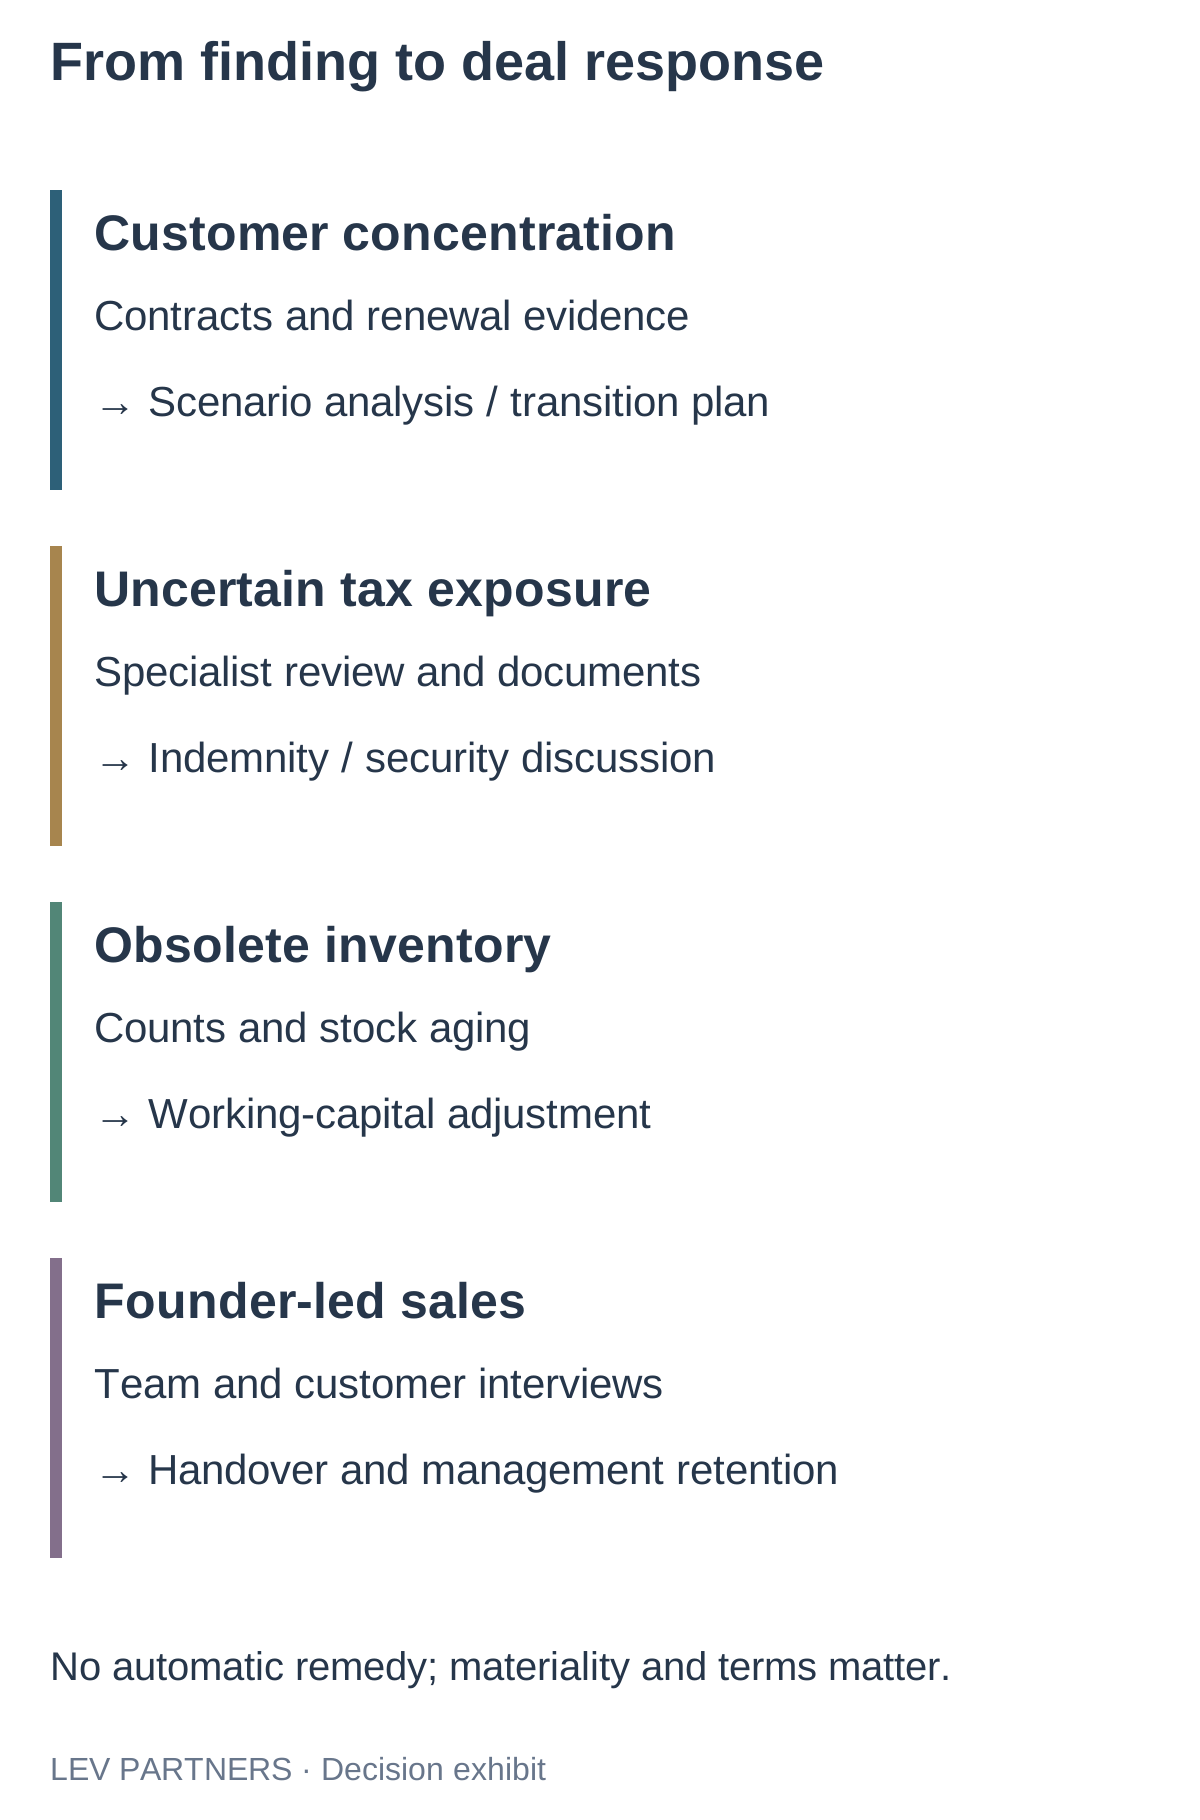
Translate findings into possible transaction responses
The exhibit links four common issues to supporting evidence and possible responses. These are not automatic remedies. Materiality, the transaction structure and negotiation determine whether an issue changes price, contract protections, closing conditions or the integration plan. Legal drafting and specialist conclusions belong with the relevant advisers.
Follow an earnings adjustment through the valuation
Assume, purely for illustration, that reported EBITDA is 10 million. Removing 1 million of non-recurring income reduces it to 9 million. An agreed 0.5 million add-back brings it to 9.5 million, but a 0.5 million recurring replacement cost takes it back to 9 million. The result depends on evidence and consistent treatment, not on whether an adjustment helps the buyer or seller.
At an illustrative unchanged multiple of 6 times, the difference between 10 million and 9 million of EBITDA is 6 million of enterprise value. This is not a recommended market multiple or a price conclusion. It shows why the earnings definition matters. Debt, cash, working capital and other agreed adjustments must still be considered separately when determining equity proceeds.
Keep cash, debt and working capital definitions consistent
An amount should not be counted twice through different adjustments. Review the treatment of overdue payables, customer deposits, restricted cash and other items with the transaction team. The appropriate classification depends on the business and the agreement. A clear schedule of definitions is often more useful than a long list of labels.
Working capital also requires a reference period that reflects the business. A single month may be distorted by seasonality, delayed payments or unusual inventory. Compare the proposed benchmark with underlying operating patterns and understand what the purchaser needs to run the company after closing.
Maintain a finding register that drives action
For each material issue, record the evidence, open questions, potential financial effect, responsible adviser and proposed response. Distinguish a confirmed liability from a possible exposure. Where quantification is not yet possible, state what information is required and who will obtain it.
Not every finding should become a price reduction. Some require a specific contractual protection; others require operational work after closing. An unresolved issue may justify delaying or abandoning a transaction, but that judgment should follow its importance to the investment case and the available alternatives.
Use the work after signing
Transfer relevant findings into the closing checklist and the post-acquisition plan. Customer retention, reporting improvements and management continuity do not become less important when negotiations end. Assign owners and review progress against the issues identified during diligence.
Lev Partners supports financial analysis and transaction coordination alongside the appropriate specialists. The objective is a decision-ready picture of the business, with explicit assumptions and practical next steps, rather than a promise that every uncertainty can be removed.
Explore due diligence services or discuss your proposed transaction.
Your M&A advisory contact
Erim N. Kargacı — Founding Partner and Head of M&A, Lev Partners. Erim leads Lev’s M&A advisory and supports owners considering investment, acquisitions or a company sale. He is also listed among Endeavor Türkiye’s mentors.
Contact us today to discuss your transaction. Tell us about your business and objectives through our confidential contact form →.