" height="21.382199999999997px" id="kC7fwj2cp" transform="translate(43.2 8.135)" width="13.727599999999995px"/><path d="M 4.136 9.621 C 4.607 11.498 6.131 12.702 8.243 12.702 C 10.062 12.702 11.088 11.908 11.616 11 L 15.957 11 C 14.696 14.286 11.999 16.485 8.243 16.485 C 3.726 16.485 0 12.789 0 8.242 C 0 3.696 3.726 0 8.243 0 C 10.385 0 12.934 0.998 14.636 3.08 C 15.897 4.664 16.66 6.806 16.338 9.621 Z M 11.999 6.366 C 11.353 4.634 9.739 3.786 8.127 3.786 C 6.191 3.786 4.872 4.9 4.226 6.366 Z" fill="rgb(255, 255, 255)" height="16.4851px" id="gR7ROinvv" transform="translate(57.746 13.913)" width="16.41157892546896px"/><path d="M 4.752 0 L 7.685 9.944 L 10.617 0 L 15.369 0 L 9.914 15.399 L 5.455 15.399 L 0 0 Z" fill="rgb(255, 255, 255)" height="15.3991px" id="gNXCG2VXg" transform="translate(74.406 14.471)" width="15.369199999999992px"/><path d="M 15.372 6.631 C 15.372 10.502 12.056 13.202 8.801 13.202 L 1.937 13.202 L 1.937 21.385 L 0 21.385 L 0 0 L 8.801 0 C 12.056 0 15.372 2.67 15.372 6.629 Z M 1.939 11.821 L 8.951 11.821 C 11.443 11.821 13.437 9.561 13.437 6.629 C 13.437 3.696 11.531 1.379 8.951 1.379 L 1.939 1.379 Z" fill="rgb(255, 255, 255)" height="21.38469px" id="hre4mzAEc" transform="translate(91.857 8.135)" width="15.371899999999997px"/><path d="M 15.372 12.907 C 13.73 14.901 11.646 16.455 7.95 16.455 C 4.254 16.455 0 13.257 0 8.243 C 0 3.228 4.164 0 7.95 0 C 11.736 0 13.493 1.349 15.372 3.608 L 15.372 0.588 L 17.279 0.588 L 17.279 15.93 L 15.372 15.93 Z M 8.773 15.076 C 12.499 15.076 15.577 12.056 15.577 8.273 C 15.577 4.489 12.584 1.469 8.801 1.469 C 5.017 1.469 1.967 4.462 1.967 8.245 C 1.967 12.029 4.96 15.079 8.771 15.079 Z" fill="rgb(255, 255, 255)" height="16.455199999999998px" id="qtTPusYyi" transform="translate(106.698 13.943)" width="17.27900000000001px"/><path d="M 4.93 2.039 C 2.555 3.271 1.937 5.47 1.937 6.146 L 1.937 15.912 L 0 15.912 L 0 0.543 L 1.937 0.543 L 1.937 3.446 C 1.995 3.358 2.936 1.539 5.045 0.543 C 7.157 -0.425 8.448 0.19 8.506 0.22 L 8.506 1.569 C 8.418 1.539 6.747 1.071 4.927 2.039 Z" fill="rgb(255, 255, 255)" height="15.91228382167905px" id="zfo3WjwfH" transform="translate(125.823 13.928)" width="8.506000000000014px"/><path d="M 5.603 21.382 L 3.726 21.382 L 3.726 7.392 L 0 7.392 L 0 6.043 L 3.726 6.043 L 3.726 0 L 5.603 0 L 5.603 6.043 L 9.298 6.043 L 9.298 7.392 L 5.603 7.392 Z" fill="rgb(255, 255, 255)" height="21.382179999999998px" id="Qgg8g1qom" transform="translate(135.62 8.138)" width="9.298000000000002px"/><path d="M 14.814 15.955 L 12.907 15.955 L 12.907 5.923 C 12.907 3.959 10.385 1.376 7.422 1.376 C 4.634 1.376 1.937 3.929 1.937 5.893 L 1.937 15.955 L 0 15.955 L 0 0.585 L 1.937 0.585 L 1.937 3.05 C 2.025 2.903 3.844 0 8.243 0 C 11.996 0 14.814 3.255 14.814 6.336 L 14.814 15.957 Z" fill="rgb(255, 255, 255)" height="15.957199999999998px" id="BdlnNQExg" transform="translate(146.297 13.888)" width="14.813999999999993px"/><path d="M 1.704 9.091 C 1.997 11.936 4.519 14.929 8.245 14.929 C 11.736 14.929 13.525 12.494 14.198 10.97 L 15.987 10.97 C 14.814 14.108 12.028 16.425 8.242 16.425 C 3.726 16.425 0 12.787 0 8.243 C 0 3.698 3.726 0 8.242 0 C 10.502 0 12.847 1.026 14.431 2.845 C 15.809 4.372 16.6 6.511 16.367 9.093 L 1.701 9.093 Z M 14.814 7.712 C 14.608 4.749 12.026 1.582 8.242 1.582 C 4.459 1.582 1.849 4.662 1.671 7.712 Z" fill="rgb(255, 255, 255)" height="16.4251px" id="miuCWcRlt" transform="translate(162.78 13.976)" width="16.40743060664854px"/><path d="M 4.93 2.039 C 2.555 3.271 1.937 5.47 1.937 6.146 L 1.937 15.912 L 0 15.912 L 0 0.543 L 1.937 0.543 L 1.937 3.446 C 1.994 3.358 2.935 1.539 5.045 0.543 C 7.157 -0.425 8.448 0.19 8.505 0.22 L 8.505 1.569 C 8.418 1.539 6.746 1.071 4.927 2.039 Z" fill="rgb(255, 255, 255)" height="15.91228382167905px" id="aUCIawkuZ" transform="translate(180.964 13.928)" width="8.504999999999995px"/><path d="M 6.161 1.349 C 3.521 1.349 2.025 2.875 2.23 4.869 C 2.435 6.776 5.751 7.129 7.275 7.597 C 9.239 8.213 12.144 8.801 12.144 11.498 C 12.174 14.313 9.857 16.455 6.161 16.455 C 1.937 16.455 0 13.17 0 11 L 1.907 11 C 1.907 13.082 3.404 15.136 6.161 15.136 C 8.743 15.136 10.443 13.64 10.327 11.528 C 10.18 9.504 7.63 9.181 6.369 8.74 C 4.139 8.007 0.473 7.567 0.356 4.809 C 0.238 2.022 2.878 0 6.164 0 C 10.387 0 12.001 3.373 12.001 5.25 L 10.095 5.25 C 10.095 3.313 8.598 1.349 6.164 1.349 Z" fill="rgb(255, 255, 255)" height="16.4551px" id="rKmBDBvEO" transform="translate(188.856 13.946)" width="12.144287854396623px"/><path d="M 0 13.565 L 0 20.556 L 23.392 6.996 L 23.389 0 Z" fill="rgb(255, 255, 255)" height="20.55642px" id="sueM4yXL_" transform="translate(0 3.798)" width="23.3915px"/><path d="M 6.123 3.481 L 6.123 15.89 L 0 19.45 L 0 0 Z" fill="rgb(255, 255, 255)" height="19.45045px" id="KaHsCjO8D" transform="translate(24.227 3.313)" width="6.123100000000001px"/><path d="M 0 2.58 L 4.452 5.027 L 4.452 0 Z" fill="rgb(255, 255, 255)" height="5.027100000000001px" id="QaN_1leFS" transform="translate(0.863 22.25)" width="4.451598px"/><path d="M 0 2.537 L 4.381 4.94 L 4.381 0 Z" fill="rgb(255, 255, 255)" height="4.939599999999999px" id="O8MjoRp3s" transform="translate(25.969 28.188)" width="4.381499999999999px"/><path d="M 0 0 L 0 12.812 L 5.788 9.459 L 5.788 3.303 Z" fill="rgb(255, 255, 255)" height="12.8118px" id="uvKJMKQmN" transform="translate(6.166 0)" width="5.78782px"/><path d="M 0.01 0 L 0 5.2 L 4.622 2.53 Z" fill="rgb(255, 255, 255)" height="5.199800000000003px" id="qR_t9VF6i" transform="translate(12.807 32.367)" width="4.621799999999999px"/><path d="M 5.788 0 L 0 3.358 L 0 16.115 L 5.788 19.456 Z" fill="rgb(255, 255, 255)" height="19.4555px" id="n1CDQdI8Y" transform="translate(6.166 18.399)" width="5.78782px"/><path d="M 0 10.162 L 6.223 13.605 L 17.591 7.037 L 17.591 0 Z" fill="rgb(255, 255, 255)" height="13.6051px" id="zpzeKYNgo" transform="translate(18.877 16.65)" width="17.5912px"/><path d="M 0 0 L 0.01 6.941 L 17.544 16.6 L 23.699 13.029 Z" fill="rgb(255, 255, 255)" height="16.600299999999997px" id="Za4WI7_WJ" transform="translate(12.807 24.46)" width="23.6993px"/><path d="M 0.629 0 L 2.514 4.549 L 4.398 0 L 5.031 0 L 5.031 5.191 L 4.594 5.191 L 4.594 0.579 L 2.691 5.191 L 2.346 5.191 L 0.443 0.585 L 0.443 5.191 L 0 5.191 L 0 0 L 0.632 0 Z" fill="rgb(255, 255, 255)" height="5.1907px" id="CKKZc3ZzS" transform="translate(43 35.201)" width="5.0305000000000035px"/><path d="M 3.061 4.438 C 2.672 4.993 1.976 5.251 1.486 5.251 C 0.658 5.251 0 4.752 0 3.806 C 0 2.953 0.942 2.512 1.353 2.418 C 1.157 2.154 0.62 1.756 0.591 1.187 C 0.566 0.482 1.182 0 1.79 0 C 2.498 0 3.042 0.435 3.042 1.244 C 3.042 1.836 2.409 2.361 1.979 2.569 L 3.064 3.849 C 3.225 3.615 3.374 2.987 3.374 2.709 L 3.797 2.709 C 3.75 3.164 3.576 3.756 3.307 4.147 L 4.129 5.124 L 3.639 5.124 L 3.067 4.441 Z M 1.603 2.692 C 1.065 2.806 0.433 3.184 0.433 3.809 C 0.433 4.508 0.892 4.92 1.502 4.92 C 2.112 4.92 2.545 4.542 2.827 4.157 Z M 1.831 0.308 C 1.347 0.308 1.009 0.686 1.009 1.127 C 1.009 1.525 1.486 2.08 1.777 2.301 C 2.112 2.151 2.631 1.739 2.631 1.204 C 2.631 0.699 2.393 0.308 1.831 0.308 Z" fill="rgb(255, 255, 255)" height="5.2509000000000015px" id="Yv9BGi2jp" transform="translate(49.564 35)" width="4.129300000000001px"/><path d="M 2.722 0 L 4.904 5.191 L 4.48 5.191 L 3.854 3.722 L 1.062 3.722 L 0.436 5.191 L 0 5.191 L 2.201 0 L 2.725 0 Z M 1.202 3.398 L 3.712 3.398 L 2.454 0.451 Z" fill="rgb(255, 255, 255)" height="5.1907px" id="sp8wYAcXb" transform="translate(54.5 35.201)" width="4.903999999999996px"/><path d="M 2.722 0 L 4.904 5.191 L 4.48 5.191 L 3.854 3.722 L 1.062 3.722 L 0.436 5.191 L 0 5.191 L 2.201 0 L 2.725 0 Z M 1.202 3.398 L 3.712 3.398 L 2.454 0.451 Z" fill="rgb(255, 255, 255)" height="5.1907px" id="P4lt6e7Rs" transform="translate(62.904 35.201)" width="4.903999999999996px"/><path d="M 3.525 4.465 C 3.149 4.943 2.672 5.318 1.824 5.318 C 0.977 5.318 0 4.549 0 3.331 C 0 2.114 0.955 1.331 1.824 1.331 C 2.694 1.331 3.095 1.659 3.525 2.207 L 3.525 0 L 3.962 0 L 3.962 5.191 L 3.525 5.191 Z M 2.011 4.993 C 2.865 4.993 3.573 4.261 3.573 3.334 C 3.573 2.408 2.887 1.682 2.017 1.682 C 1.148 1.682 0.449 2.415 0.449 3.334 C 0.449 4.254 1.135 4.993 2.011 4.993 Z" fill="rgb(255, 255, 255)" height="5.317799999999998px" id="lGGhIxpVD" transform="translate(68.238 35.214)" width="3.961800000000011px"/><path d="M 0.487 0 L 1.764 3.211 L 3.042 0 L 3.519 0 L 1.992 3.722 L 1.534 3.722 L 0 0 Z" fill="rgb(255, 255, 255)" height="3.7224000000000004px" id="Obt61Nowr" transform="translate(72.952 36.752)" width="3.519199999999998px"/><path d="M 0.436 0.328 L 0 0.328 L 0 0 L 0.436 0 Z M 0.436 5.191 L 0 5.191 L 0 1.331 L 0.436 1.331 Z" fill="rgb(255, 255, 255)" height="5.19069998703003px" id="vw59luFvh" transform="translate(77.135 35.201)" width="1px"/><path d="M 1.413 0.328 C 0.806 0.328 0.465 0.699 0.512 1.181 C 0.56 1.642 1.319 1.729 1.669 1.843 C 2.122 1.993 2.786 2.134 2.786 2.789 C 2.792 3.472 2.261 3.993 1.413 3.993 C 0.446 3.993 0 3.197 0 2.669 L 0.436 2.669 C 0.436 3.174 0.781 3.672 1.413 3.672 C 2.005 3.672 2.397 3.308 2.368 2.796 C 2.333 2.304 1.748 2.227 1.461 2.12 C 0.949 1.943 0.107 1.836 0.082 1.167 C 0.054 0.492 0.661 0 1.413 0 C 2.384 0 2.754 0.819 2.754 1.274 L 2.318 1.274 C 2.318 0.803 1.976 0.328 1.416 0.328 Z" fill="rgb(255, 255, 255)" height="3.993300000000005px" id="PgD12ztc6" transform="translate(78.264 36.612)" width="2.7856554260391704px"/><path d="M 1.91 0 C 2.972 0 3.819 0.903 3.819 2.024 C 3.819 3.144 2.972 4.054 1.91 4.054 C 0.847 4.054 0 3.151 0 2.024 C 0 0.896 0.854 0 1.91 0 Z M 0.367 2.013 C 0.367 2.91 1.066 3.659 1.91 3.659 C 2.754 3.659 3.45 2.927 3.45 2.03 C 3.45 1.134 2.764 0.391 1.916 0.391 C 1.069 0.391 0.367 1.124 0.367 2.013 Z" fill="rgb(255, 255, 255)" height="4.053600000000003px" id="foA7n1hlj" transform="translate(81.726 36.548)" width="3.819499999999991px"/><path d="M 1.129 0.493 C 0.585 0.791 0.443 1.326 0.443 1.49 L 0.443 3.861 L 0 3.861 L 0 0.132 L 0.443 0.132 L 0.443 0.837 C 0.455 0.817 0.67 0.376 1.157 0.132 C 1.641 -0.102 1.938 0.045 1.951 0.055 L 1.951 0.383 C 1.932 0.376 1.546 0.262 1.129 0.496 Z" fill="rgb(255, 255, 255)" height="3.860826369589411px" id="k5aYRf81s" transform="translate(86.314 36.611)" width="1.950800000000001px"/><path d="M 0.496 0 L 1.774 3.204 L 3.051 0 L 3.529 0 L 1.394 5.191 L 0.977 5.191 L 1.556 3.746 L 0 0 Z" fill="rgb(255, 255, 255)" height="5.1907px" id="Qk0qQI08R" transform="translate(88.669 36.809)" width="3.5285999999999973px"/><path d="M 0.62 1.318 C 0.275 1.318 0 1.027 0 0.662 C 0 0.298 0.275 0 0.62 0 C 0.964 0 1.239 0.298 1.239 0.662 C 1.239 1.027 0.964 1.318 0.62 1.318 Z" fill="rgb(255, 255, 255)" height="1.317699999999995px" id="UvfhJgcqn" transform="translate(97.39 37.819)" width="1.2394000000000034px"/><path d="M 0.436 0 L 0.436 5.191 L 0 5.191 L 0 0 Z" fill="rgb(255, 255, 255)" height="5.1907px" id="Q3xjhsKOv" transform="translate(103.755 35.201)" width="1px"/><path d="M 3.396 3.87 L 2.959 3.87 L 2.959 1.435 C 2.959 0.956 2.381 0.331 1.701 0.331 C 1.062 0.331 0.443 0.95 0.443 1.428 L 0.443 3.87 L 0 3.87 L 0 0.14 L 0.443 0.14 L 0.443 0.739 C 0.462 0.702 0.879 0 1.891 0 C 2.751 0 3.399 0.789 3.399 1.538 L 3.399 3.873 Z" fill="rgb(255, 255, 255)" height="3.8729000000000013px" id="PA0q_YXTt" transform="translate(104.934 36.599)" width="3.399000000000001px"/><path d="M 0.487 0 L 1.765 3.211 L 3.042 0 L 3.519 0 L 1.992 3.722 L 1.534 3.722 L 0 0 Z" fill="rgb(255, 255, 255)" height="3.7224000000000004px" id="WMOxgqPnQ" transform="translate(108.867 36.752)" width="3.5189999999999912px"/><path d="M 0.389 2.204 C 0.455 2.893 1.034 3.622 1.891 3.622 C 2.691 3.622 3.102 3.03 3.257 2.662 L 3.668 2.662 C 3.399 3.425 2.76 3.987 1.891 3.987 C 0.854 3.987 0 3.104 0 2 C 0 0.896 0.854 0 1.891 0 C 2.409 0 2.947 0.251 3.31 0.689 C 3.627 1.06 3.81 1.579 3.756 2.204 Z M 3.399 1.87 C 3.352 1.151 2.76 0.381 1.891 0.381 C 1.021 0.381 0.424 1.127 0.383 1.87 Z" fill="rgb(255, 255, 255)" height="3.986699999999999px" id="OthKZAb9W" transform="translate(112.652 36.622)" width="3.7653860948311824px"/><path d="M 1.413 0.328 C 0.806 0.328 0.465 0.699 0.512 1.181 C 0.559 1.642 1.318 1.729 1.669 1.843 C 2.121 1.993 2.785 2.134 2.785 2.789 C 2.792 3.472 2.26 3.993 1.413 3.993 C 0.446 3.993 0 3.197 0 2.669 L 0.436 2.669 C 0.436 3.174 0.781 3.672 1.413 3.672 C 2.004 3.672 2.396 3.308 2.368 2.796 C 2.333 2.304 1.748 2.227 1.46 2.12 C 0.948 1.943 0.107 1.836 0.082 1.167 C 0.053 0.492 0.661 0 1.413 0 C 2.384 0 2.754 0.819 2.754 1.274 L 2.317 1.274 C 2.317 0.803 1.976 0.328 1.416 0.328 Z" fill="rgb(255, 255, 255)" height="3.993300000000005px" id="ciJYZP1cO" transform="translate(117.12 36.612)" width="2.785068243274509px"/><path d="M 1.284 5.187 L 0.854 5.187 L 0.854 1.793 L 0 1.793 L 0 1.465 L 0.854 1.465 L 0.854 0 L 1.284 0 L 1.284 1.465 L 2.131 1.465 L 2.131 1.793 L 1.284 1.793 Z" fill="rgb(255, 255, 255)" height="5.1873000000000005px" id="hsBMLYZHI" transform="translate(120.326 35.204)" width="2.1310000000000002px"/><path d="M 5.027 3.863 L 4.61 3.863 L 4.61 1.194 C 4.61 0.639 4.132 0.331 3.667 0.331 C 3.203 0.331 2.671 0.686 2.671 1.194 L 2.671 3.863 L 2.302 3.863 L 2.302 1.194 C 2.302 0.632 1.824 0.331 1.432 0.331 C 1.021 0.331 0.423 0.652 0.423 1.227 L 0.423 3.863 L 0 3.863 L 0 0.14 L 0.423 0.14 L 0.423 0.562 C 0.442 0.532 0.793 0 1.527 0 C 2.194 0 2.523 0.619 2.542 0.655 C 2.561 0.619 2.965 0 3.775 0 C 4.502 0 5.027 0.642 5.027 1.331 L 5.027 3.866 Z" fill="rgb(255, 255, 255)" height="3.866199999999999px" id="AfUG7WuDE" transform="translate(123.216 36.605)" width="5.027000000000001px"/><path d="M 0.389 2.204 C 0.455 2.893 1.034 3.622 1.891 3.622 C 2.69 3.622 3.102 3.03 3.256 2.662 L 3.667 2.662 C 3.399 3.425 2.76 3.987 1.891 3.987 C 0.853 3.987 0 3.104 0 2 C 0 0.896 0.853 0 1.891 0 C 2.409 0 2.947 0.251 3.31 0.689 C 3.626 1.06 3.81 1.579 3.756 2.204 Z M 3.399 1.87 C 3.351 1.151 2.76 0.381 1.891 0.381 C 1.021 0.381 0.423 1.127 0.382 1.87 Z" fill="rgb(255, 255, 255)" height="3.986699999999999px" id="nK4KLjWvd" transform="translate(129.078 36.622)" width="3.7653500179975223px"/><path d="M 3.396 3.87 L 2.959 3.87 L 2.959 1.435 C 2.959 0.956 2.381 0.331 1.701 0.331 C 1.062 0.331 0.443 0.95 0.443 1.428 L 0.443 3.87 L 0 3.87 L 0 0.14 L 0.443 0.14 L 0.443 0.739 C 0.462 0.702 0.879 0 1.891 0 C 2.751 0 3.399 0.789 3.399 1.538 L 3.399 3.873 Z" fill="rgb(255, 255, 255)" height="3.8729000000000013px" id="FAdN09aYl" transform="translate(133.691 36.599)" width="3.399000000000001px"/><path d="M 1.283 5.187 L 0.853 5.187 L 0.853 1.793 L 0 1.793 L 0 1.465 L 0.853 1.465 L 0.853 0 L 1.283 0 L 1.283 1.465 L 2.131 1.465 L 2.131 1.793 L 1.283 1.793 Z" fill="rgb(255, 255, 255)" height="5.1873000000000005px" id="rPmG4YvO9" transform="translate(137.672 35.204)" width="2.1310000000000002px"/><path d="M 1.414 0.328 C 0.807 0.328 0.465 0.699 0.513 1.181 C 0.56 1.642 1.319 1.729 1.67 1.843 C 2.122 1.993 2.786 2.134 2.786 2.789 C 2.792 3.472 2.261 3.993 1.414 3.993 C 0.446 3.993 0 3.197 0 2.669 L 0.437 2.669 C 0.437 3.174 0.781 3.672 1.414 3.672 C 2.005 3.672 2.397 3.308 2.369 2.796 C 2.334 2.304 1.749 2.227 1.461 2.12 C 0.949 1.943 0.108 1.836 0.083 1.167 C 0.054 0.492 0.661 0 1.414 0 C 2.384 0 2.754 0.819 2.754 1.274 L 2.318 1.274 C 2.318 0.803 1.977 0.328 1.417 0.328 Z" fill="rgb(255, 255, 255)" height="3.993300000000005px" id="yigdtUGQl" transform="translate(140.188 36.612)" width="2.7860503179292095px"/><path d="M 0.62 1.318 C 0.275 1.318 0 1.027 0 0.662 C 0 0.298 0.275 0 0.62 0 C 0.964 0 1.239 0.298 1.239 0.662 C 1.239 1.027 0.964 1.318 0.62 1.318 Z" fill="rgb(255, 255, 255)" height="1.317699999999995px" id="A9BLuCh5E" transform="translate(148.128 37.819)" width="1.2390000000000043px"/><path d="M 4.563 1.729 C 4.342 1.154 3.621 0.398 2.584 0.398 C 1.468 0.398 0.402 1.368 0.402 2.726 C 0.402 4.084 1.458 5.053 2.584 5.053 C 3.633 5.053 4.332 4.291 4.563 3.722 L 4.987 3.722 C 4.658 4.642 3.735 5.445 2.584 5.445 C 1.164 5.445 0 4.227 0 2.726 C 0 1.224 1.164 0 2.584 0 C 3.735 0 4.652 0.806 4.987 1.729 Z" fill="rgb(255, 255, 255)" height="5.444800000000001px" id="tMM9qOUdD" transform="translate(154.568 35.074)" width="4.986999999999995px"/><path d="M 3.092 0 L 3.092 0.328 L 0.446 0.328 L 0.446 2.194 L 3.029 2.194 L 3.029 2.528 L 0.446 2.528 L 0.446 5.191 L 0 5.191 L 0 0 Z" fill="rgb(255, 255, 255)" height="5.1907px" id="HdCqFaxpa" transform="translate(160.475 35.201)" width="3.092000000000013px"/><path d="M 2.577 0 C 4.003 0 5.154 1.217 5.154 2.726 C 5.154 4.234 4.003 5.445 2.577 5.445 C 1.151 5.445 0 4.227 0 2.726 C 0 1.224 1.157 0 2.577 0 Z M 0.398 2.726 C 0.398 4 1.375 5.033 2.58 5.033 C 3.785 5.033 4.762 4 4.762 2.726 C 4.762 1.452 3.785 0.418 2.58 0.418 C 1.375 0.418 0.398 1.445 0.398 2.726 Z" fill="rgb(255, 255, 255)" height="5.444800000000001px" id="YTLuHpHRE" transform="translate(164.231 35.074)" width="5.153999999999996px"/><path d="M 1.771 0.341 C 1.091 0.341 0.572 0.783 0.572 1.472 C 0.572 2.161 1.758 2.381 2.229 2.602 C 2.808 2.866 3.5 3.037 3.5 3.896 C 3.5 4.709 2.748 5.448 1.777 5.448 C 0.62 5.448 0 4.495 0 3.833 L 0.446 3.833 C 0.446 4.465 0.965 5.12 1.771 5.12 C 2.647 5.12 3.064 4.431 3.064 3.933 C 3.064 3.151 2.403 3.1 1.96 2.9 C 1.281 2.602 0.142 2.371 0.142 1.482 C 0.142 0.686 0.87 0 1.771 0 C 2.726 0 3.38 0.776 3.399 1.438 L 2.963 1.438 C 2.963 1.027 2.485 0.334 1.771 0.334 Z" fill="rgb(255, 255, 255)" height="5.4482px" id="DmJ2Y_yAT" transform="translate(172.85 35.067)" width="3.5px"/><path d="M 0.389 2.204 C 0.455 2.893 1.034 3.622 1.89 3.622 C 2.69 3.622 3.101 3.03 3.256 2.662 L 3.667 2.662 C 3.399 3.425 2.76 3.987 1.89 3.987 C 0.853 3.987 0 3.104 0 2 C 0 0.896 0.853 0 1.89 0 C 2.409 0 2.946 0.251 3.31 0.689 C 3.626 1.06 3.81 1.579 3.756 2.204 Z M 3.399 1.87 C 3.351 1.151 2.76 0.381 1.89 0.381 C 1.021 0.381 0.423 1.127 0.382 1.87 Z" fill="rgb(255, 255, 255)" height="3.986699999999999px" id="yMUVUZg9o" transform="translate(177.119 36.622)" width="3.7653500179975223px"/><path d="M 1.129 0.493 C 0.585 0.791 0.443 1.326 0.443 1.49 L 0.443 3.861 L 0 3.861 L 0 0.132 L 0.443 0.132 L 0.443 0.837 C 0.455 0.817 0.67 0.376 1.157 0.132 C 1.641 -0.102 1.938 0.045 1.951 0.055 L 1.951 0.383 C 1.932 0.376 1.546 0.262 1.129 0.496 Z" fill="rgb(255, 255, 255)" height="3.860826369589411px" id="px2Eh9pZT" transform="translate(181.697 36.611)" width="1.9509999999999934px"/><path d="M 0.487 0 L 1.764 3.211 L 3.042 0 L 3.519 0 L 1.992 3.722 L 1.533 3.722 L 0 0 Z" fill="rgb(255, 255, 255)" height="3.7224000000000004px" id="OCJj23ndt" transform="translate(184.021 36.752)" width="3.5190000000000055px"/><path d="M 0.436 0.328 L 0 0.328 L 0 0 L 0.436 0 Z M 0.436 5.191 L 0 5.191 L 0 1.331 L 0.436 1.331 Z" fill="rgb(255, 255, 255)" height="5.19069998703003px" id="N4v92LZAN" transform="translate(188.204 35.201)" width="1px"/><path d="M 3.256 1.331 C 3.162 1.067 2.713 0.405 1.884 0.405 C 1.116 0.405 0.376 1.06 0.376 2 C 0.376 2.94 1.129 3.602 1.884 3.602 C 2.678 3.602 3.13 3.003 3.256 2.669 L 3.667 2.669 C 3.392 3.438 2.751 3.993 1.884 3.993 C 0.853 3.993 0 3.104 0 2 C 0 0.896 0.853 0 1.884 0 C 2.754 0 3.446 0.625 3.667 1.331 Z" fill="rgb(255, 255, 255)" height="3.993300000000005px" id="x54xXVLtV" transform="translate(189.352 36.612)" width="3.6670000000000016px"/><path d="M 0.389 2.204 C 0.455 2.893 1.034 3.622 1.891 3.622 C 2.69 3.622 3.101 3.03 3.256 2.662 L 3.667 2.662 C 3.399 3.425 2.76 3.987 1.891 3.987 C 0.853 3.987 0 3.104 0 2 C 0 0.896 0.853 0 1.891 0 C 2.409 0 2.947 0.251 3.31 0.689 C 3.626 1.06 3.81 1.579 3.756 2.204 Z M 3.399 1.87 C 3.351 1.151 2.76 0.381 1.891 0.381 C 1.021 0.381 0.423 1.127 0.382 1.87 Z" fill="rgb(255, 255, 255)" height="3.986699999999999px" id="xkGiviUHf" transform="translate(193.747 36.622)" width="3.765350017997494px"/><path d="M 1.414 0.328 C 0.807 0.328 0.465 0.699 0.513 1.181 C 0.56 1.642 1.319 1.729 1.67 1.843 C 2.122 1.993 2.786 2.134 2.786 2.789 C 2.792 3.472 2.261 3.993 1.414 3.993 C 0.446 3.993 0 3.197 0 2.669 L 0.437 2.669 C 0.437 3.174 0.781 3.672 1.414 3.672 C 2.005 3.672 2.397 3.308 2.369 2.796 C 2.334 2.304 1.749 2.227 1.461 2.12 C 0.949 1.943 0.108 1.836 0.083 1.167 C 0.054 0.492 0.661 0 1.414 0 C 2.384 0 2.754 0.819 2.754 1.274 L 2.318 1.274 C 2.318 0.803 1.977 0.328 1.417 0.328 Z" fill="rgb(255, 255, 255)" height="3.993300000000005px" id="N8bEmWbbj" transform="translate(198.214 36.612)" width="2.7860503179292664px"/></svg>)


Archive perspective: 2024 themes and the outlook originally considered for 2025. Revised for clarity on September 15, 2026. This is not a current market forecast.
Market outlooks can be useful starting points, but a company sale should not depend on a broad prediction of rising deal activity. This archive article revisits the questions behind the 2024–2025 discussion: financing costs, strategic capability, technology investment and the difference between market headlines and a company-specific transaction case.
Read the market measures before reading the conclusion
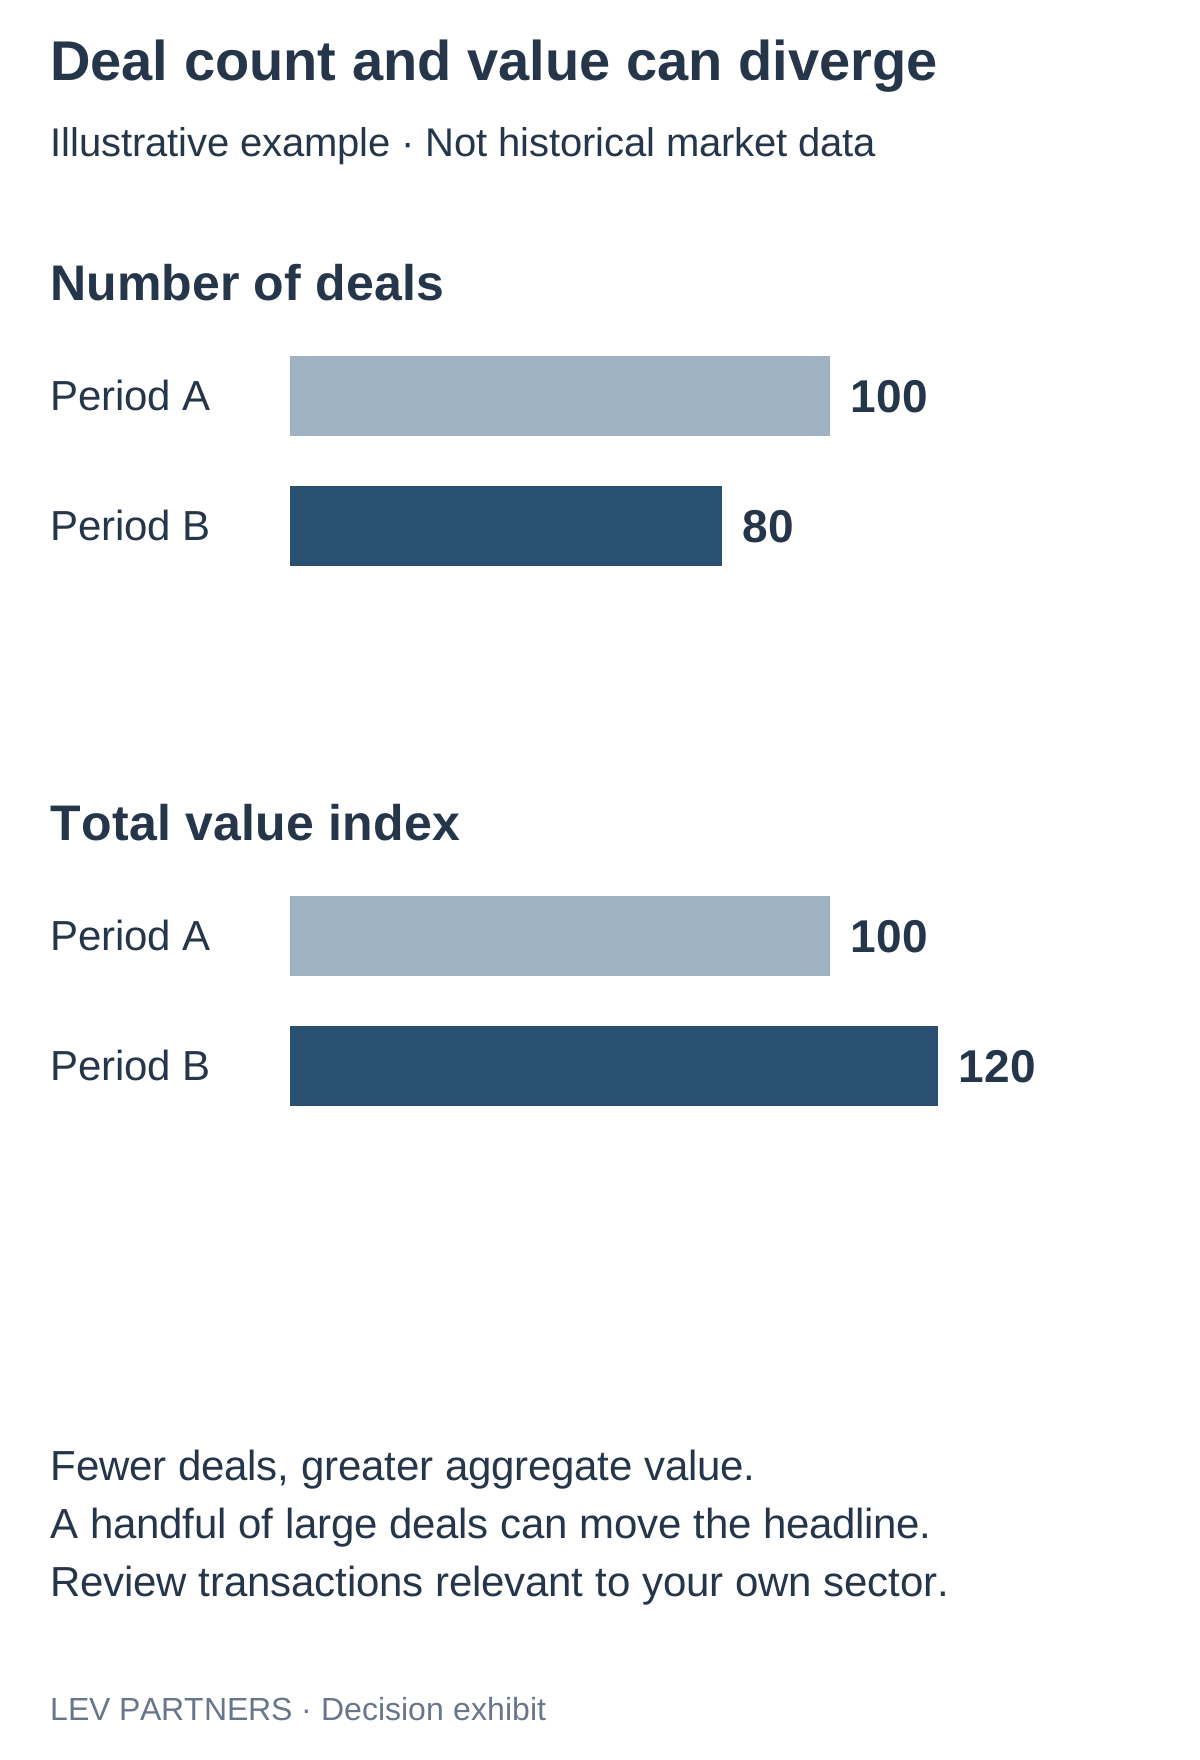
Deal count measures the number of transactions, while aggregate deal value measures their combined reported or estimated value. The two can move in opposite directions. A small number of very large transactions can lift total value even when fewer businesses change hands. Definitions also matter: announced and completed transactions, domestic and cross-border deals, and disclosed and estimated values are not identical datasets.
The exhibit is a numerical illustration, not historical market data. If the count falls from 100 to 80 while a value index rises from 100 to 120, it would be inaccurate to describe the whole market as uniformly stronger. For an owner, the relevant follow-up is what happened in comparable sectors, size ranges and transaction structures.
Separate a strategic theme from an acquisition case
Technology, energy transition and scale were prominent themes in the period’s deal discussions. A theme, however, does not establish that a particular target is attractive. An acquirer needs to understand which capability is missing, why ownership is the best way to obtain it and how value will be created after closing.
For an industrial business, the case may involve customer access, production specialization or supply-chain resilience. For a technology business, it may involve a product, an engineering team or recurring customer relationships. Each rationale requires different diligence. A presentation that simply labels the company “AI-enabled” or “sustainable” does not answer the investment question.
Financing conditions change the transaction, not just the price
When financing is expensive or uncertain, buyers may change leverage, defer consideration, seek seller participation or reduce the acquisition scope. Sellers should assess these structures alongside headline valuation. A transaction with a larger contingent component shifts risk differently from one with more cash at closing.
Company-level funding capacity remains important even when a market outlook is optimistic. Examine debt service, cash conversion, capital expenditure and the resources required to integrate the target. A buyer that can fund the purchase but cannot support the acquired business has not solved the full financing problem.
Treat regional opportunities as hypotheses to test
International buyer interest should be assessed through strategic fit and execution capability rather than geography alone. A buyer’s location does not prove sector knowledge, access to financing or willingness to undertake a cross-border acquisition. The relevant evidence includes past activity, management capacity, investment criteria and a credible process for the proposed transaction.
Owners should likewise distinguish the company’s international potential from its current readiness. Export sales may demonstrate demand, but contracts, margins, working capital and management continuity still need to withstand examination. Local legal, tax and regulatory considerations should be incorporated with qualified advisers instead of treated as a final administrative step.
The lesson for an owner reading an old outlook today
Use historical material to understand the questions that shaped decisions, not to recycle past predictions as current facts. A practical preparation pack includes reconciled financials, a supported earnings bridge, customer analysis, a funding plan and a clear shareholder objective. Update these with current evidence before approaching counterparties.
Lev Partners supports company-specific preparation and transaction assessment across international markets. The useful question is not whether a past forecast was optimistic, but whether the business can present a credible investment case and evaluate the terms available to it now.
Explore M&A advisory and read our 2026 selective-market perspective.
Your M&A advisory contact
Erim N. Kargacı — Founding Partner and Head of M&A, Lev Partners. Erim leads Lev’s M&A advisory and supports owners considering investment, acquisitions or a company sale. He is also listed among Endeavor Türkiye’s mentors.
Contact us today to discuss your transaction. Tell us about your business and objectives through our confidential contact form →.